Draw as you need
Access funds when costs arise, rather than taking a lump sum upfront.
FLEXIBLE ACCESS TO YOUR EQUITY
Funds when you need them.
Interest only on what you use.
A line of credit is a revolving facility secured by your home. Draw funds up to a set limit for planned costs, emergencies or investments, and pay interest only on what you’ve drawn. We compare limits, fees and redraw terms across our lender panel. Personal guidance from Ausfirst Lending Group’s mortgage brokers in Brisbane and on the Sunshine Coast.
Excellent · 35 Google reviews
HOW IT WORKS
Once approved, you can withdraw up to a set limit, repay and redraw again. Because it’s secured by your property, rates are generally lower than credit cards or personal loans.
Access funds when costs arise, rather than taking a lump sum upfront.
Interest applies to the amount drawn, not the whole limit.
A revolving facility you can use again and again, up to your limit.
Best for disciplined borrowers. A line of credit suits people with strong budgeting habits and changing costs.
Start with a free chatPOSSIBLE BENEFITS
A line of credit can offer flexibility other loans can’t, if it’s used for the right purpose.
Funds available as you need them, for planned costs or the unexpected.
No interest on the undrawn part of your limit.
Usually cheaper than credit cards or personal loans.
Withdraw through standard banking tools once set up.
A QUICK COMPARISON
| What you compare | Offset | Redraw | Line of credit |
|---|---|---|---|
| Access to | Your savings | Extra repayments | Up to your limit |
| Interest | Reduced by balance | On loan balance | On amount drawn |
| Discipline needed | Low | Medium | High |
| Suits | Everyday savings | Occasional access | Ongoing or variable costs |
Features, fees and conditions vary by lender. A broker can clarify which suits you.
Compare my optionsKNOW YOUR NUMBERS
With a lump-sum loan, you pay interest on the full amount from day one. With a line of credit, you pay only on what you’ve drawn, which can cost less when funds are needed gradually.
We compare limits, rates and annual fees, so the flexibility doesn’t cost more than it saves.
Illustration only. Interest-only on the drawn balance at a steady rate. The full-limit figure shows yearly interest plus the fee if the whole limit were used. Fees and rates vary.
Check my actual optionsFACTORS TO KEEP IN MIND
Before proceeding, think about your long-term financial habits. The same features that make a line of credit flexible can make it easy to overuse.

Redrawing is simple, which can lead to spending more than planned if it’s not monitored. Because it’s secured by your home, missed repayments put your property at risk.
A clear purpose and a plan to repay the principal make all the difference.
Some lines of credit are interest-only for an extended period. That keeps repayments low, but the balance doesn’t fall unless you actively repay it.
Annual or package fees may apply, and some lenders review the facility periodically. Check the terms on access and redraw before committing.
Line of credit features, fees and limits vary by lender and can change.
Let’s see if it fits. We’ll look at your equity, habits and goals, and suggest alternatives if a line of credit isn’t right.
Check my next stepsWHAT LENDERS ASSESS
Lenders usually assess you as though the full limit is drawn, even if you don’t use it.
Usually up to 80% of your home’s value, less your existing loan. A valuation may be required.
Income and expenses are assessed against the full limit.
A clean history shows you manage revolving credit well.
Some lenders restrict business or speculative uses.
WHAT IT CAN BE USED FOR
A line of credit works best for costs that arrive over time, rather than one fixed amount.
Pay trades and suppliers as invoices arrive.
Draw funds when an opportunity comes up.
Cover school or university fees term by term.
A buffer for emergencies, repaid when you can.
Need one fixed amount instead? A home loan top-up or equity release may suit better.
Explore home equity loansHOW WE CAN HELP
Line of credit products vary in fees, structures and redraw rules. We help you compare them and avoid ones that don’t suit you.
UNDERSTAND
What you’ll use it for, your budgeting habits and your goals.
REVIEW
We estimate your available equity and a sensible limit.
COMPARE
We compare lender criteria, fees, redraw terms and approval timeframes.
APPLY
We help gather your documents and lodge the application.
SET UP
Once approved, your facility is set up and ready to draw.
SUPPORT
We review your facility as your needs and the market change.
SPEAK WITH US
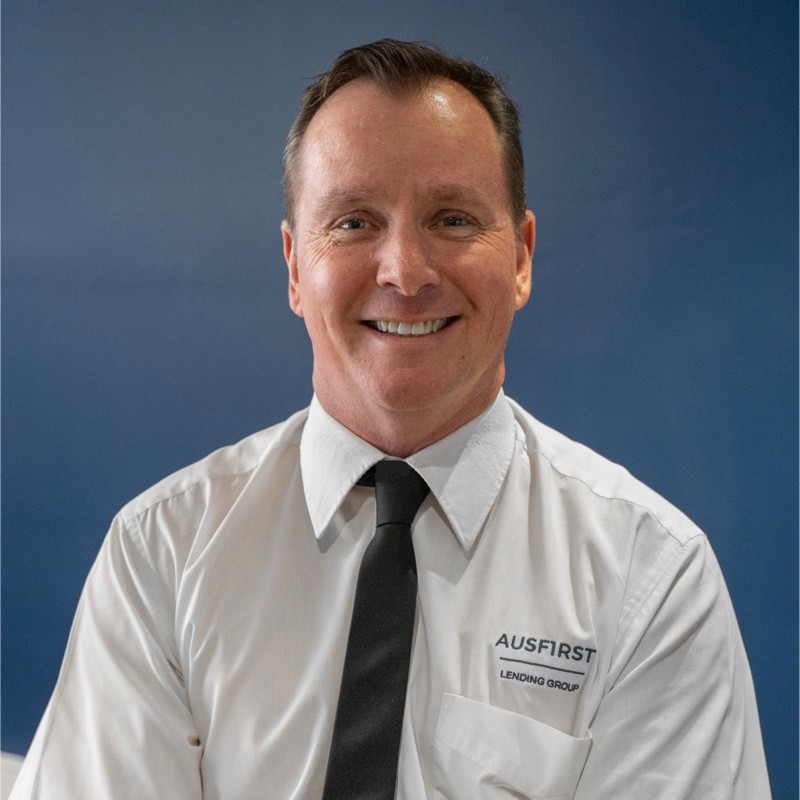
You’re looked after by someone who treats your financial success as his own.
Richard brings more than 30 years of hands-on broking experience. He takes the time to understand your position, equity and repayment preferences before suggesting whether a line of credit fits your goals.
If another structure suits you better, such as an offset, redraw or equity top-up, we’ll tell you.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Debbie made the process of buying a new house frictionless, by providing excellent support throughout”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions we’re asked most about line of credit home loans. Your habits and goals matter, so we’re happy to talk through the detail.
Ask a questionHome improvements, investments, education or short-term needs. Some lenders restrict business or speculative uses, so check the terms upfront.
It may suit borrowers with fluctuating costs and strong repayment discipline. A redraw facility or offset account may fit better if you mainly want access to savings.
Many lenders allow up to 80% of your home’s value, less your current loan. A valuation may be required, and your income must support the full limit.
Usually, yes. Lenders tend to assess a line of credit as if it’s fully drawn, which can reduce what you can borrow elsewhere.
Quicker access to funds than some alternatives, with withdrawals through standard banking tools. Watch for fees and conditions on access or redraw.
Often, yes. Converting to a standard loan with principal and interest repayments can help you clear the balance. We can review your options.
READY TO START THE CONVERSATION?
Tell us what you’d like to use a line of credit for. We’ll look at your equity, habits and goals, and whether this structure suits you.
Your equity and a sensible limit
Fees, redraw and rates compared
Alternatives if it isn’t the right fit
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, 9 am–5 pm
YOUR FREE CHAT
Send our team a little about what you need.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form