Add value to your home
Well-planned improvements may lift your property’s value, depending on the work and market conditions.
RENOVATE WITH A PLAN
Love where you live.
Fund it the right way.
From a new kitchen to a full extension, the right finance keeps your project and your budget on track. We help you compare renovation loans, equity options and lender requirements from our panel. Personal guidance from Ausfirst Lending Group’s mortgage brokers in Brisbane and on the Sunshine Coast.
Excellent · 35 Google reviews
WHAT ARE RENOVATION LOANS?
A renovation loan funds home improvements, from cosmetic updates to structural changes and extensions. Many are structured around the costs and timeline of the work, rather than a single lump sum.
Well-planned improvements may lift your property’s value, depending on the work and market conditions.
Update your home’s layout, comfort and function without the cost and disruption of moving.
Construction loans release funds in stages, which can help you manage cash flow through major works.
Still getting quotes? That’s a good time to talk. Knowing your borrowing position helps you set a realistic budget.
Start with a free chatWAYS TO FUND YOUR RENOVATION
The right option depends on the scope of your project, your equity and your budget. We explain the trade-offs of each.
For major renovations or rebuilds. Funds are released in stages as work is completed, with lender sign-off at each stage.
Increase your existing mortgage using available equity. Often a lower rate than unsecured borrowing, with higher repayments to plan for.
Replace your current loan with a new one that releases equity, and potentially gain a sharper rate or better features at the same time.
Draw on your equity as you need it, similar to a credit card. Useful when costs land over time, but it needs discipline.
For smaller, non-structural jobs like a kitchen or bathroom refresh. If you’ve made extra repayments, redraw may cover it instead.
A QUICK COMPARISON
| What you compare | Personal loan | Using equity |
|---|---|---|
| Project size | Smaller upgrades | Small to major works |
| Interest rate | Usually higher | Often lower |
| Loan term | Shorter | Longer, more interest over time |
| Security | Usually unsecured | Secured by your home |
Rates, limits and terms depend on the lender and your circumstances. Spreading costs over a home loan term can increase the total interest you pay.
Compare my renovation optionsCAN I USE EQUITY TO RENOVATE?
Equity is your home’s current value minus what you owe. Lenders typically let you borrow up to 80% of the value, less your loan balance. That’s your usable equity.
On an $800,000 home with $400,000 owing, total equity is $400,000, but usable equity is around $240,000. Borrowing above 80% may be possible with LMI, at extra cost.
Illustration only, not a borrowing assessment. Based on your estimated value; the lender’s valuation may differ. Above 80%, LMI usually applies. Your income and expenses also determine how much you can borrow.
Check my actual optionsBEFORE YOU COMMIT
Renovation finance adds to your debt and your repayments. We help you test the budget, allow for overruns and choose a structure you can comfortably carry.
Renovation costs often run over estimates because of hidden issues, price changes or delays. A contingency buffer helps you finish the job without scrambling for extra funds.
Get detailed quotes, confirm council requirements early and know what your repayments will be before work starts.
Borrowing more raises your monthly repayments. Extending your mortgage or using a personal loan can also increase the interest you pay over time.
We show you the repayment impact before you apply.
Some lenders apply stricter criteria to properties undergoing major structural work. And while renovations can add value, market changes can affect your return.
We match your project to lenders whose policies suit it.
Lender policies, LVR limits and fees vary and can change. Confirm current requirements with your lender before starting work.
Let’s pressure-test your budget. We’ll compare options and show what each means for your repayments.
Check my next stepsHOW TO APPLY
A well-prepared application can make approval smoother. Requirements vary by lender and by the scale of your project.
Income, expenses, existing debts and credit history set how much you can borrow and repay.
Recent payslips, tax returns or bank statements showing steady income.
Builder contracts and detailed renovation plans, especially for major or structural works.
Relevant council approvals for structural modifications or extensions.
THE RIGHT STRUCTURE MATTERS
How funds are released matters as much as the rate. We help you choose a structure that fits your project timeline and budget.
Progress payments released at each build stage. You typically pay interest only on what’s been drawn.
Add to your existing loan in one step. Your repayments rise with the larger balance.
Draw funds as invoices arrive, up to an approved limit. Rates can be higher than a standard home loan.
A lump sum for non-structural upgrades, with a shorter term and usually a higher rate.
Renovating an investment property or adding a granny flat? We’ll talk through the extra lending considerations.
Talk about my projectFROM FIRST CHAT TO FIRST TRADIE
We explain each stage, prepare the application with you and keep you informed until your funds are available.
UNDERSTAND
Meet by phone, Zoom or in person. Tell us about the project, your quotes and your timeline.
GATHER
We collect income documents, loan details and project paperwork, and estimate your usable equity.
ANALYSE & PLAN
We compare construction loans, top-ups, refinancing and other options against your budget and repayments.
APPLY
We submit your application with plans, contracts and approvals, and liaise with the lender on valuation.
FINALISE
Funds are released as a lump sum or in stages, depending on your loan. We keep you informed throughout.
SUPPORT
Once the renovation is done, your property value may have changed. We review your loan as your needs evolve.
WHAT MAKES AUSFIRST DIFFERENT
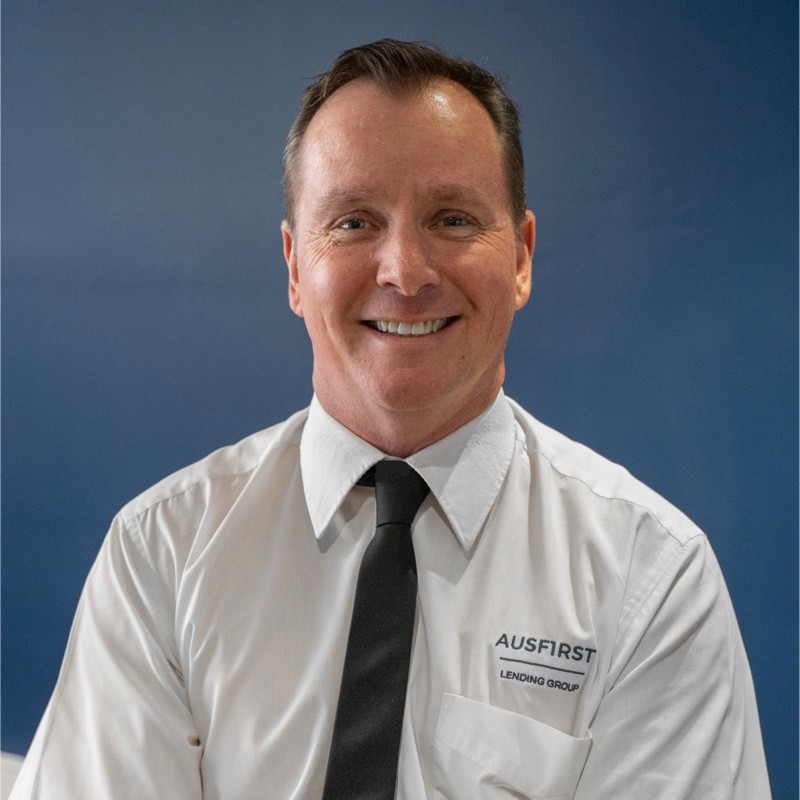
You’re looked after by someone who treats your financial success as his own.
Richard brings more than 30 years of hands-on broking experience. He takes the time to understand your renovation plans, finances and long-term goals before comparing options from our panel.
Whether it’s a kitchen update, a major extension or improving an investment property, you get clear advice, regular updates and the same team from application to settlement.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Debbie made the process of buying a new house frictionless, by providing excellent support throughout”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions we’re asked most about funding renovations. Your circumstances matter, so we’re happy to talk through the detail.
Ask about my projectYes. Smaller upgrades may suit a personal loan. Larger projects are often funded with a construction loan, a home loan top-up or refinancing. If you’ve made extra repayments, redraw may cover the cost instead.
It depends on the size of the project and your finances. Construction loans suit major structural work because funds are released in stages. Personal loans can be quicker for smaller jobs. If you have equity, a top-up or refinance may offer a lower rate and more flexible repayments.
Many lenders offer construction loans for larger projects and personal loans for smaller ones. Eligibility and requirements vary, and some lenders are stricter on major structural work.
It depends on your property value, loan balance, income and borrowing capacity. Using equity, many lenders allow up to 80% of your property’s value less what you owe, or more with LMI. Personal loans are often between $5,000 and $50,000, subject to the lender’s assessment.
Often, yes. Equity is your property’s value minus your mortgage balance. Depending on the lender, you can access it through a home loan top-up, refinancing or a line of credit.
It can be cost-effective, as home loan rates are often lower than personal loan or credit card rates. But a larger balance means higher repayments, so consider your long-term position and whether the work is likely to add value.
A top-up increases your existing mortgage, refinancing replaces your loan and releases extra funds, and a line of credit gives flexible access to equity. The right option depends on your finances and project.
Yes. Refinancing can release equity and may also improve your rate or loan features. Weigh any break, discharge and setup fees against the benefits first.
Learn more about refinancingLET’S MAKE A START
You don’t need final quotes to get started. Tell us about your project, and we’ll help you understand your borrowing position, equity and the right way to fund it.
A clear look at your usable equity
Loan structures and repayments compared
Personal guidance from an experienced team
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, 9 am–5 pm
YOUR FREE RENOVATION CHAT
Send our team a little about your plans.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form