Lower interest rates
Secured lending usually costs less than credit cards or personal loans.
LEVERAGE YOUR EQUITY
Your home has grown in value.
Put that equity to work.
Renovating, investing, consolidating debt or planning a major purchase, the equity in your home can help. We work out how much you could access, compare the ways to release it across our lender panel and check the repayments suit your budget. Personal guidance from Ausfirst Lending Group’s mortgage brokers in Brisbane and on the Sunshine Coast.
Excellent · 35 Google reviews
A QUICK INTRODUCTION
A short look at how releasing equity works, and when it’s worth it.
Equity is your home’s value minus what you owe. We work out how much you could access, compare the ways to release it and check the repayments suit your budget.
Renovating, consolidating debt or investing, we’ll show you whether the numbers stack up before you commit.
HOW HOME EQUITY LOANS WORK
Equity is your home’s current value minus what you still owe. Because the borrowing is secured by your home, rates are usually lower and limits higher than unsecured loans like credit cards or personal loans.
Secured lending usually costs less than credit cards or personal loans.
Fund a renovation, a deposit or a major expense without draining your savings.
Take a lump sum, a separate split or a line of credit, depending on how you’ll use it.
Not sure how much equity you have? We’ll estimate it and show what releasing it would mean for your repayments.
Start with a free chatWAYS TO ACCESS YOUR EQUITY
The right method depends on what you’re funding, when you need the money and how your current loan is set up.
Increase your existing home loan to receive a lump sum for a known cost, such as a renovation.
Borrow through a new split, keeping each purpose separate. Useful when funds go towards an investment.
Draw funds as needed up to a limit and pay interest only on what you use. Best for costs spread over time.
Move to a new lender and release equity at the same time, potentially with a sharper rate or better features.
A QUICK COMPARISON
| What you compare | Lump sum | Line of credit |
|---|---|---|
| How funds arrive | All at once | Drawn as needed |
| Interest charged | On the full amount | Only on what you use |
| Best for | One known cost | Ongoing or variable costs |
| Repayments | Set schedule | Needs discipline |
Rates, features and fees vary by lender. Borrowing more increases your loan balance and repayments.
Compare my optionsHOW MUCH COULD YOU ACCESS?
Most lenders let you borrow up to 80% of your home’s value, less your current loan. Above 80%, LMI usually applies. Lenders often value conservatively, so your accessible equity may be lower than an online estimate.
Your income and expenses also decide how much you can comfortably borrow. We check both.
Illustration only, not a borrowing assessment. Based on your estimate; the lender’s valuation may differ. Your income, expenses and credit history also determine how much you can borrow.
Check my actual optionsUSING EQUITY TO INVEST
Equity can help you invest sooner without saving a large cash deposit. It also adds to your debt, so the plan needs to work for your budget and risk tolerance.
The most common use is a deposit for an investment property, so you can enter the market sooner and potentially benefit from rent and growth.
Some homeowners use equity to start a business, buy shares or fund other income-producing assets. Get licensed financial advice before borrowing to invest.
Interest may be tax deductible if the funds are used for income-producing purposes, like an investment property. Renovating your own home or consolidating personal debt usually doesn’t qualify.
Confirm with your tax adviser.
Well-planned renovations may lift your home’s value, improving how you live and the equity available later. Results depend on the work and the market.
We provide credit assistance only, not tax or investment advice. Speak with your accountant or a licensed financial adviser about your strategy.
Let’s structure it properly. Keeping investment and personal borrowing separate makes tracking much simpler.
Check my next stepsELIGIBILITY CRITERIA
Lenders want to know you can comfortably repay the larger loan. These are the main factors.
Usually borrowing up to 80% of the value, less your current loan, keeps a buffer and avoids LMI.
Payslips or tax returns, or BAS and profit and loss statements if you’re self-employed.
Existing debts, credit limits and your credit history all affect your borrowing capacity.
A formal valuation. Rural or unusual properties may face extra criteria.
KNOW THE COSTS
Understanding the costs upfront helps you budget and avoid surprises. We include them when comparing your options.
LMI usually applies if your total borrowing exceeds 80% of your home’s value.
Some lenders charge to increase or restructure a loan and value the property.
Releasing equity through a new lender can involve discharge or break costs.
Spreading a short-term cost over a long term can mean paying more interest overall.
Using equity to buy your next property? We’ll plan the deposit, costs and repayments on both loans.
Talk about my plansFROM FIRST CHAT TO SETTLEMENT
We estimate your equity, compare the options and manage the application through to settlement.
UNDERSTAND
Meet by phone, Zoom or in person. Tell us what you’d like to fund and your timeline.
GATHER
We collect income documents and loan details, and look at your home’s likely valuation.
ANALYSE & PLAN
We compare top-ups, splits, lines of credit and refinancing, including rates, fees and terms.
APPLY
We gather your credit report, income and property details and liaise with the lender on valuation.
FINALISE
We keep you informed until your funds are available.
SUPPORT
We review your loan as values, rates and your goals change.
WHAT MAKES AUSFIRST DIFFERENT
You’re looked after by someone who treats your financial success as his own.
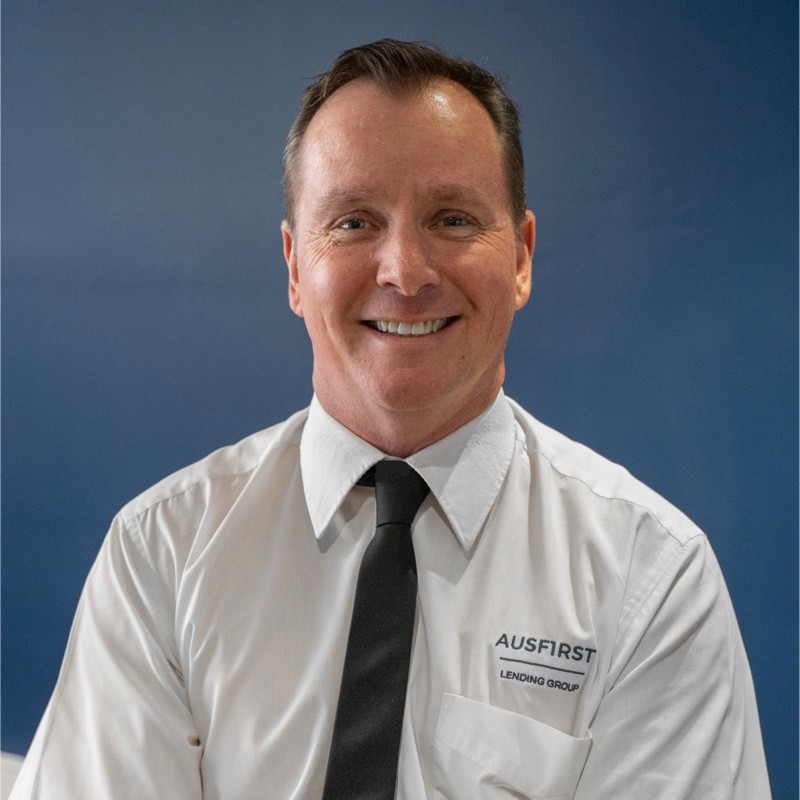
Richard brings more than 30 years of hands-on broking experience. He takes the time to understand your circumstances before comparing home equity options from our panel.
Whether you’re renovating, consolidating debt, buying an investment property or covering a major cost, you get clear advice on how much you could access, regular updates and the same team through to settlement.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Debbie made the process of buying a new house frictionless, by providing excellent support throughout”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions we’re asked most about borrowing against your home. Your circumstances matter, so we’re happy to talk through the detail.
Ask about my equityMany lenders allow up to 80% of your home’s value, less your current loan. Some allow more with LMI. Your income and expenses also determine how much you can comfortably borrow.
Yes. Equity is commonly used as the deposit for an investment property, so you don’t need to save a large cash deposit. Your borrowing capacity still needs to cover both loans.
Yes. A top-up, split or line of credit can fund renovations. A larger balance means higher repayments, so we check the numbers first.
It may be if the funds are used for income-producing purposes, such as an investment property or shares. It usually isn’t for personal uses like renovating your home. Check with your tax adviser.
Not always. Your current lender may increase your loan or add a split. Refinancing can make sense if another lender offers better terms or features.
Usually only if your total borrowing exceeds 80% of your home’s value. LMI adds to the cost, so we factor it into your options.
It depends on the lender and whether a valuation and full application are needed. A top-up with your current lender is often faster than refinancing.
LET’S MAKE A START
Tell us what you’d like to fund. We’ll estimate your usable equity, compare the ways to release it and show what it means for your repayments.
A clear look at your usable equity
Top-ups, splits and lines of credit compared
Personal guidance from an experienced team
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, 9 am–5 pm
YOUR FREE EQUITY CHECK
Send our team a little about your plans.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form