First-time investors
- Understand your borrowing power and budget
- Compare loan types suited to a first investment
- Explore low deposit and LMI options
- Get pre-approval before you search
BUILD YOUR PORTFOLIO
Grow your property portfolio.
On the right structure.
Whether it’s your first investment property or your fifth, how the loan is set up matters as much as the rate. We compare investment loans from our lender panel and help you structure them around your strategy. Personal guidance from Ausfirst Lending Group’s mortgage brokers in Brisbane and on the Sunshine Coast.
Excellent · 35 Google reviews
WHO THIS IS FOR
Investors have different goals, incomes and timelines. Whether you’re buying your first rental or scaling a portfolio, we match the loan to your strategy.
Not sure where to start? We’ll look at your equity, income and goals, then explain your options.
Start with a free chatWHY STRUCTURE MATTERS
Investment loans have their own lending criteria. Lenders treat rental income, existing debts and multiple properties differently, and those differences affect how far you can grow.
Some lenders count more of your rental income or assess existing debts differently. We compare policies across our panel to find those that fit your plans.
How loans are set up today affects your flexibility later. We plan the structure with your next property in mind.
Release equity from your home or existing investments to fund a deposit, without dipping into savings.
Mortgage brokers providing regulated credit assistance must act in your best interests, considering costs, features and your needs.
A QUICK COMPARISON
| What you compare | One bank | Ausfirst |
|---|---|---|
| Loan choice | That bank’s products | Our lender panel |
| Investor policy | One lender’s rules | Multiple lender policies |
| Portfolio structure | Within one lender | Planned across lenders |
| After settlement | When you ask | Ongoing loan reviews |
Our panel does not include every lender or every loan in the market. A bank can also provide application support.
Compare my investment optionsKNOW YOUR NUMBERS
Rental yield shows how much income a property earns relative to its price. Gross yield is a quick comparison; net yield, after costs, is closer to what you’ll actually earn.
We look at yield alongside your repayments, buffers and borrowing capacity, so the next purchase doesn’t stall the one after.
Illustration only, not financial advice or a borrowing assessment. Excludes loan repayments, vacancy, tax and capital growth. Annual costs can include rates, insurance, strata and management fees.
Check my actual optionsWHAT IS AN INVESTMENT LOAN?
An investment loan funds a property you plan to rent out rather than live in. Lenders assess it differently from an owner-occupied loan, and the structure you choose shapes your cash flow.
Investment loans often carry higher rates and stricter serviceability checks than owner-occupied loans. Most lenders look for a 10–20% deposit, or equity from a property you already own.
Lenders also count only part of your expected rent when assessing what you can borrow. Pre-approval sets a realistic budget before you start searching.
You pay only interest for an agreed term, often up to five years, which can help cash flow. Your loan balance doesn’t reduce, and repayments rise when the term ends.
Interest-only rates are often higher than principal and interest rates.
Repayments cover interest and reduce your balance, building equity over time. That equity can later support your next purchase.
Repayments are higher, so we check your cash flow can carry them.
Tax treatment of investment loans depends on your circumstances. Speak with your accountant or a licensed financial adviser about tax and investment strategy.
Let’s check your starting position. We’ll look at your deposit or equity, borrowing capacity and the right structure.
Check my next stepsINVESTMENT SCENARIOS
Three examples of how loan structure can support different strategies. Every investor’s situation is different, and results depend on the property, the market and your circumstances.
A Brisbane teacher buys a $540,000 apartment with an 11% deposit, using a profession-based LMI waiver and an interest-only loan for two years.
Next step: switch to principal and interest and use equity towards the next purchase.
A dual-income couple used an offset account and extra repayments on a $720,000 townhouse, then released equity for a second investment.
Rent from both properties covers most of their combined repayments.
A consultant’s SMSF buys a $720,000 commercial unit leased to medical tenants, funded through a limited recourse borrowing arrangement.
SMSF borrowing is complex; get advice from a licensed SMSF specialist.
Scenarios are illustrative. Past performance is not a reliable indicator of future returns, and capital growth is not guaranteed.
BEFORE YOU APPLY
Investment lending criteria are often stricter than for a home you live in. These are the main factors lenders weigh.
Your salary and other regular income, and how stable it is, set the base for what you can borrow.
Lenders count a portion of the expected rent, usually after a discount for vacancy and costs.
Current home and investment loans, car loans and credit card limits all reduce your capacity.
Most lenders want 10–20% from savings or equity. Less may be possible with LMI or a guarantor.
THE RIGHT STRUCTURE MATTERS
The right mix depends on your cash flow, tax position and plans for the portfolio. We help you compare features against your strategy.
Lower repayments for a set term. The balance doesn’t reduce and repayments rise when the term ends.
Higher repayments that reduce your loan balance and build equity over time.
Fix part of the loan for certainty and keep the rest variable for flexibility.
Reduce the balance used to calculate interest while keeping savings accessible.
Buying through a trust, a company or your SMSF? We’ll talk through the extra lending considerations.
Talk about my structureFROM FIRST CHAT TO SETTLEMENT
We explain each stage, prepare the application with you and keep you informed until settlement, then review your loans as your portfolio grows.
UNDERSTAND
Meet by phone, Zoom or in person. Tell us about your strategy, timeline and existing properties.
GATHER
We collect income documents, loan details and rental statements, and review your equity position.
ANALYSE & PLAN
We compare lenders, policies and features, and plan the structure with your next purchase in mind.
APPLY
Once you’ve found a property, we finalise the application and liaise with the lender on valuation and approval.
FINALISE
We coordinate with your lender and conveyancer and keep you informed through to settlement.
SUPPORT
We review your loans as rates, values and your goals change, including when equity may support your next purchase.
WHAT MAKES AUSFIRST DIFFERENT
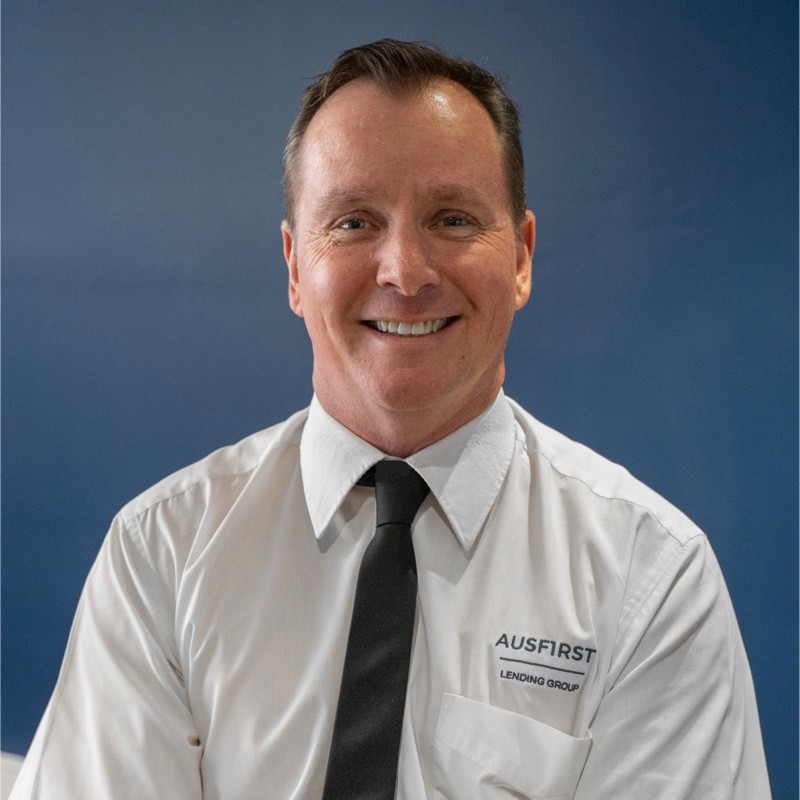
You’re looked after by someone who treats your financial success as his own.
Richard brings more than 30 years of hands-on broking experience. He takes the time to understand your finances, investment objectives and future plans before comparing options from our panel.
Whether it’s your first investment property, refinancing an existing loan or using equity for the next purchase, you get clear advice, regular updates and the same team from application to settlement.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Debbie made the process of buying a new house frictionless, by providing excellent support throughout”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions we’re asked most about investment lending. Your circumstances matter, so we’re happy to talk through the detail.
Ask about my situationA loan used to buy an asset, such as property, that you expect to earn income or grow in value. For property, it usually means a home you plan to rent out rather than live in.
Yes, if you meet the lender’s criteria. Lenders assess your income, credit history, existing debts and the expected rent. Investment loans often have higher rates and stricter requirements than owner-occupied loans.
Most lenders want a 10–20% deposit. You may be able to borrow the full purchase price by using equity in an existing property as security, or with a family guarantor.
Yes. Margin loans and other investment lending can fund shares or managed funds. They carry different risks, so get licensed financial advice before borrowing to invest.
Often, yes. Refinancing or a line of credit can let you access equity to fund a new purchase without a cash deposit. Borrowing more increases your risk and repayments.
We compare loans across our panel, including major banks and specialist lenders, handle the paperwork and liaise with the lender. Our service is free for you; lenders pay us a commission, which we disclose.
A lender can only offer its own products. A broker compares options across multiple lenders and their investor policies, which can matter more as your portfolio grows.
LET’S MAKE A START
You don’t need a property picked out. Tell us where you’re at, and we’ll help you understand your borrowing position, equity and the right structure for your next purchase.
A clear look at your borrowing capacity
Equity, structure and lender options explained
Personal guidance from an experienced team
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, 9 am–5 pm
YOUR FREE INVESTMENT CHAT
Send our team a little about your goals.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form