Interest on what’s drawn
Drawn $100,000 of a $500,000 loan? You pay interest on $100,000.
CONSTRUCTION LOAN BROKER
Build with confidence.
Finance explained in plain English.
Building lets you design a home around your life, but a standard home loan won’t cover most builds. Construction loans release funds in stages as your build progresses. We help first home builders, families and small developers find the right lender, then coordinate progress payments through to handover. Personal guidance from Ausfirst Lending Group in Caloundra.
Excellent · 35 Google reviews
WHAT MAKES A CONSTRUCTION LOAN DIFFERENT
A construction loan pays your builder as the build reaches key milestones. It keeps interest lower while you build, but adds paperwork and approvals at each stage.
Drawn $100,000 of a $500,000 loan? You pay interest on $100,000.
Paid at base, frame, lock-up, fixing and completion, usually after an inspection or invoice.
Once complete, the loan converts to principal and interest like a standard mortgage.
Building your first home? Queensland’s $30,000 grant and stamp duty relief may apply. We’ll check what you qualify for.
See first home supportBUILD TYPES WE HELP WITH
Not every build is the same, and lenders know that. We match your project to lenders experienced in your build type.
Finance coordinated across land and build in new estates.
A build on your vacant land, or demolition plus a new home.
Live in one and rent the other, or house extended family.
Townhouses or multiple dwellings, structured around the timeline.
A QUICK COMPARISON
| What you compare | Home loan | Construction loan |
|---|---|---|
| Funds released | All at settlement | In stages |
| Repayments | From day one | Interest on drawn amount |
| Documents | Contract of sale | Build contract, plans, insurance |
| Inspections | One valuation | At each stage |
Drawdown terms and requirements vary by lender.
Compare my optionsKNOW YOUR NUMBERS
During the build you pay interest only on what’s drawn, so costs rise as each stage is paid. Once complete, repayments switch to principal and interest.
We map the cash flow before you sign, so there are no surprises.
Illustration only. Assumes the land loan is fully drawn and build funds are drawn evenly over the build. P&I over 30 years. Excludes fees and variations.
Check my actual optionsFIRST HOME BUILDERS IN QUEENSLAND
If you’re building your first home in Queensland, several incentives could save you thousands.
The First Home Owner Grant is $30,000 for eligible new homes valued under $750,000, continued in the 2026–27 State Budget.
Eligible first home buyers building a new home, or buying vacant land to build on, may pay no transfer duty. From 1 August 2026, duty concessions require Australian citizenship, permanent residency or specified retiree status.
Eligible first home buyers may build with a 5% deposit and no LMI through a participating lender.
Some lenders reduce or waive LMI for eligible professionals.
See LMI waived loansChecked October 2026. Grant and duty rules are set by the Queensland Revenue Office and can change.
Let’s check what you qualify for. We’ll help you check eligibility and lodge the paperwork correctly.
Check my next stepsWHAT LENDERS NEED
Owner-builder loans are possible with some lenders, often needing a 30–40% deposit and stronger documents.
With a licensed builder, setting scope, cost and stages.
Plans and specifications approved to proceed.
Home warranty and builder’s insurance in place.
Payslips and returns, or BAS and an accountant’s letter.
COMMON FIRST-BUILD MISTAKES
Most can be avoided with the right preparation.
Site works, fees, landscaping, upgrades and a contingency buffer.
Lock decisions in before signing to avoid fees and delays.
Know your limit before committing to land or a contract.
Insurance, approvals and payment claims often fall to you.
Self-employed or a tradie? Low-doc construction options may suit.
Explore self-employed loansFROM APPROVAL TO KEY HANDOVER
We stay involved the entire way, not just during approval.
ASSESS
Your goals, timeline and borrowing capacity for a realistic budget.
PRE-APPROVAL
We compare lenders and secure pre-approval.
CONTRACT
Fixed-price contract, approved plans and insurance.
APPROVAL
We walk through the structure, rate and drawdown terms.
BUILD
We help manage claims and inspections at each stage.
HANDOVER
Final payment, loan conversion and your new keys.
HOW WE MAKE IT EASIER
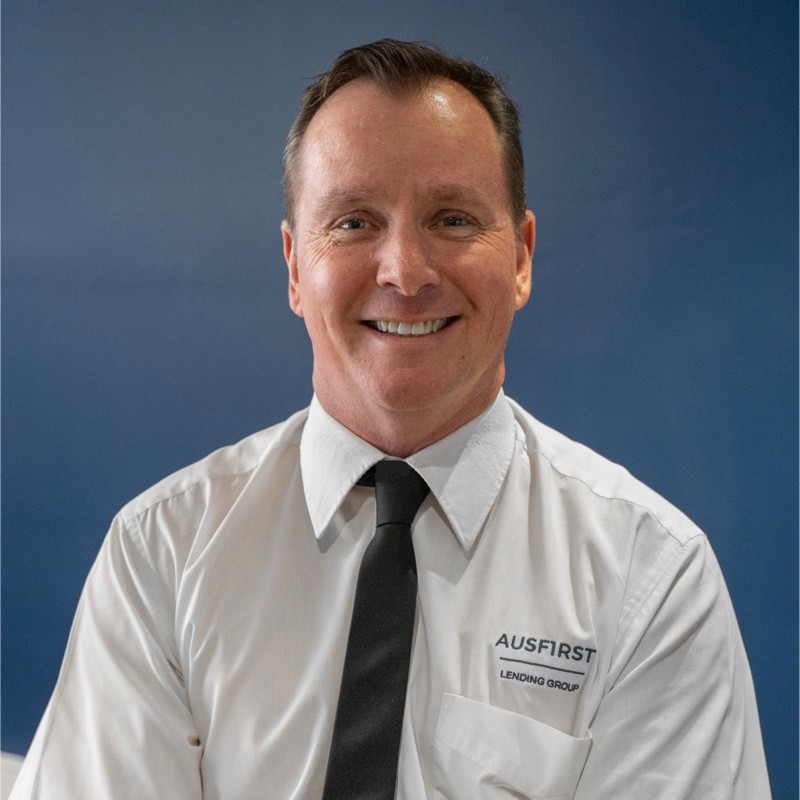
You’re looked after by someone who treats your financial success as his own.
Richard brings more than 30 years of broking experience. We take the time to understand your goals, income and timeline, prepare the extra paperwork and compare lenders’ construction policies.
We coordinate with your builder on progress payments, invoices and inspections, so you’re not stuck in admin while you build.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Debbie made the process of buying a new house frictionless, by providing excellent support throughout”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions first-time builders ask us most. Every build is different, so we’re happy to talk through the detail.
Ask about my buildThe lender pays your builder at set stages, such as base, frame, lock-up, fixing and completion, usually after an invoice or inspection.
Usually interest-only on the amount drawn. Repayments rise as each stage is paid, then switch to principal and interest at completion.
Yes. In Queensland, eligible first home buyers building a new home valued under $750,000 may receive $30,000.
Some lenders allow it, usually with a 30–40% deposit, detailed plans and stronger documents. Most prefer a licensed builder.
Yes. Full-doc lenders use tax returns; low-doc lenders may accept BAS or an accountant’s declaration.
Yes. We structure finance to cover demolition and the new build, often using equity in your existing land.
LET’S MAKE YOUR BUILD HAPPEN
Whether you’re starting from scratch or mid-way through planning, we’ll help with the right loan and hands-on support at every stage.
Construction lenders compared
Grants and duty relief checked
Progress payments coordinated
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, 9 am–5 pm
YOUR FREE BUILD CHAT
Land, builder and timeline, wherever you’re at.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form