Sole traders
Tradies, consultants and small operators earning through their own ABN.
FOR BUSINESS OWNERS
Your income doesn’t fit a payslip.
Your loan doesn’t have to.
Lenders built around PAYG income can struggle with irregular earnings, add-backs and company or trust structures. We know which lenders look at business owners differently, and how to present your financials, with full-doc and alt-doc options compared across our panel. Personal guidance from Ausfirst Lending Group in Caloundra, Brisbane and across Queensland.
Excellent · 35 Google reviews
WHO WE HELP
Being self-employed means your finances rarely look the same two years running. We help lenders see a viable business and a reliable income, whatever your structure.
Tradies, consultants and small operators earning through their own ABN.
Directors and beneficiaries with income flowing through business structures.
Variable or project-based income that doesn’t fit a standard assessment.
Been told no by your bank? One lender’s policy isn’t the whole market. Different lenders assess business income very differently.
Start with a free chatPROVING YOUR INCOME
The right lender and documentation path depend on how long you’ve traded and how up to date your tax returns are.
Tax returns and ATO notices of assessment, usually for the last two years. Often the sharpest rates.
BAS, business bank statements or an accountant’s letter when returns aren’t current.
Depreciation, extra super and one-off costs can often be added back to your income.
Some lenders consider one year of trading, especially in the same industry.
A QUICK COMPARISON
| What lenders look at | PAYG | Self-employed |
|---|---|---|
| Income proof | Payslips | Tax returns, financials, BAS |
| History | Current job | Often 2 years, sometimes 1 |
| Rates | Standard | Similar full-doc; higher alt-doc |
| Approval | Usually quicker | Often more checks |
LMI depends on your LVR, not how you’re paid. Lender policies vary.
Compare my optionsKNOW YOUR NUMBERS
Many lenders average your last two years. If income has risen, some use the more recent year. If it has fallen, most use the lower figure.
Add-backs can lift the figure, so we work through your financials with you and your accountant.
Illustration only, not a borrowing assessment. Add-backs accepted and averaging rules vary by lender. Company and trust income is assessed differently. Confirm figures with your accountant.
Check my actual optionsPLAN AHEAD
Minimising taxable income lowers your tax, but it also lowers what lenders see. If you’re planning to buy, talk to us and your accountant before you lodge.
Lenders want to see consistent income, manageable business debts and a business that’s still trading strongly. Up-to-date BAS and financials make that easier.
Personal and business debts are both assessed, including partnerships, equipment finance and ATO payment plans.
Lenders may use your wage, director’s fees, trust distributions and retained company profits. We present the full picture.
Alt-doc loans rely on BAS or an accountant’s letter. They often carry higher rates and lower maximum LVRs, and may need LMI.
Lender policies on add-backs, trading history and alt-doc lending vary and can change.
Let’s check what lenders will see. We’ll review your financials and match lenders to how your business earns.
Check my next stepsDOCUMENTS TO PREPARE
Exact requirements depend on the lender and documentation path.
Personal and business tax returns and notices of assessment, often two years.
Profit and loss statements and balance sheets.
Recent BAS and business bank statements, especially for alt-doc.
Proof of how long you’ve traded and been GST-registered.
YOUR LOAN OPTIONS
The right features can smooth out lumpy income and keep your money working.
Standard rates when your returns are current.
Options when returns are behind or income has grown.
Park tax provisions and income to reduce interest.
Balance steady repayments with flexibility.
A self-employed tradie? See loan options built around contractor income.
Explore tradie home loansFROM FIRST CHAT TO SETTLEMENT
Richard personally oversees self-employed applications, so you’re not passed between departments.
UNDERSTAND
By phone, Zoom or in person. Your structure, income and goals.
GATHER
Tax returns, financials and BAS, with your accountant if needed.
ANALYSE & PLAN
Full-doc or alt-doc, and the lenders whose policies fit your income.
APPLY
We present your business clearly so the lender sees the full picture.
FINALISE
We manage settlement and keep you informed.
SUPPORT
As your financials improve, we review your rate and options.
WHAT MAKES AUSFIRST DIFFERENT
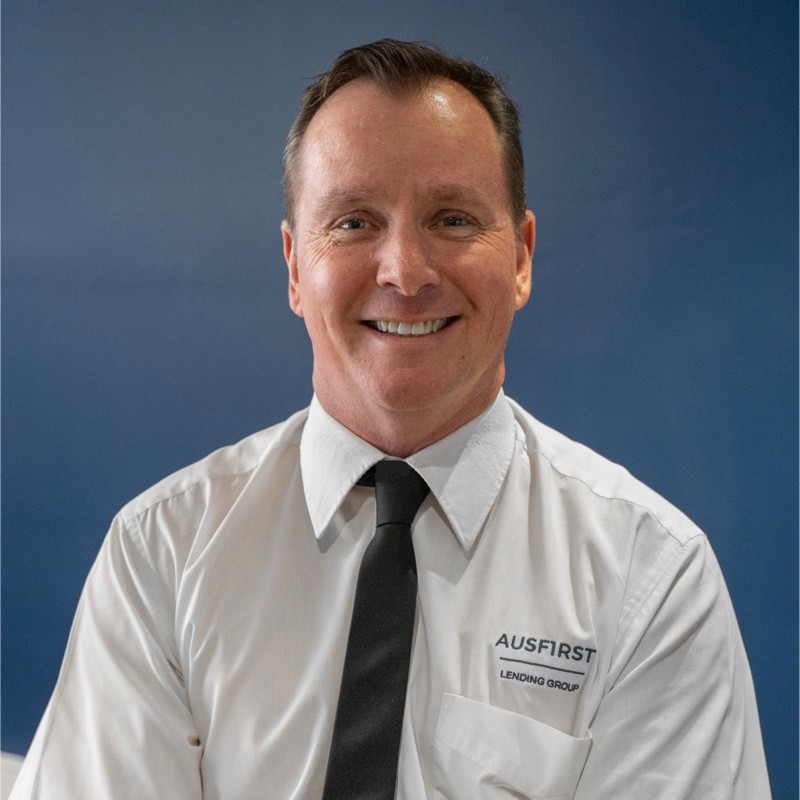
You’re looked after by someone who treats your financial success as his own.
When you choose Ausfirst, you deal directly with Richard, the founder, who brings over 30 years of hands-on lending experience across Queensland.
He understands that being self-employed means your finances don’t always fit a standard bank box. Whether you need an alt-doc loan, have complex tax structures or want to maximise your borrowing power, you get tailored advice and a smooth application.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Thanks to Richard and Debbie and the team at Ausfirst Lending… They are the gurus of self employed loans. I highly recommend their services.”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions business owners ask most. Every business is different, so we’re happy to talk through the detail.
Ask about my situationMost lenders want two years of trading, but some consider one year, particularly if you worked in the same industry before.
Possibly. Some lenders accept one year of financials, sometimes with extra documents like BAS or an accountant’s letter.
A loan that verifies income with BAS, bank statements or an accountant’s declaration instead of full tax returns. Rates are usually higher and LVRs lower.
Not necessarily. With full documentation, self-employed borrowers can access the same rates as PAYG borrowers. Alt-doc loans usually cost more.
Non-cash or one-off expenses, like depreciation, extra super contributions or interest on loans being refinanced, that lenders may add back to your income.
Yes, ideally. Your accountant can confirm add-backs and help time lodgements, and some lenders need an accountant’s letter.
GET STARTED TODAY
Tell us about your business and what you’d like to buy. We’ll look at your financials and the lenders that suit how you earn.
Full-doc and alt-doc options compared
Add-backs and structures worked through
Direct access to Richard
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, 9 am–5 pm
YOUR FREE CHAT
Send our team a little about your plans.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form