Trade income, understood
ABN income, add-backs and BAS, read the way lenders assess them.
SELF-EMPLOYED LENDING
Buy a home sooner.
Even when the bank says no.
Self-employed lending is our specialty. Whether you run your own ABN, subcontract or have just gone out on your own, we help tradies buy and refinance when a bank’s standard assessment doesn’t fit trade income. We know which of our 40+ lenders lend comfortably to trade businesses. Personal guidance from Ausfirst Lending Group in Caloundra.
Excellent · 35 Google reviewsWHY GOOD EARNERS GET KNOCKED BACK
Most tradies who get declined can comfortably afford the loan. Trade income doesn’t arrive as a tidy fortnightly payslip, so automated assessments read a strong business as “inconsistent”. We present net profit, add-backs and BAS the way lenders assess them, to lenders that understand a trade business.
ABN income, add-backs and BAS, read the way lenders assess them.
We know which say yes to self-employed and trade income.
The same person from the first chat through to settlement.
The bank already said no? One bank’s decline is one bank’s policy. A different lender and a better-presented file often gets a yes.
Start with a free chatHOW LENDERS ASSESS TRADE INCOME
Two builders on the same income can get different answers, depending on how it’s documented.
Two years of returns and NOAs, with add-backs for depreciation, one-offs, extra super and interest.
BAS plus an accountant’s declaration, usually with an ABN and GST history.
A handful of lenders use your stronger latest year instead of averaging two.
PAYG is assessed like any wage. Mixed PAYG and ABN income can count together.
HOW YOU’RE PAID
| What changes | PAYG | ABN full-doc | Low-doc |
|---|---|---|---|
| Income proof | Payslips | Returns and NOAs | BAS, accountant |
| History | Current job | Often 2 years | Shorter, with ABN/GST |
| Rates | Standard | Standard | Often higher |
Lender policies on trading history and low-doc lending vary and can change.
Check my optionsMY TAX RETURN LOOKS LOW
You’ve claimed hard, so paper income looks small. Add-backs often lift assessable income substantially without changing your tax.
Many lenders average two years; some use a stronger latest year.
Illustration only, not a borrowing assessment. Add-backs accepted and averaging rules vary by lender. Company and trust income is assessed differently. Confirm figures with your accountant.
Check my actual optionsTRADIE SITUATIONS WE SORT OUT
If one of these sounds like you, there’s usually a lender that fits.
We look at low-doc options and lenders that accept a shorter trading history.
Some lenders consider one year, especially if you worked in the same trade before.
We match you to lenders comfortable with variable trade income, not ones that want a flat wage.
LMI, a family guarantee or a first home scheme can bring the purchase forward.
See low deposit loansLow-doc loans can carry a higher rate or LMI. We show the full cost so it’s a considered choice.
Let’s read your income the way a lender will. Before you assume the bank’s “no” is final.
Check my next stepsWHAT YOU’LL NEED TO QUALIFY
Variable income invites closer questions. Clean statements and up-to-date returns make them a formality.
Returns and NOAs, or BAS and an accountant’s declaration.
Often held for a set period, GST-registered where it applies.
Past issues change which lenders will consider you.
Savings, equity, a family guarantee or a first home scheme.
WHEN YOU NEED MORE THAN A HOME LOAN
We structure your home loan with the whole picture in mind, leaving room for the next ute or tool purchase.
Bridge unpaid invoices and keep the business moving.
Fund tools, machinery and plant without tying up cash.
A structure that suits a trade business.
Home, business, cash flow and assets under one broker.
Want the broader guide to buying on business income?
Explore self-employed loansHOW WE WORK
We work around site hours, by phone, Zoom or in person.
CONVERSATION
Your business, income and what you’d like to buy.
FINANCIALS
Returns, BAS and add-backs, with your accountant if needed.
STRATEGY
Full-doc or low-doc, and lenders that suit trade income.
APPLICATION
A well-presented file the lender can say yes to.
SETTLEMENT
We coordinate settlement and keep you informed.
AND BEYOND
As your financials improve, we review your rate.
WHY TRADIES WORK WITH AUSFIRST
You’re looked after by someone who treats your financial success as his own.
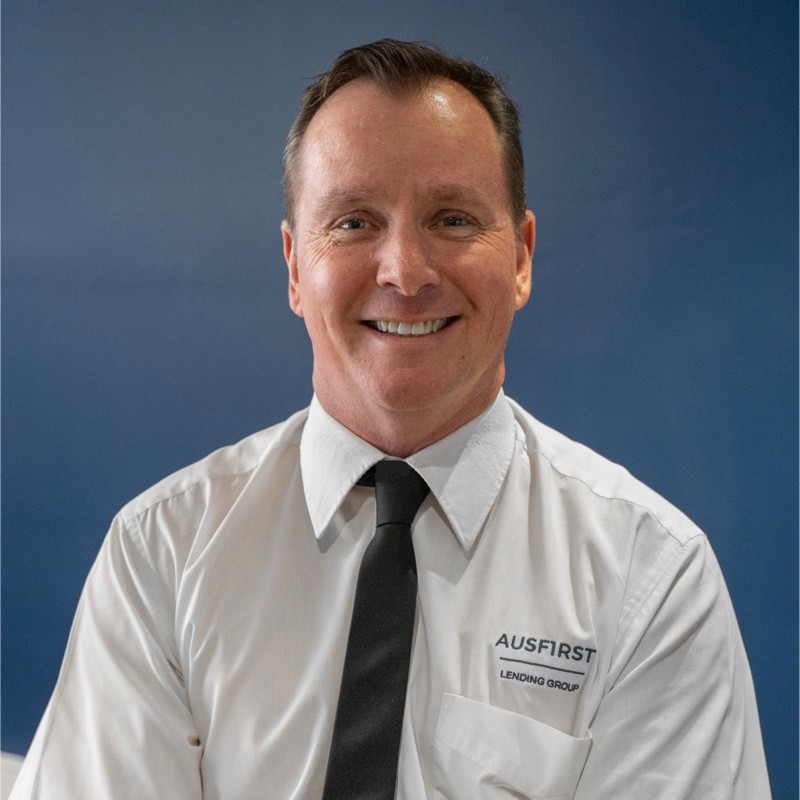
You work directly with Richard Luke, our director, with more than 30 years in Queensland lending. Not a call centre, and not a different voice each time.
Add-backs, BAS, NOAs, ABN age and low-doc policy: we handle these every week and know which lender says yes to which file.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Thanks to Richard and Debbie and the team at Ausfirst Lending… They are the gurus of self employed loans. I highly recommend their services.”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions tradies ask us most. Every business is different, so we’re happy to talk through the detail.
Ask a questionYes. Lenders usually want two years of returns and NOAs, or a low-doc option for newer ABNs. The key is presenting your income the way lenders read it.
Two years is the common benchmark. Some lenders consider one year, and a few look at shorter histories on a low-doc basis.
Because you’ve claimed legitimate deductions. Lenders add back depreciation, one-off purchases, extra super and interest, so assessable income is often higher.
Yes. PAYG apprentices are assessed like any wage earner. ABN income is self-employed income, and the right lender can count a mix of both.
No. A decline usually reflects one lender’s policy, not your ability to repay. A different lender and a better-presented file often gets a yes.
GET A STRAIGHT ANSWER
Before you assume the bank’s “no” is the final word, let’s look at your income the way a lender will.
Add-backs and BAS worked through
Lenders that lend to trade businesses
Direct access to Richard
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, and by appointment
YOUR FREE CHAT
Your ABN, how long you’ve traded and what you’d like to buy.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form