Know what you can afford
We review your income, expenses, existing debts and deposit to help you understand your borrowing capacity and a budget you can live with.
YOUR FIRST HOME STARTS HERE
Big first step.
A clear plan to get you there.
You bring the homeownership dream. We help you work out your budget, compare suitable loans and make sense of deposits and grants. Get personal guidance from Ausfirst Lending Group’s mortgage brokers in Brisbane and on the Sunshine Coast.
Excellent · 35 Google reviews
WHERE DO I START?
A short intro to how we turn the big questions into clear next steps.
From working out a budget you can live with to comparing suitable loans, deposits and grants, we explain each stage in plain language, so you always know what’s coming next.
Still saving, or ready to make an offer? Either way, there’s a useful step to take now.
FIRST HOME BUYER LOANS, MADE CLEARER
Buying your first home is exciting. The finance should feel manageable, too. As your mortgage broker for first home buyers, we turn the big questions into practical next steps, whether you’re still saving or ready to make an offer.
We review your income, expenses, existing debts and deposit to help you understand your borrowing capacity and a budget you can live with.
We compare suitable options from our lender panel, looking at interest rates, fees, loan features and lender policies alongside your goals.
From checking paperwork to liaising with your lender, we keep your application moving and explain what happens next. You have someone to call.
Not quite ready to buy? That’s a good time to talk. We can help you understand what to work on before you apply.
Start with a free chatA LOAN CHOSEN AROUND YOU
Your first mortgage deserves more than a rate comparison. It needs a clear look at your circumstances, your options and the way you want to live.
Mortgage brokers providing regulated credit assistance must act in your best interests. We consider the overall suitability of a loan, including costs, features and your needs.
Every lender assesses borrowers differently. We compare options from our panel and explain which lenders may suit your income, deposit and property plans.
We help you weigh rates, fees, repayment flexibility and offset options. We can also ask lenders about available pricing and fee concessions; outcomes depend on the lender.
We help prepare your application, check supporting documents and liaise with the lender. We also explain relevant grants and scheme requirements and support you after settlement.
A QUICK COMPARISON
| What you compare | One bank | Ausfirst |
|---|---|---|
| Loan choice | That bank’s products | Our lender panel |
| Lending criteria | One lender’s policies | Multiple lender policies |
| Your application | Apply with that bank | We help manage it |
| Loan fit | Options within its range | Options matched to your needs |
Our panel does not include every lender or every loan in the market. A bank can also provide application support.
Find my first home optionsLET’S TALK ABOUT YOUR DEPOSIT
You don’t always need a 20% deposit to buy your first home. Depending on your circumstances, low deposit loans, government support or a family guarantee may offer another path.
We help you compare what those options mean for your repayments, costs and responsibilities. A smaller deposit usually means a larger loan, so the right starting point is a budget that works for you.
Illustration only, not a borrowing assessment. Excludes duty, legal costs, fees and LMI. A 5% deposit option depends on lender approval, scheme eligibility and location price caps.
Check my actual optionsMAKE THE MOST OF AVAILABLE SUPPORT
A grant, a government guarantee and a stamp duty concession do different things. We help you understand which support may apply to your purchase and what you need to check before you commit.

Eligible first home buyers can buy with a minimum 5% deposit through a participating lender, without LMI. Since 1 October 2025, the scheme has no income caps or limit on places. Location price caps, owner-occupier requirements and lender approval still apply.
Eligible single parents and legal guardians may have a minimum 2% deposit option. The guarantee supports the lender; it does not pay your deposit or repayments.
Check the official scheme detailsFor eligible Queensland contracts signed on or after 20 November 2023, the grant is $30,000. The new home and land must be valued below $750,000. It is not available for an established home.
Your ownership history, residency and other conditions matter. Your broker can help you understand the documents and application pathway.
Queensland grant eligibilityEligible first buyers of new homes under contracts dated 1 May 2025 or later may receive a full transfer duty concession, with no home value cap for the qualifying residence.
For eligible established homes, no duty is payable up to $700,000; a reduced concession applies above $700,000 and below $800,000. Residency and other rules apply, including citizenship conditions for transactions from 1 August 2026.
The NSW First Home Owner (New Homes) Grant may be available when you buy or build your first new home. The purchase price limit is $600,000 for an eligible newly built or substantially renovated home.
For land and a building contract, the combined value limit is $750,000. The grant does not apply to established homes. Other eligibility and residence conditions must be met.
NSW grant eligibilityEligible NSW buyers may receive a full transfer duty exemption on new or existing homes valued up to $800,000, and a concessional rate above $800,000 and below $1 million.
For qualifying vacant land, the exemption threshold is $350,000, with concessions above that amount and below $450,000. Residence and ownership conditions apply. The former First Home Buyer Choice scheme is closed to new applicants.
NSW assistance scheme detailsScheme information checked 5 October 2026. Your eligibility depends on the scheme, property, contract date and personal circumstances. Confirm current rules with the relevant authority before applying.
Let’s check what applies to you. We’ll explain the support options alongside your loan, deposit and buying costs.
Check my next stepsBEFORE YOU APPLY
A lender’s loan criteria and a government scheme’s rules are separate checks. We look at both, so you understand your starting position.
Lenders assess your ability to repay, including your income, living expenses, credit history, existing commitments and available deposit. Different lenders may treat your circumstances differently.
Most first home buyer programs require applicants to be at least 18. Citizenship or permanent residency requirements vary by benefit. We help identify the requirements relevant to your application.
Grants and concessions have their own ownership rules, including rules about partners. The federal 5% scheme can also include people who have not owned property or land in Australia for 10 years.
Property price caps, new versus established home rules and residence obligations differ across programs. Owner-occupier support is not for buying an investment property. We explain which conditions apply.
THE RIGHT STRUCTURE MATTERS
A competitive rate matters, but so do fees and flexibility. We help you compare loan features against your budget, saving habits and plans for the years ahead.
A rate fixed for an agreed period can make repayments easier to plan. We’ll explain limits on extra repayments and possible break costs if your plans change.
Your rate and repayments can change. Depending on the product, you may have access to extra repayments, redraw or an offset account.
You may be able to divide your loan into fixed and variable portions. We help you compare the costs and features of each part.
A linked offset account can reduce the loan balance used to calculate interest. We check whether the benefit suits your savings balance and any added fees.
Building, buying off the plan or purchasing with someone else? We’ll talk through the extra lending and timing considerations.
Talk about my property plansFROM FIRST CHAT TO FIRST KEYS
You don’t need to know the whole process before you start. We explain each stage, prepare the application with you and keep you informed as your first home purchase progresses.
UNDERSTAND
Meet by phone, Zoom or in person. Tell us where you want to buy, your timeline and what matters to you. Buying with a partner, friend or family member? Discuss ownership and responsibilities with your solicitor early.
GATHER
We help gather identification, income documents, savings and debt details. We review your deposit, expenses and credit position, then discuss borrowing capacity and upfront costs, including legal fees, duty and any LMI.
ANALYSE & PLAN
We compare suitable lenders, rates and features, check relevant grants and scheme pathways and discuss conditional pre-approval. You can then focus your property search on a clearer budget. Pre-approval is not final approval.
APPLY
When you’ve found a home, we help finalise the application and liaise with the lender about valuation and approval requirements. New builds and off-the-plan purchases have extra timing considerations. Seek legal advice before signing or bidding.
FINALISE
We help coordinate the finance with your lender and conveyancer or solicitor. They handle the legal transfer; we keep you informed about your loan documents, outstanding requirements and the finance side of settlement.
SUPPORT
Once settlement is complete, it’s time to enjoy your new home. We remain available to explain your loan, review it as your circumstances change and discuss future refinancing when appropriate.
WHAT MAKES AUSFIRST DIFFERENT
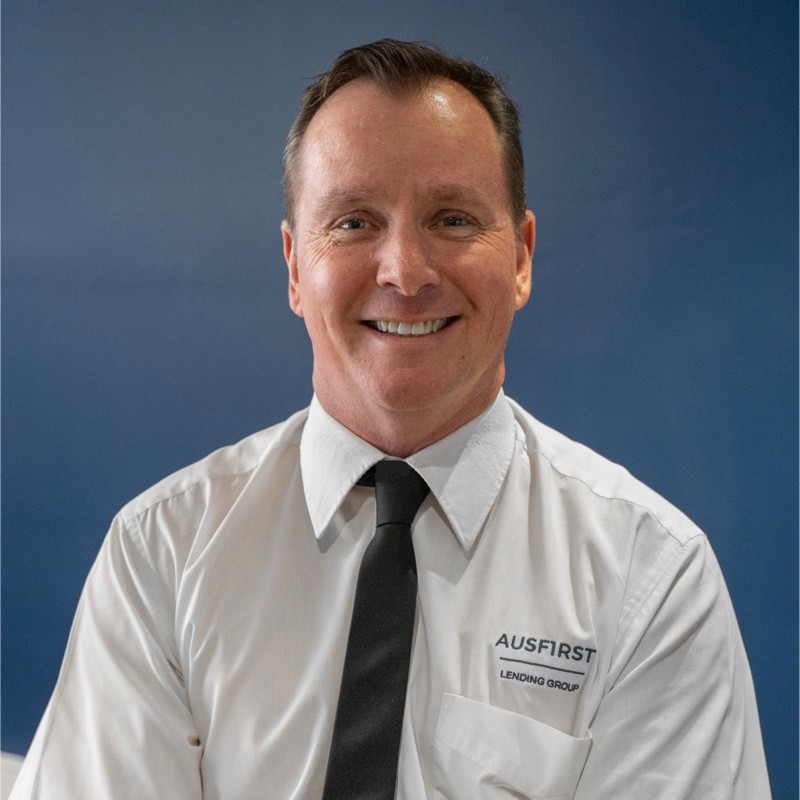
You’re looked after by someone who treats your financial success as his own.
Richard brings more than 30 years of hands-on broking experience to Ausfirst Lending Group. He personally oversees clients’ lending journeys, supported by the team, with a focus on clear advice, careful loan structuring and the bigger picture.
For first home buyers, that means taking the time to explain the options, answer your questions and help you make an informed decision. You have a team who understands your circumstances and stays involved through the process.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Debbie made the process of buying a new house frictionless, by providing excellent support throughout”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
Here are the questions we’re often asked as mortgage brokers for first home buyers. Your circumstances matter, so we’re happy to talk through the details with you.
Ask us about my situationThe amount depends on the lender, property and your eligibility for support. Eligible buyers may use the Australian Government 5% Deposit Scheme; other low deposit or family guarantee options may also be worth exploring. You still need to allow for buying costs and show that the loan repayments are affordable. We help you compare the full picture.
A deposit of 20% of the lender’s assessed property value generally avoids LMI on a standard home loan. Eligible government guarantees, some profession-based waivers and suitable guarantor arrangements may provide alternatives. LMI protects the lender, rather than you, if you cannot repay. We explain whether it applies and how it affects your loan costs.
We assess your financial position, compare suitable loans from our panel, explain deposit and support options and help prepare your application. We liaise with your lender through approval and settlement, and remain available afterwards. That guidance can help you avoid application mistakes and understand lender criteria, but it does not guarantee approval.
Ausfirst’s home loan broker service is free for clients. Participating lenders pay us a commission. We explain that remuneration as part of our disclosure process. Lender fees, legal costs, valuation costs and any LMI are separate, so we help you understand the costs associated with the loan and property purchase.
We help you compare suitable options from our panel and understand why a loan may fit your needs. That includes interest rates, fees, features, eligibility and repayment flexibility. There is no single loan that is best for everyone, and our panel does not include every product on the market. The recommendation depends on your circumstances and goals.
Some eligible buyers can receive a full concession; others may receive a reduction or pay duty. The result depends on the home type, value, contract date and eligibility. New and established homes have different concession rules. See the Queensland summary above and confirm your position with Queensland Revenue Office or your conveyancer before committing.
The First Home Super Saver scheme can allow eligible buyers to release certain voluntary super contributions, plus associated earnings calculated by the ATO. Contribution limits apply: up to $15,000 in a financial year and $50,000 in total may count. It does not let you withdraw your ordinary compulsory employer contributions to buy a home. Check the ATO’s release and timing rules.
Read the official super saver scheme guidanceYour partner’s ownership history can affect your eligibility for a grant, concession or guarantee. The rules differ between programs, so owning a property previously does not produce the same answer for every type of assistance. Tell us when, where and how the property was owned and occupied, and we can help identify what needs to be checked.
Potentially, but it depends on the nature of any credit issues, your income evidence, deposit and the lender’s policy. We review your circumstances before discussing suitable pathways. If you’re self-employed, we help you understand the documents a lender may require. Approval cannot be promised, and it may be better to improve your position before applying.
State grants generally support eligible buyers of new homes, while duty concessions and the federal 5% scheme have their own rules. Queensland and NSW offer different benefits. Your age, residency, ownership history, property, contract date and occupancy plans can all matter. Use the grants section above as a starting point, then check your individual eligibility.
We help you understand the application route and supporting documents. State grants may be lodged through an approved lender or directly with the relevant revenue authority, depending on timing. The federal 5% Deposit Scheme is accessed through a participating lender, not a direct application to Housing Australia. Your conveyancer can assist with duty concession requirements.
No. Pre-approval is conditional and subject to the lender’s requirements, the property and a final assessment. It helps guide your budget, but changes to your finances, valuation or property choice may affect final approval. Speak with your broker and solicitor before making an unconditional offer or bidding at auction.
LET’S MAKE A START
You don’t need a perfect plan or a property picked out. Tell us where you’re at, and we’ll help you understand your first home loan options and what to do next.
A clear look at your borrowing position
Deposit, grant and lender options explained
Personal guidance from an experienced team
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, 9 am–5 pm
YOUR FREE FIRST HOME CHAT
Send our team a little about your plans.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form