Buy sooner
Purchase with a 10–15% deposit instead of waiting years to save 20%.
KEEP MORE OF YOUR DEPOSIT
Buy with a smaller deposit.
Skip the insurance premium.
Lenders mortgage insurance can add tens of thousands to your purchase. If you work in an eligible profession, some lenders waive it on loans up to 85–90% of the property value. We find the lenders whose policies fit you. Personal guidance from Ausfirst Lending Group’s mortgage brokers in Brisbane and on the Sunshine Coast.
Excellent · 35 Google reviews
WHAT IS AN LMI WAIVED LOAN?
LMI usually applies when your deposit is under 20%. It protects the lender if you default, but you pay for it. Some lenders waive it for professions they see as lower risk because of stable income and job security.
Purchase with a 10–15% deposit instead of waiting years to save 20%.
Put the money you’d spend on LMI towards your buffer, furniture or a fit-out.
Eligible professionals may borrow 85–90% of the property value without LMI, depending on the lender.
Not sure if your profession qualifies? Lender lists differ. We’ll check which policies apply to you.
Start with a free chatWHO MAY BE ELIGIBLE
Each lender keeps its own list of eligible professions, minimum incomes and registration requirements. These are the groups most commonly included.
Doctors, specialists, dentists and other registered health professionals are the most widely accepted group.
Members of recognised professional bodies, often with a minimum income, may qualify with some lenders.
Some lenders extend waivers to engineers, actuaries and other listed professions that meet their criteria.
Not in a listed profession? The Australian Government 5% Deposit Scheme lets eligible buyers avoid LMI.
A QUICK COMPARISON
| At 90% of the value | Standard loan | LMI waiver |
|---|---|---|
| Deposit | 10% | 10% |
| LMI | Usually payable | Waived |
| Who qualifies | Most borrowers | Eligible professions |
| Lender choice | Wide | Fewer lenders |
Waiver policies, eligible professions and LVR limits vary by lender and can change. Standard lending criteria still apply.
Check if I’m eligibleKNOW YOUR LVR
Your loan-to-value ratio (LVR) is the loan as a percentage of the property value. Above 80%, LMI usually applies, unless you qualify for a waiver or scheme.
We check your LVR against each lender’s waiver limits and your profession’s requirements.
Illustration only. Excludes buying costs such as duty and legal fees. LVR is based on the lender’s valuation, which may differ from the price. Waiver eligibility depends on the lender and your profession.
Check my actual optionsWHICH LENDERS OFFER WAIVERS?
Several major and smaller lenders offer LMI waivers, but each sets its own eligible professions, income thresholds and LVR limits. Matching you to the right one is where we help.
Lenders may require current registration or professional membership, a minimum income, and a loan size or LVR cap. Some limit waivers to owner-occupied purchases.
We compare these rules across our panel, so your application goes to a lender whose policy fits.
An early-career doctor buying a $900,000 first home with a 10% deposit. LMI at that LVR can cost upwards of $20,000.
With a waiver, she put those savings towards her new home’s fit-out instead.
A couple of school teachers buying a $700,000 home with a 15% deposit. LMI would normally have cost around $9,000.
A lender policy recognising educators’ income stability meant no LMI was charged.
LMI figures are estimates and vary with the lender, loan size and LVR. Outcomes depend on your circumstances and lender approval.
Let’s see what you could save. We’ll compare waiver lenders and show the LMI you could avoid.
Check my next stepsBEFORE YOU APPLY
A waiver removes the insurance, not the lending criteria. Lenders still assess you as they would any borrower.
Your occupation must be on the lender’s list, often with current registration or membership.
Many lenders set an income threshold, which can differ by profession.
Waivers usually cap at 85% or 90% LVR, with some limiting the loan size.
Lenders still check your expenses, debts and credit history.
OTHER WAYS TO AVOID LMI
If your profession isn’t on a lender’s list, other options may still help you reduce or avoid LMI.
Eligible first home buyers can buy with 5% down and no LMI through a participating lender.
A family member’s property equity can secure part of the loan and help you avoid LMI.
A 20% deposit generally avoids LMI on a standard loan.
Some lenders let you add LMI to your loan, though you pay interest on it.
Buying an investment property or self-employed? Waiver rules can differ, so we’ll check what applies.
Talk about my situationFROM FIRST CHAT TO FIRST KEYS
We verify your eligibility, match you to the right lender and keep you informed through to settlement.
UNDERSTAND
Meet by phone, Zoom or in person. Tell us about your profession, deposit and property goals.
GATHER
We collect proof of registration or membership, income documents and savings details.
ANALYSE & PLAN
We compare lender lists, income thresholds, LVR limits and rates across our panel.
APPLY
We prepare your application so the waiver is correctly applied and liaise with the lender.
FINALISE
We coordinate with your lender and conveyancer and keep you informed through to settlement.
SUPPORT
We review your loan as your income and plans change.
WHAT MAKES AUSFIRST DIFFERENT
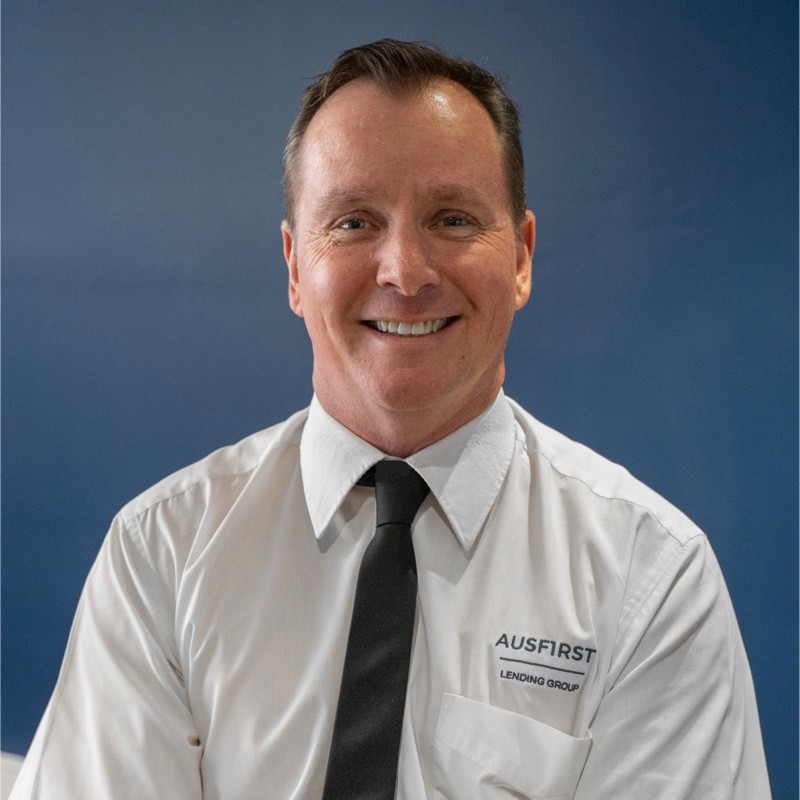
You’re looked after by someone who treats your financial success as his own.
Richard brings more than 30 years of hands-on broking experience. He knows which lenders recognise which professions, and how to structure an application so the waiver applies.
We verify your professional standing, check lender thresholds and compare rates, so you keep more of your deposit and buy sooner.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Debbie made the process of buying a new house frictionless, by providing excellent support throughout”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions we’re asked most about LMI waivers and eligibility. Your circumstances matter, so we’re happy to talk through the detail.
Ask about my eligibilityMost commonly doctors, specialists, dentists and other registered health professionals. Some lenders also include accountants, lawyers, engineers and other listed professions. Each lender sets its own list and requirements.
Several major banks and smaller lenders offer waivers, and their policies change regularly. We compare current policies across our panel to find lenders that suit your profession.
The Australian Government 5% Deposit Scheme lets eligible first home buyers purchase with a 5% deposit and no LMI through a participating lender. A family guarantee may also help.
Not automatically. First home buyers usually pay LMI with less than 20% deposit, unless they use the 5% Deposit Scheme, a family guarantee or qualify for a professional waiver.
There’s no Queensland-specific exemption. The same options apply as elsewhere: professional waivers, the federal 5% Deposit Scheme, a family guarantee or a 20% deposit.
A loan for 90% of the property value, with a 10% deposit, where the lender waives LMI. It’s typically offered to eligible professionals.
Anyone with a 20% deposit generally avoids it. Below that, you’ll need a waiver, a government scheme or a guarantor.
It’s usually required when you borrow more than 80% of the property value, unless a waiver, scheme or guarantee applies.
LET’S MAKE A START
Tell us your profession and plans. We’ll check which lenders could waive LMI for you and what you could save.
Your profession checked against lender lists
LMI savings and alternatives compared
Personal guidance from an experienced team
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, 9 am–5 pm
YOUR FREE LMI WAIVER CHECK
Send our team a little about your plans.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form