Understand the fund
We review the fund’s income, contributions, existing commitments and cash available for the deposit, transaction costs and ongoing liquidity.
COMMERCIAL SMSF LENDING
Finance for business premises starts
with the right structure.
Looking to acquire an office, warehouse, industrial unit or retail shop through your self-managed super fund? Ausfirst Lending Group helps trustees compare commercial SMSF loan options, understand lender requirements and manage the application through to settlement.
Whether the premises will be leased to your operating business or an unrelated commercial tenant, we assess the fund, property, lease and borrowing proposal together. Caloundra-based support for commercial SMSF lending across Queensland.
HOW IT COMES TOGETHER
A short overview of how a commercial SMSF loan comes together.
We assess the fund, the premises and the lease together, compare the panel lenders that offer commercial SMSF finance, and explain the documents each one needs.
Your accountant, solicitor and SMSF administrator confirm the compliance side; we handle the finance and keep everyone aligned through to settlement.
COMMERCIAL SMSF LENDING ACROSS QUEENSLAND
Commercial SMSF borrowing brings together lender policy, property use, lease arrangements and the fund’s financial position. We assess the finance, compare relevant lenders and explain the documentation needed. Your professional advisers confirm the SMSF’s investment strategy, business real property status, tax treatment and legal structure.
We review the fund’s income, contributions, existing commitments and cash available for the deposit, transaction costs and ongoing liquidity.
We consider the property’s type, location, valuation, business use and tenancy arrangements against lender requirements.
We identify lenders whose policies may suit the property, proposed LVR, rental income and fund position.
Buying business premises outside super? Explore our commercial property loan options.
Explore commercial property loansHOW A COMMERCIAL SMSF LOAN WORKS
A limited recourse borrowing arrangement, or LRBA, allows an SMSF to borrow to acquire an eligible asset, subject to strict superannuation rules. For a commercial property purchase, the borrowing structure and ownership documents need to be established correctly before the transaction proceeds.
The commercial property is held in a separate holding trust while the SMSF holds the beneficial interest. Properties involving multiple titles require specific legal assessment.
The lender’s recourse against the SMSF under a compliant LRBA is restricted to the acquired asset. Any personal guarantees require separate consideration.
The fund needs to cover its contribution to the purchase and transaction costs, while retaining sufficient liquid assets after settlement.
Commercial rent, eligible contributions and other accepted fund income may support repayments, depending on lender policy.
BUSINESS REAL PROPERTY AND THE AUGUST 2026 CHANGES
Schedule 5 of the Treasury Laws Amendment (Tax Reform No. 1) Act 2026 amended section 67A of the Superannuation Industry (Supervision) Act 1993. From 10 August 2026, affected new LRBAs involving real property must satisfy the business real property requirement in section 66. Specified earlier arrangements and qualifying refinancing remain protected under the transitional provisions.
CURRENT BORROWING RULES
| Commercial SMSF proposal | What the changes mean |
|---|---|
| New commercial property LRBA | The property must satisfy the business real property requirement, alongside the other LRBA conditions. |
| Maintaining or refinancing a borrowing under a pre-commencement arrangement | The new requirement does not apply to the extent covered by the statutory transition. |
| Acquisition under an arrangement entered into before commencement | Transitional protection may apply even where settlement occurs later. |
Your solicitor and SMSF advisers should confirm which provisions apply to your transaction.
Check my commercial SMSF proposalBusiness real property generally requires the relevant land or buildings to be used wholly and exclusively in one or more businesses. An office, warehouse or shop does not automatically qualify simply because it is marketed as commercial property.
For affected LRBAs, the ATO states that the property must qualify when the arrangement begins and remain business real property throughout its life. Vacant premises, mixed use or a proposed change of use need careful assessment.
BUYING PREMISES FOR YOUR BUSINESS
An SMSF may acquire eligible business premises and lease them to a related operating business, subject to the business real property rules and other SMSF requirements.
An office occupied by a professional practice, a warehouse used by a distribution business, or a retail shop occupied by the members’ trading business.
The arrangement must be conducted on an arm’s-length basis, with market rent and commercial lease terms. Your advisers should document the lease and confirm compliance before proceeding.
We assess the lease, rental evidence, commercial valuation and the fund’s ability to meet repayments. The lender may also require financial information about the tenant business.
A QUICK COMMERCIAL SMSF CHECK
We can review lender appetite while your advisers confirm business real property status and any transitional treatment.
Under ATO guidance, a binding acquisition contract exchanged before 10 August 2026 may qualify for protection even if settlement or the LRBA occurs later. Significant contract changes need separate assessment.
This check is a starting point. It does not determine legal eligibility or loan approval.
Check my actual lending optionsCOMPARING COMMERCIAL SMSF LOANS
There is no single deposit, fund balance or liquidity figure that suits every commercial SMSF application.
Only some panel lenders offer commercial SMSF finance. We identify relevant options and compare their requirements against your proposed transaction. Lenders may differ on:
Commercial SMSF product limits can also vary with the security and loan amount.
A rate only becomes useful when the lender accepts the premises, recognises enough income and offers a workable loan structure.
An early assessment can identify a deposit shortfall, an unacceptable lease or a liquidity requirement before the purchase advances.
See which lenders fit your proposal. We compare relevant commercial SMSF policies against your fund, premises and lease.
Compare my commercial SMSF loan optionsCOMMERCIAL LVR, DEPOSIT AND LIQUIDITY
The loan-to-value ratio measures the loan against the property value accepted by the lender. Commercial SMSF LVR ceilings are lender-specific and may depend on the premises, loan size and security assessment.
Allow for transfer duty, commercial valuation, lender fees, legal work and holding-trust documentation. Your accountant and solicitor should also confirm any GST implications.
The deposit is only one part of the funding requirement. The fund must be able to meet loan repayments, property expenses and its other obligations after settlement. We check any lender liquidity requirement alongside the fund’s available cash and accepted liquid assets.
AN ILLUSTRATION
| Lender’s accepted valuation | $1,000,000 |
|---|---|
| Loan at 70% LVR | $700,000 |
| Fund contribution | $300,000 |
| Also required | Transaction costs and any required liquidity |
This is an illustration, not a loan offer or universal lending limit.
Review my deposit and liquidity positionCOMMERCIAL RENTAL YIELDS AND SERVICING
A commercial property’s rental yield is a useful starting point, but it does not establish whether the SMSF can afford the loan.
Compares annual rent with the property’s price or value.
Also accounts for property expenses borne by the owner.
We review the lease, rental evidence, outgoings and lender treatment of income. A lender may accept only part of the rent when assessing repayments.
Vacancy, lease expiry and changes in contributions can place pressure on the fund’s cash flow. A leaseback to your own business also needs planning for circumstances where that business can no longer pay rent.
A CALCULATION EXAMPLE
| Annual rent | $60,000 |
|---|---|
| Purchase price | $1,000,000 |
| Gross yield | 6% |
Before expenses, financing costs and tax. This is a calculation example, not a forecast return.
Assess my commercial rental incomeWHAT COMMERCIAL SMSF LENDERS ASSESS
Depending on the lender, member ages, retirement timing, guarantees and the repayment strategy may also be considered.
Financial statements, existing commitments, contributions, available deposit and liquid assets remaining after settlement.
Property type, location, value, marketability and the proposed loan against the lender’s accepted valuation.
Tenant details, rental evidence, lease term, options, incentives and responsibility for outgoings.
Accepted rent, contributions and other fund income assessed against repayments and ongoing commitments.
SMSF and holding-trust deeds, trustee details, financial records, purchase contract, lease and supporting professional advice.
COMMERCIAL SMSF SITUATIONS WE CAN ASSIST WITH
Assess lending for eligible premises your SMSF proposes to lease to your operating business.
Compare finance for qualifying offices, warehouses, industrial units and shops leased to independent businesses.
Review your existing loan’s rate, fees, term and lender requirements, subject to legal eligibility and a fresh credit assessment.
Check lender appetite before committing to a commercial property or finalising lease arrangements.
Coordinate finance requirements with your solicitor, accountant, financial adviser and SMSF administrator.
HOW WE WORK
Discuss the premises, intended tenant, purchase or refinance timing and current fund position.
Outline the fund, lease, property and financial information relevant lenders are likely to request.
Review commercial security requirements, LVR limits, servicing, liquidity and loan options.
Keep lender requirements aligned with the legal documentation and advice your professionals provide.
Prepare the application and assist through valuation, credit assessment, documentation and settlement.
Where appropriate, reassess the loan as products, policies or the fund’s circumstances change.
WHAT MAKES AUSFIRST DIFFERENT
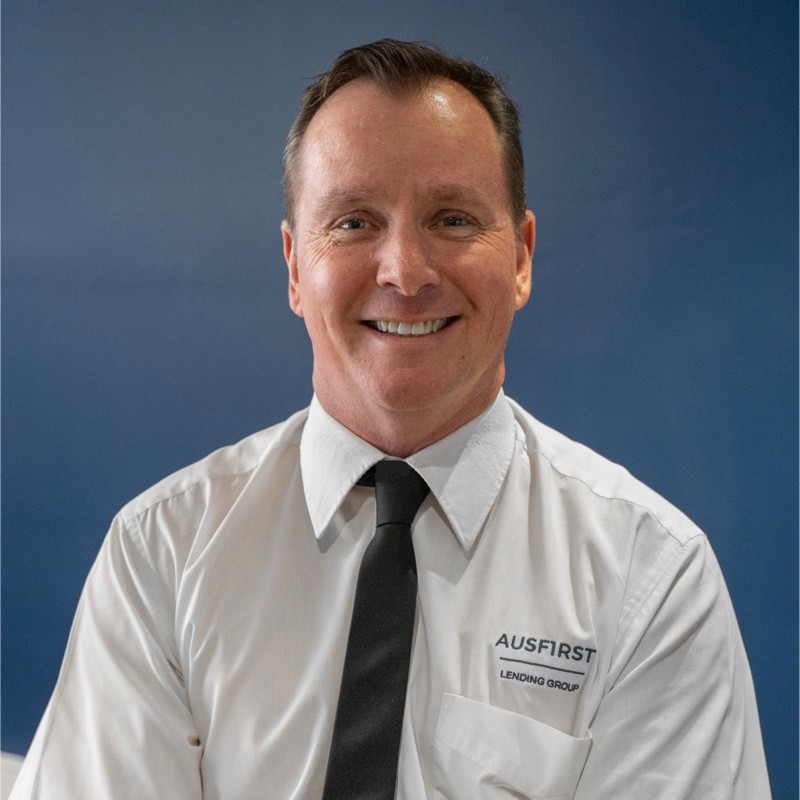
Work directly with an experienced Queensland broker on your commercial SMSF finance.
Richard is Director of Ausfirst Lending Group, with more than 30 years of experience across finance and lending, including the Commonwealth Bank and senior roles in finance businesses.
His work includes commercial property finance, SMSF borrowing and structured lending. He assesses proposals from a finance perspective, compares relevant lender policies and oversees applications alongside clients’ professional advisers.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews supplied for this page. They reflect individual service experiences and are not presented as commercial SMSF lending testimonials.
COMMERCIAL SMSF LOANS QUEENSLAND FAQS
Yes, through a compliant LRBA. Offices, warehouses, industrial units and shops may be suitable, subject to business real property eligibility, the fund’s circumstances and lender acceptance.
Broadly, it is an eligible interest in land or buildings used wholly and exclusively in one or more businesses. Actual use matters; a commercial label or zoning alone does not establish eligibility.
Potentially. Eligible business real property can be leased to a related operating business under a compliant arrangement. The lease needs market rent and arm’s-length terms, with advice on the applicable SMSF rules.
An exception to the related-party acquisition prohibition may permit business real property to be acquired at market value. Your advisers must confirm that the property and transaction meet the exception and all other applicable requirements.
It depends on the lender’s maximum LVR and accepted valuation. The fund also needs money for purchase costs and sufficient post-settlement liquidity. We assess these together rather than quoting a universal minimum.
That depends on the rent, expenses, loan terms and lender assessment. Lenders may discount rental income for servicing. A gross yield calculation alone does not establish affordability.
Affected real property LRBAs entered into from 10 August 2026 must involve business real property. ATO guidance requires that status to continue throughout the LRBA. Earlier arrangements may have transitional protection.
Refinancing may be possible, subject to the LRBA rules and lender assessment. The August 2026 amendments preserve qualifying refinancing of pre-commencement borrowings.
Requirements may include SMSF and holding-trust deeds, financial statements, bank statements, contribution records, the purchase contract, commercial lease and valuation. A related-business tenancy may require additional business financial information.
We are based at Suite 3/74 Bulcock St, Caloundra QLD 4551, and assist with commercial SMSF lending across Queensland.
COMMERCIAL SMSF LENDING QUEENSLAND
Have an office, warehouse, industrial unit, retail shop or business premises purchase in mind? Start with a lending assessment of the property, tenancy, fund income, deposit and liquidity. We compare relevant commercial SMSF lenders and coordinate their requirements with your professional advisers.
Your commercial proposal assessed
Relevant lender policies compared
Finance coordinated through to settlement
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, 9 am–5 pm
DISCUSS YOUR COMMERCIAL SMSF LOAN
Send us a few details about your proposed commercial purchase or refinance.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact formGeneral information only, checked October 2026. This content does not consider your objectives, financial situation or needs and is not personal financial, investment, superannuation, tax or legal advice. Obtain appropriate independent advice about your fund, business real property eligibility, LRBA structure and any transitional provisions. Lending is subject to lender assessment, valuation, eligibility, terms and fees.