Buy sooner
Stop chasing a 20% target while prices move, and start building equity earlier.
BUY WITH LESS THAN 20%
No 20% deposit yet?
You may still have options.
Saving a full 20% deposit is hard when prices keep rising. Low deposit loans, government schemes and family support can help you buy sooner. We compare the options from our lender panel and show the full cost of each. Personal guidance from Ausfirst Lending Group’s mortgage brokers in Brisbane and on the Sunshine Coast.
Excellent · 35 Google reviews
HOW LOW DEPOSIT LOANS WORK
Low deposit loans are high loan-to-value ratio (LVR) loans. Some lenders lend up to 90% or 95% of the property value, depending on your income, credit profile and their policies.
Stop chasing a 20% target while prices move, and start building equity earlier.
Lenders mortgage insurance offsets the lender’s higher risk, unless a scheme or waiver applies.
First home buyers, professionals and investors who meet specific lender criteria.
Not sure how much deposit you need? We’ll work out your LVR, costs and which options you may qualify for.
Start with a free chatWAYS TO BUY WITH A SMALLER DEPOSIT
Each path has different eligibility and costs. We compare the ones that apply to you.
Eligible first home buyers can buy with a 5% deposit and no LMI through a participating lender.
Borrow above 80% and pay LMI. Some lenders let you add it to the loan, though you’ll pay interest on it.
A family member’s property equity secures part of your loan, which can help you avoid LMI.
Some lenders waive LMI for eligible professions, such as doctors, on loans up to 85–90% LVR.
A QUICK COMPARISON
| What you compare | Wait for 20% | Buy sooner |
|---|---|---|
| Deposit | 20% of the price | From 5–10% |
| LMI | Generally none | Usually, unless exempt |
| Loan size | Smaller | Larger, more interest |
| Time to buy | Longer | Sooner |
Neither option suits everyone. Prices can rise while you save, but a larger loan means higher repayments.
Compare my optionsKNOW YOUR NUMBERS
See your LVR today and how long it could take to save a full 20% deposit at your current rate.
Then weigh that against buying sooner with a smaller deposit. We’ll show the real cost of each path.
Illustration only. Excludes stamp duty, buying costs, interest on savings and price changes while you save. Your borrowing capacity also depends on income and expenses.
Check my actual optionsBEFORE YOU COMMIT
A smaller deposit can get you in sooner, but it usually costs more over time. Strong income, secure work and a solid credit history can help you access better terms.
Beyond LMI, high LVR loans can carry a higher interest rate, and a larger loan means more interest over its life.
We compare these costs across lenders and schemes, so you can see what buying sooner really costs.
Run by Housing Australia (formerly NHFIC). Since 1 October 2025, there are no income caps or limits on places. Property price caps, owner-occupier requirements and lender approval still apply.
A deposit bond can stand in for the cash deposit when you sign a contract. It doesn’t reduce what you need at settlement, and not every seller accepts one.
We can explain whether one suits your purchase.
Scheme rules, lender policies and LMI premiums vary and can change. Confirm current eligibility before you rely on any option.
Let’s compare your paths. We’ll show the deposit, LMI and repayments for each option you qualify for.
Check my next stepsBEFORE YOU APPLY
Not every lender offers high LVR loans, and criteria are stricter than at 80% or below.
Secure, consistent income helps lenders accept a smaller deposit.
A clean history can mean better rates and more lender options.
Many lenders want evidence you’ve saved part of the deposit over time.
Some lenders limit high LVR loans on certain units or rural properties.
BEYOND THE DEPOSIT
Your deposit isn’t the only upfront cost. We help you plan for each one so there are no surprises at settlement.
Queensland offers concessions for eligible first home buyers, depending on the property.
Paid upfront or added to the loan, unless a scheme, waiver or guarantee applies.
Conveyancing, searches, registration and any lender application fees.
Savings set aside for rate rises, repairs and life’s surprises.
A family member willing to help? A guarantee may let you buy without LMI.
Explore family guaranteesFROM FIRST CHAT TO FIRST KEYS
We explain each stage, compare your deposit options and keep you informed through to settlement.
UNDERSTAND
Meet by phone, Zoom or in person. Tell us about your savings, income and the property you have in mind.
GATHER
We collect income documents and savings history, and check scheme eligibility.
ANALYSE & PLAN
We compare schemes, LMI, guarantees and waivers, then discuss conditional pre-approval.
APPLY
Once you’ve found a property, we finalise the application and liaise with the lender.
FINALISE
We coordinate with your lender and conveyancer and keep you informed through to settlement.
SUPPORT
Once you pass 80% LVR, a review could open up sharper rates.
WHY CHOOSE AUSFIRST LENDING GROUP
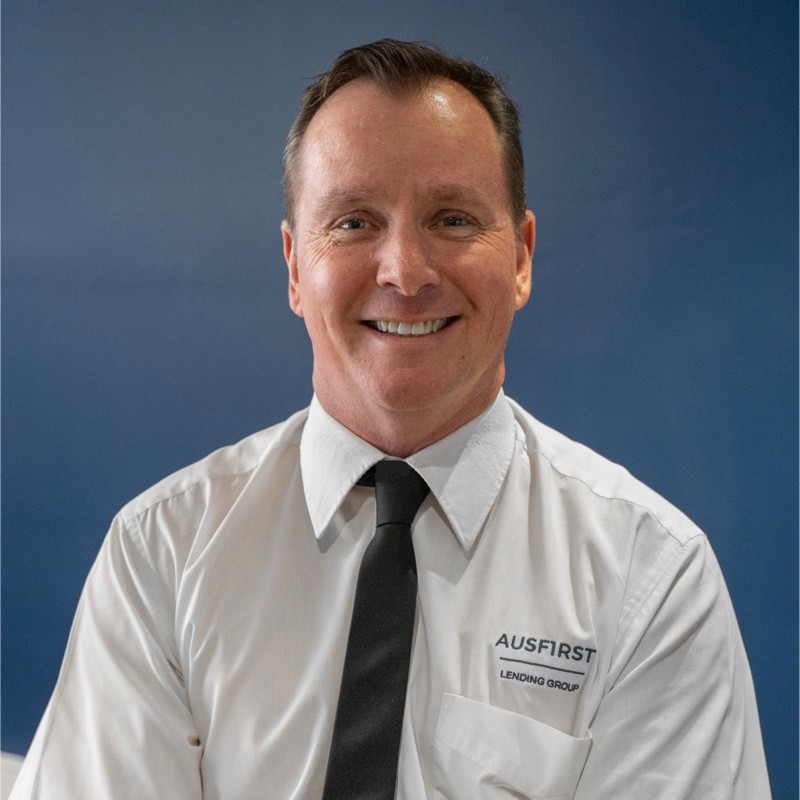
You’re looked after by someone who treats your financial success as his own.
Richard brings more than 30 years of hands-on broking experience. He takes the time to understand your savings, income and goals before comparing low deposit options from our panel.
From buying a home to refinancing or investing later on, you get clear advice and a long-term lending partner on the Sunshine Coast and in Brisbane.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Debbie made the process of buying a new house frictionless, by providing excellent support throughout”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions we’re asked most about buying with a smaller deposit. Your circumstances matter, so we’re happy to talk through the detail.
Ask about my depositEligible first home buyers may buy with 5% through the 5% Deposit Scheme. Otherwise, some lenders lend up to 90–95% with LMI. A family guarantee can reduce the cash needed further.
Not all lenders offer them. Major banks and non-bank lenders may have options, depending on your financial profile and the property you’re buying.
It’s possible. Rates depend on your deposit, income, profession and credit history. Some eligible professionals may borrow 85–90% without LMI, subject to lender policy.
They can be. Expect LMI and possibly a higher rate, plus more interest on a larger loan. Strong income and credit can help you access better terms.
Many lenders allow it, so you don’t pay it upfront. You’ll pay interest on it over the loan term, which adds to the overall cost.
Some major lenders offer low deposit loans, but eligibility varies. We assess your situation and identify lenders that suit your goals.
LET’S MAKE A START
Tell us about your savings and the property you’re aiming for. We’ll show which deposit paths you may qualify for and what each would cost.
Your LVR and deposit gap worked out
Schemes, LMI and guarantees compared
Personal guidance from an experienced team
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, 9 am–5 pm
YOUR FREE DEPOSIT CHAT
Send our team a little about your plans.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form