Pay less interest
Every dollar in the offset reduces the balance interest is charged on.
PUT YOUR SAVINGS TO WORK
Keep your savings accessible.
Pay less interest.
A 100% offset account links an everyday account to your home loan, so your balance reduces the interest you’re charged. We compare offset features across our lender panel, including fees, packages and conditions. Personal guidance from Ausfirst Lending Group’s mortgage brokers in Brisbane and on the Sunshine Coast.
Excellent · 35 Google reviews
HOW A 100% OFFSET ACCOUNT WORKS
Your offset balance is deducted from your loan balance before interest is calculated, so you’re charged only on the rest. The account works like a normal transaction account for your salary, bills and everyday spending.
Every dollar in the offset reduces the balance interest is charged on.
Funds stay available for everyday use and emergencies.
Keep repayments the same, and more of each one reduces the principal.
Already have a loan without an offset? We’ll check whether adding one or switching lenders is worth it.
Start with a free chatTHINGS TO CONSIDER
Offsets work best when you keep a consistent balance. They can suit people comfortable with digital banking and budgeting.
Your offset balance doesn’t earn interest. It saves interest on your loan instead.
The lower your average balance, the less interest you save.
Some lenders require a professional package or minimum loan size, often with an annual fee.
Full offsets are mostly available on variable rate loans. A split loan can give you both.
A QUICK COMPARISON
| What you compare | Extra repayments | Offset account |
|---|---|---|
| Reduces interest | Yes | Yes |
| Access to funds | Through redraw, if available | Anytime |
| Loan balance | Reduced | Unchanged |
| Best if you want | Discipline | Flexibility |
The right choice depends on your habits and need for access. Redraw conditions and offset features vary by lender.
Compare my optionsKNOW YOUR NUMBERS
Keeping your savings in an offset, rather than a separate account, can reduce interest over the life of your loan, and help you finish it sooner if you keep repayments the same.
We compare offset loans on fees and conditions too, so the savings aren’t eaten up by package costs.
Illustration only. Assumes the offset balance stays the same, repayments stay at the standard amount and the rate doesn’t change. Excludes fees.
Check my actual optionsREAD THE PRODUCT TERMS
Offset products work differently from lender to lender. The conditions can matter as much as the rate.

Some offsets reduce interest on 100% of the balance, others only part of it. Some lenders allow several linked accounts, which helps if you budget across separate pots.
Smaller banks and non-bank lenders sometimes offer offsets without bundled package fees.
Most fixed loans don’t offer a full offset, though a limited number of lenders do. A split loan lets you fix part and keep an offset on the variable part.
Where you hold savings, in an offset or as extra repayments, can affect future flexibility and tax. Talk to your accountant before choosing.
Offset features, fees and eligibility vary by lender and can change. Review the product terms before committing.
Let’s compare offset features. We’ll find loans whose offset fits how you bank, without unnecessary fees.
Check my next stepsWHO MIGHT BENEFIT
Offsets tend to deliver more when you keep a healthy balance, and suit people who prefer flexibility over locking funds into the loan.
Borrowers who keep a steady balance see the biggest benefit.
Salary paid straight into the offset works for you until it’s spent.
Funds for emergencies or upcoming costs stay accessible.
Interest savings without committing funds to the loan.
THE RIGHT STRUCTURE MATTERS
The best offset loan for you depends on your balance, habits and other features you need.
A 100% offset counts every dollar. A partial offset counts only a portion.
Some lenders link several offset accounts to one loan.
Annual package fees can outweigh savings on smaller balances.
Pair an offset with a split loan for certainty on part of the balance.
Refinancing or switching lenders? We’ll make sure the new loan’s offset works the way you need.
Talk about my loanFROM FIRST CHAT TO SETTLEMENT
We explain each stage, compare offset features and keep you informed through to settlement.
UNDERSTAND
Meet by phone, Zoom or in person. Tell us about your income, savings and spending habits.
GATHER
We collect income documents and details of your current loan and savings.
ANALYSE & PLAN
We compare rates, offset features, packages and fees across our panel.
APPLY
We prepare your application and liaise with the lender on approval.
FINALISE
We manage settlement and make sure your offset is linked correctly.
SUPPORT
We review your loan as rates, savings and your needs change.
WHAT MAKES AUSFIRST DIFFERENT
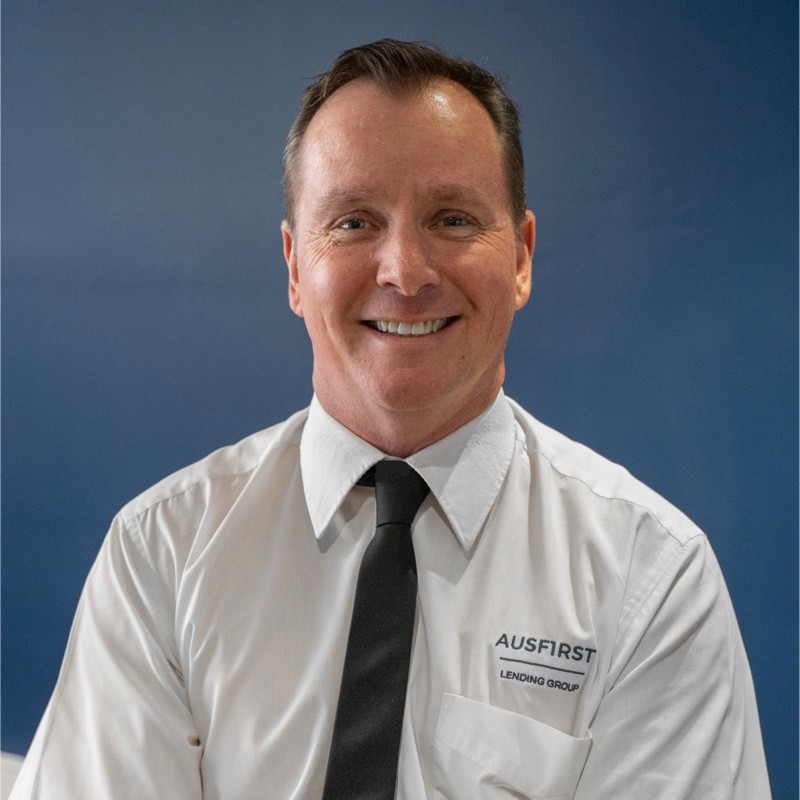
You’re looked after by someone who treats your financial success as his own.
You deal directly with Richard, the founder, who brings more than 30 years of hands-on experience across Queensland. Unlike larger brokerages, you won’t become just another file number.
Richard personally oversees your loan, from comparing offset features to settlement, including for self-employed borrowers whose finances don’t fit a standard bank box.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Debbie made the process of buying a new house frictionless, by providing excellent support throughout”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions we’re asked most about 100% offset home loans. Your circumstances matter, so we’re happy to talk through the detail.
Ask about offsetsNo. Availability depends on the lender, product and loan amount, and some offsets come only with certain packages. Some smaller and non-bank lenders offer offsets without extra package fees.
Both reduce interest. An offset keeps your money accessible, which suits variable income or upcoming costs. Extra repayments reduce temptation to spend but are harder to access. Services Australia’s Financial Information Service offers free guidance.
Borrowers with consistent savings or strong cash flow, such as professionals with predictable income, families with surplus after expenses, and investors who value flexibility.
Most fixed loans don’t offer a full offset, though a few lenders do. A split loan lets you fix part of your loan and keep an offset on the variable part.
Generally no. An offset reduces interest you’re charged rather than earning interest, so there’s usually nothing to declare. Check with your accountant, especially for investment loans.
LET’S TALK
Have questions about how an offset could fit your loan? Speak with our team. No pressure, just practical guidance tailored to your circumstances.
Offset features and fees compared
Your potential savings worked out
Personal guidance from an experienced team
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, 9 am–5 pm
YOUR FREE OFFSET CHAT
Send our team a little about your savings and goals.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form