LMI often waived
Many lenders waive LMI for eligible doctors, even with a deposit under 20%.
FOR MEDICAL PROFESSIONALS
Lenders treat doctors differently.
Mostly in your favour.
Because medical professionals are seen as low-risk, stable earners, many lenders waive LMI for eligible doctors, allow higher LVRs and offer professional-package pricing. We assess a panel of 40+ lenders, work out which medico policies you actually qualify for and manage the application through to settlement. Personal guidance from Ausfirst Lending Group in Caloundra.
Excellent · 35 Google reviews
WHY THE BENEFITS EXIST
Lenders compete for medical professionals because of stable, high earning potential and very low default rates. But eligibility, the professions covered and the size of the benefit vary a lot between lenders. The value is in matching you to the right one, not assuming every “doctor deal” applies.
Many lenders waive LMI for eligible doctors, even with a deposit under 20%.
Overtime, on-call and allowances can count heavily with the right lender.
The same person from first chat through to settlement.
Intern, resident or registrar? Many lenders extend doctor policies to earlier career stages when you’re AHPRA-registered.
Start with a free chatTHE ADVANTAGES
Subject to lender policy and your profession.
Often up to 90%, and in some cases 95%, of the property value. On a larger purchase, that can save thousands upfront.
Buy a higher-value home or investment with a smaller deposit.
Discounted or package rates, a meaningful saving over the loan’s life.
Offset, redraw and flexible repayments around on-call work and variable rosters.
HOW YOU’RE PAID
| What changes | Hospital (PAYG) | Private practice |
|---|---|---|
| Income proof | Payslips | Two years’ returns |
| Base income | Usually 100% | Profit plus add-backs |
| Overtime, on-call | Often 80–100% | Within business profit |
| Medico benefits | Yes, if eligible | Yes, if eligible |
Some lenders consider a shorter history, BAS or interim financials for self-employed doctors. Policies vary.
Check my optionsKNOW YOUR NUMBERS
A smaller deposit without LMI leaves more cash for an offset account, your practice or your next investment.
We check which lenders waive LMI for your profession, at what LVR, and whether their loan limits fit your purchase.
Illustration only, not a borrowing assessment. Excludes stamp duty and buying costs. Eligibility, waiver LVRs and loan limits vary by lender.
Check my actual optionsEVERY CAREER STAGE
Many lenders extend doctor policies to interns, residents and registrars, and sometimes to final-year students with a graduate role confirmed. Benefits may scale with career stage.

GPs, specialists, surgeons and dentists are commonly covered. Some lenders extend medico policies to optometrists, pharmacists, physiotherapists, vets and others.
Because each lender’s list differs, we check before you apply.
Two medical professionals applying together can often access doctor benefits across the whole loan, with combined income lifting capacity.
Some lenders consider doctors on temporary skilled visas, such as the 482, usually with a larger deposit and tighter conditions.
Lender policies on medico waivers, eligible professions and visas vary and can change.
Let’s check what you qualify for. We’ll match your profession, stage and income to the right lender.
Check my next stepsAM I ELIGIBLE?
Doctor policies aren’t identical between lenders, but most come down to these.
Practising in a recognised medical field and registered with AHPRA.
Citizens and permanent residents qualify most easily.
PAYG on base salary; self-employed usually on two years’ returns.
Minor blemishes change which lenders offer their best terms.
THINGS TO WEIGH UP
A doctor loan should still fit your life, not just the lender’s limit.
A higher approval isn’t a target. We size the loan to what’s comfortable.
Reduced hours or time out can affect a loan set against a higher income.
Build room for rate rises before stretching your budget.
Waivers often cap the loan size on larger purchases.
Already have a loan? Doctor benefits can apply when you refinance, not only when you buy.
Explore refinancingHOW WE WORK
We know which lenders waive LMI for which professions, and who prices doctors best, so your file isn’t left on a generic policy.
CONVERSATION
What you can borrow and which doctor policies you qualify for.
COMPARE
Matching your profession and income to lender rules.
STRATEGY
The medico policy and pricing that best fit your situation.
APPLICATION
Including AHPRA and income evidence, liaising with lender and solicitor.
SETTLEMENT
We coordinate settlement around your rosters.
AND BEYOND
We review your loan to check it remains competitive.
WHAT MAKES AUSFIRST DIFFERENT
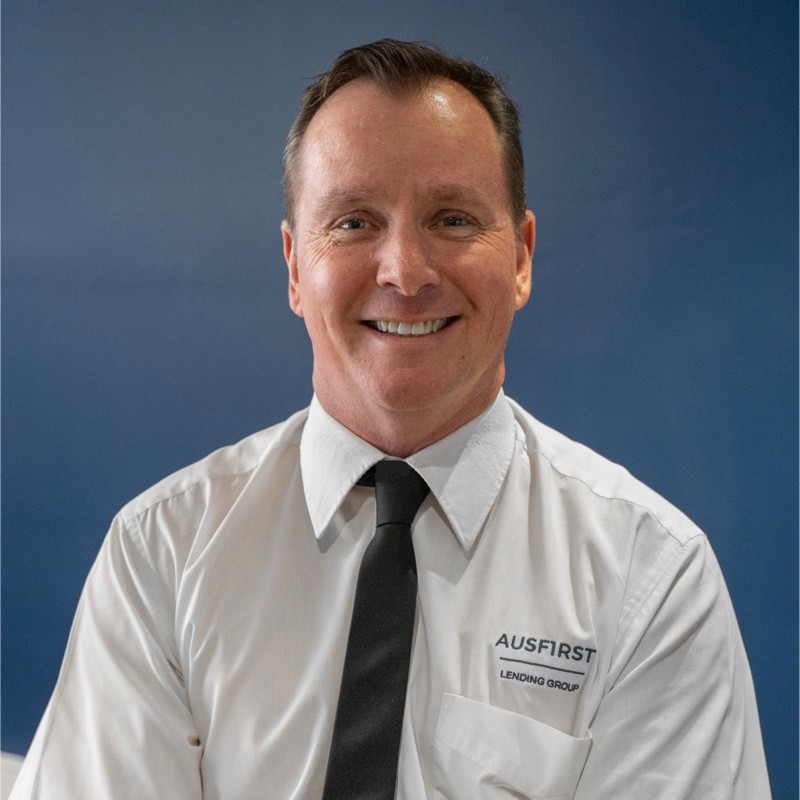
You’re looked after by someone who treats your financial success as his own.
You work directly with Richard Luke, our director, with more than 30 years in Queensland lending. Not a call centre, and not a different voice each time.
He takes the time to understand your profession, career stage and goals, whether you’re buying your first home, refinancing or growing a portfolio.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Debbie made the process of buying a new house frictionless, by providing excellent support throughout”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions doctors ask us most. Your profession and stage matter, so we’re happy to talk through the detail.
Ask a questionNot automatically. Many lenders waive it for eligible doctors, often up to 90% and sometimes 95%, but it depends on your profession, income and lender policy.
GPs, specialists, surgeons and dentists are commonly included. Some lenders extend to optometrists, pharmacists, physios, vets and others.
Often, yes. Many lenders include earlier career stages, sometimes final-year students with a confirmed role. AHPRA registration in a recognised role is usually key.
Yes. Practice owners and those paid through a company or trust are usually assessed on two years’ returns with add-backs. Medico benefits still apply where eligible.
Usually in part, often 80–100% of consistent overtime, on-call and allowances with a reasonable history. It varies by lender.
Yes. You can often access doctor benefits across the whole loan, and combined income can significantly lift borrowing capacity.
Sometimes. Some lenders consider doctors on temporary skilled visas, usually with a larger deposit and tighter conditions.
Yes. Waived LMI where eligible, professional pricing and higher LVRs can apply when you refinance, not just when you buy.
For most home loans, no. Lenders pay us a commission on settlement. We disclose any fees before you proceed.
START WITH A CONVERSATION
Tell us your profession, your stage and what you’re buying. We’ll show you which medico benefits you qualify for and what you can borrow.
LMI waiver eligibility checked
Medico pricing compared
Direct access to Richard
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, and by appointment
YOUR FREE CONSULTATION
Your profession, stage and what you’re buying.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form