Upgrade your home
Buy a bigger family home and keep your current one as an investment, or sell it later.
YOUR NEXT PROPERTY STARTS HERE
Ready for property number two?
Let’s make the numbers work.
Upgrading, buying a holiday home or adding an investment, the equity in your current home can help fund the next one. We work out what you can borrow, compare loans from our lender panel and structure them around your plans. Personal guidance from Ausfirst Lending Group’s mortgage brokers in Brisbane and on the Sunshine Coast.
Excellent · 35 Google reviews
WHAT IS A SECOND HOME LOAN?
A second home loan funds another property while you keep your first. Many buyers use equity in their current home towards the deposit, so they can expand without selling existing assets.
Buy a bigger family home and keep your current one as an investment, or sell it later.
Secure a getaway for the family, with the option of renting it out when you’re not using it.
Add a rental property to build long-term wealth alongside your home.
Not sure how much equity you have? We’ll estimate it and explain what it could mean for your next purchase.
Start with a free chatWAYS TO FUND IT
The right approach depends on your equity, savings and what you plan to do with your current home.
Release equity in your current home to cover the deposit and costs, keeping your savings as a buffer.
Move into the new property and rent out the old one. Its loan may need restructuring as an investment loan.
A bridging loan can cover the gap if you buy your next home before selling your current one.
Separate loans for each property can make it easier to sell, refinance or switch lenders later.
A QUICK COMPARISON
| What you compare | Cash deposit | Using equity |
|---|---|---|
| Source | Your savings | Your current home |
| Timing | Once you’ve saved | Once valued and approved |
| Current loan | Unchanged | Balance increases |
| Your buffer | Savings used up | Savings kept |
Borrowing against your home increases your debt and repayments. Lending criteria apply.
Compare my optionsCAN YOUR EQUITY COVER IT?
Lenders typically let you borrow up to 80% of your home’s value, less what you owe. That usable equity can go towards a 20% deposit on your next property, which generally avoids LMI.
Remember to allow for stamp duty and buying costs on top of the deposit.
Illustration only, not a borrowing assessment. Uses 80% of your estimated value; the lender’s valuation may differ. Excludes stamp duty and buying costs. Your income and expenses also determine what you can borrow.
Check my actual optionsBEFORE YOU BUY
A second property brings costs and rules that don’t apply to your first. We help you plan for them before you commit.

There’s no government grant for second home buyers, and first home duty concessions won’t apply. In Queensland, a home concession may still apply if the new property becomes your principal place of residence.
Allow for LMI if your deposit is under 20%, plus holding costs like rates, insurance and maintenance on two properties.
Your current loan may need restructuring, and lenders count only part of the rent when assessing what you can borrow.
Talk to your accountant about tax before you move out.
A holiday home you also rent out may be assessed as an investment, and rental income can be seasonal.
Duty concessions, tax treatment and lender policies vary and can change. Confirm your position with your conveyancer and accountant.
Let’s map out the costs. We’ll show your deposit, buying costs and repayments on both properties.
Check my next stepsBEFORE YOU APPLY
Lenders look at your whole position, including your current mortgage, before approving another loan.
Income, living costs and credit history set how much more you can borrow and repay.
Your current balance and repayments are counted against your capacity.
A valuation of your current home shows how much equity you can use.
If either property will be rented, lenders count part of the rent.
THE RIGHT STRUCTURE MATTERS
The right mix depends on how you’ll use the property and your cash flow. We help you compare features against your plans.
Repayments stay the same for the fixed term, making two loans easier to budget for.
Your rate moves with the market, often with extra repayments and redraw.
Fix part of the loan for certainty and keep the rest variable.
Reduce the balance used to calculate interest while keeping your buffer accessible.
Planning to rent out your current home or keep both? We’ll structure the loans with that in mind.
Talk about my plansFROM FIRST CHAT TO SETTLEMENT
We explain each stage, prepare the application with you and keep you informed through to settlement.
UNDERSTAND
Meet by phone, Zoom or in person. Tell us what you’re buying, and what happens to your current home.
GATHER
We collect income documents and loan details, and estimate the equity in your home.
ANALYSE & PLAN
We compare lenders and loan structures, then discuss conditional pre-approval so you can search with confidence.
APPLY
Once you’ve found a property, we finalise the application and liaise with the lender on valuations.
FINALISE
We coordinate with your lender and conveyancer and keep you informed through to settlement.
SUPPORT
We review your loans as rates, values and your plans change.
WHAT MAKES AUSFIRST DIFFERENT
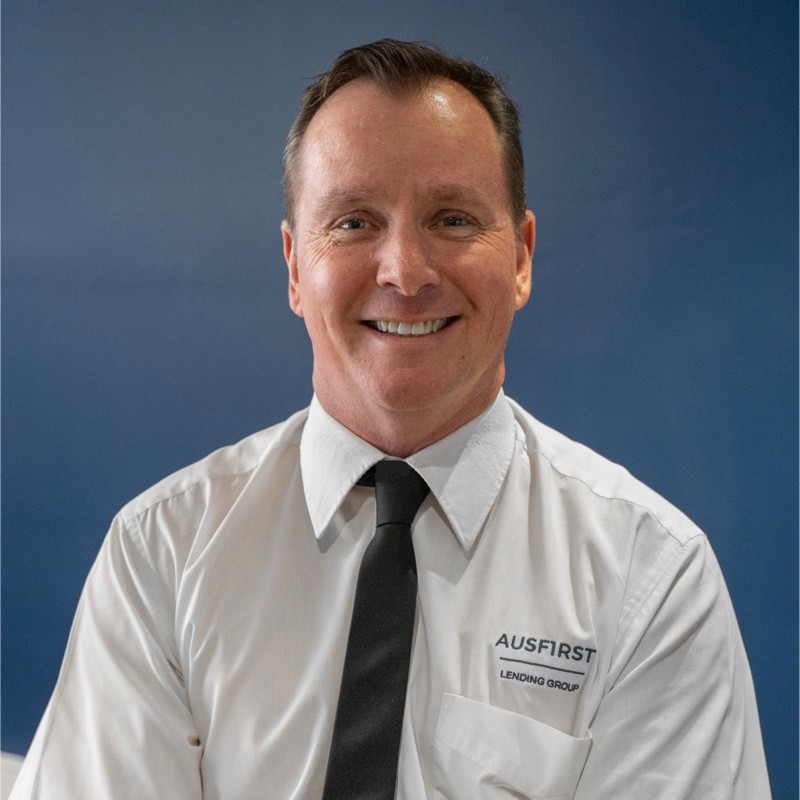
You’re looked after by someone who treats your financial success as his own.
Richard brings more than 30 years of hands-on broking experience. He takes the time to understand your finances and long-term goals before comparing second home loan options from our panel.
Whether you’re upgrading, buying a holiday home or using equity to invest, you get clear advice, regular updates and the same team from application to settlement.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Debbie made the process of buying a new house frictionless, by providing excellent support throughout”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions we’re asked most about buying a second property. Your circumstances matter, so we’re happy to talk through the detail.
Ask about my situationYes. Lenders assess your income, current mortgage and available equity to work out how much more you can borrow.
Usually 10–20% of the purchase price, depending on the lender and your situation. Equity in your current home can often cover some or all of it. A 20% deposit generally avoids LMI.
Many lenders allow up to 80% of your home’s value, less your current loan balance. Your income, expenses and credit history also determine your borrowing capacity.
Often, yes. Your current lender may increase your loan or set up a separate loan split. Refinancing to a new lender is another option if it offers better terms.
Yes, most lenders do. If the property will be an investment, rates and criteria may differ from an owner-occupied loan.
No. First home grants and concessions don’t apply. If the new property becomes your principal place of residence, a state home concession on duty may still apply, so check with your conveyancer.
It can be, if you have solid equity, steady income and a buffer. Consider the higher debt, repayments on two properties and how rate rises would affect you.
We estimate your equity, compare lenders and loan structures, and manage the application, so both loans work together for your plans.
LET’S MAKE A START
You don’t need a property picked out. Tell us what you’re hoping to buy, and we’ll help you understand your equity, borrowing position and next steps.
A clear look at your usable equity
Loan structures for both properties compared
Personal guidance from an experienced team
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, 9 am–5 pm
YOUR FREE SECOND HOME CHAT
Send our team a little about your plans.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form