Professional benefits
Some lenders extend LMI waivers and pricing to eligible engineers.
FOR ENGINEERING PROFESSIONALS
A stable profession.
Income read the right way.
Civil, electrical, mechanical, mining or any other discipline, some lenders reward engineers with potential LMI waivers, discounted rates and fee reductions. Where you most need a specialist is income: bonuses, site allowances, FIFO and contract work are read very differently between lenders. We present yours the way lenders assess it, across a panel of 40+ lenders. Personal guidance from Ausfirst Lending Group in Caloundra.
Excellent · 35 Google reviews
STABLE PROFESSION, VARIABLE INCOME
The complication is rarely the profession. Contract terms, project gaps, bonuses and site allowances can make a strong earner look inconsistent to the wrong lender. Presented properly, to a lender that understands engineering income, both work in your favour.
Some lenders extend LMI waivers and pricing to eligible engineers.
Bonuses, overtime, allowances, FIFO and fixed-term work, read the right way.
The same person from first chat through to settlement, not a call centre.
Benefits are more conditional than for medicos. We check which lenders extend them to engineers rather than assume.
Start with a free chatWHAT ENGINEERS MAY ACCESS
Subject to lender policy and eligibility.
Some lenders may waive LMI for eligible engineers with under 20% deposit. We confirm it against current policy first.
Professional or package pricing reflecting career stability, a meaningful saving over time.
Application, package or account fees reduced or waived by some lenders.
Offset, redraw and flexible repayments to manage bonuses and gaps between contracts.
HOW YOU’RE EMPLOYED
| What changes | Permanent | Contract | Own ABN |
|---|---|---|---|
| Income proof | Payslips | Contract, payslips | Two years’ returns |
| Base income | Usually 100% | Lender-dependent | Profit plus add-backs |
| Time in role | Often 6 months | Continuous history | Usually 2 years |
| Lender choice | Widest | Varies most | Narrower |
Some lenders consider a low-doc approach for newer ABNs. Policies vary.
Check my optionsKNOW YOUR NUMBERS
Lenders count your base salary in full, but bonuses, overtime and site or FIFO allowances are often shaded, sometimes heavily. The right lender counts more of what you actually earn.
That difference can move your borrowing capacity significantly.
Illustration only, not a borrowing assessment. Lenders usually need a consistent history for extras, and some count bonuses and allowances differently. Annual amounts before tax.
Check my actual optionsHOW YOUR INCOME IS ASSESSED
Full-time permanent engineers are the simplest to assess, usually on 100% of base salary after around six months in the role. Everything else is where lenders differ.

Fixed-term, day-rate and project work is where lenders differ most. Many lend as normal with a solid contract and continuous history; others tighten conditions.
A clear work history, a signed contract and clean statements turn scrutiny into a formality.
Consistent bonuses, overtime and site or FIFO allowances can be counted, often partially and sometimes in full with history.
Assessed as self-employment, usually on two years of returns. A low-doc approach can help newer ABNs.
See self-employed home loansLender policies on engineer benefits and income assessment vary and can change.
Let’s read your income properly. We’ll match how you’re paid to the lender that counts the most of it.
Check my next stepsTHINGS TO WEIGH UP
An engineer’s loan should still fit your work pattern and your life.
Contract and project income invites closer questions. Good paperwork answers them.
On fixed-term work or in a cyclical sector, build room for rate rises.
An offset buffer helps you ride out a gap without strain.
Some lenders consider 482 visa holders, often with a larger deposit.
WHY ENGINEERS WORK WITH AUSFIRST
A strong earner shouldn’t be undersold because the income looks lumpy.
Day rates, fixed-term contracts, FIFO allowances and bonuses.
Which lenders extend waivers and pricing, so you don’t assume.
You work directly with Richard Luke, not a call centre.
Lenders pay us on settlement. We disclose any fees before you proceed.
No waiver available? Low deposit options or a family guarantee can still get you in.
Explore low deposit loansHOW WE WORK
A simple process built around reading your income properly before anything is lodged.
CONVERSATION
What you can borrow once your income is read properly.
ELIGIBILITY
Which waivers and pricing you may qualify for.
STRATEGY
The policy and income rules that best fit how you earn.
APPLICATION
Payslips, contracts and income evidence, liaising with lender and solicitor.
SETTLEMENT
We coordinate settlement around your roster or site time.
AND BEYOND
We review your loan to check it remains competitive.
WHAT MAKES AUSFIRST DIFFERENT
You’re looked after by someone who treats your financial success as his own.
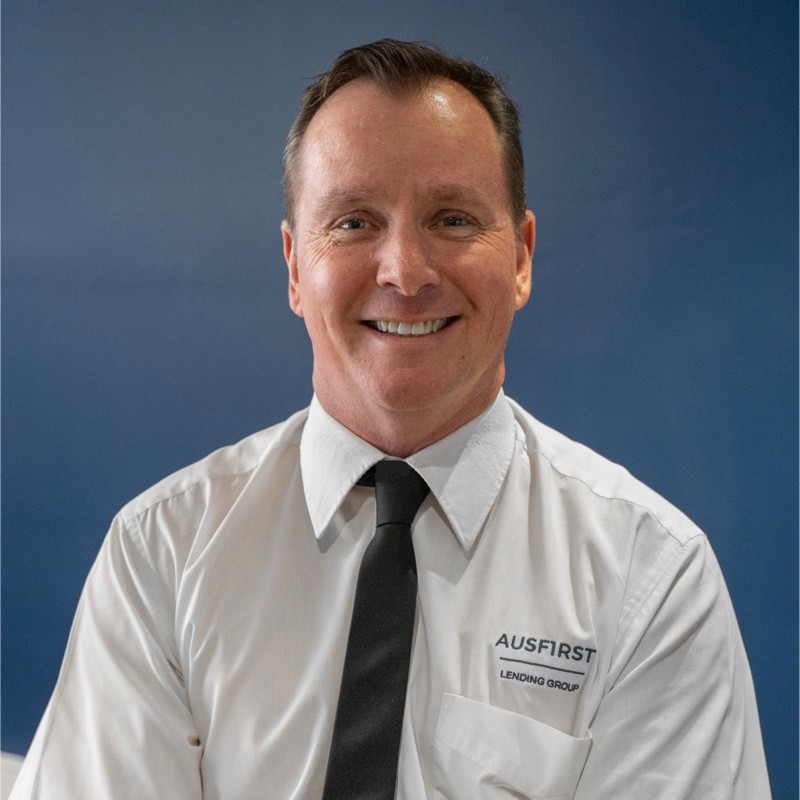
You work directly with Richard Luke, our director, with more than 30 years in Queensland lending. Not a call centre, and not a different voice each time.
Whether you’re buying your first home, upgrading, refinancing or investing, he takes the time to understand your profession, income structure and plans.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Debbie made the process of buying a new house frictionless, by providing excellent support throughout”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions engineers ask us most. How you’re employed matters, so we’re happy to talk through the detail.
Ask a questionWith some lenders, yes: potential LMI waivers, discounted pricing and fee reductions. They’re more conditional than for medical professionals, so we check which apply to you.
Sometimes. Some lenders may waive LMI for eligible engineers with under 20% deposit, depending on the lender, your income and your role.
Yes. Some lenders are cautious with contract or self-employed income; others lend as normal with a solid contract or two years of returns.
Usually in part, and sometimes in full with a consistent history. How much counts varies by lender.
Not necessarily. With a waiver, some lenders allow up to 90% LVR. Without one, low deposit options or a family guarantee can help.
Payslips, bank statements, ID and debt details, plus a contract if you’re on a project role, or two years of returns if self-employed.
Sometimes. Some lenders consider 482 visa holders, usually with a larger deposit and tighter conditions.
A bank only applies its own view of contract or bonus income. We match your income pattern to a lender that reads it favourably, at no direct cost for most home loans.
START WITH A CONVERSATION
Tell us how you’re employed and what you’re buying. We’ll show you which benefits you qualify for and what you can borrow.
Professional benefits checked
Contract, FIFO and bonus income read properly
Direct access to Richard
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, and by appointment
YOUR FREE CONSULTATION
Permanent, contract, FIFO or consulting, and what you’re buying.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form