Teacher pay, read properly
Salary, allowances, casual loading and packaging, matched to lenders that count them.
FOR TEACHERS AND EDUCATION STAFF
Permanent, contract or casual.
Matched to the right lender.
Some lenders treat teaching favourably, with LMI waivers or discounts, professional pricing and fee reductions for eligible teachers. But the perks, and how your income is read, vary a lot between lenders. We compare 40+ lenders to find the policy that fits your role, allowances and salary packaging. Personal guidance from Ausfirst Lending Group in Caloundra.
Excellent · 35 Google reviews
THE PERKS ARE REAL, BUT LENDER-SPECIFIC
LMI waivers, professional pricing and fee reductions aren’t automatic, and eligibility rules differ. Permanent, contract and casual teachers are also assessed differently. We match your role and income to a lender whose policy works in your favour.
Salary, allowances, casual loading and packaging, matched to lenders that count them.
Which offer teacher benefits, and which suit how you’re employed.
The same person from first chat to settlement, not a call centre.
A “teacher rate” isn’t always best. Once fees and features are counted, another loan may cost less. We compare the real cost.
Start with a free chatHOW LENDERS ASSESS TEACHER INCOME
And where lenders differ most.
Base salary is straightforward, and many lenders count consistent allowances too.
Higher hourly rates, but gaps between terms. Lenders want six to twelve months of pattern.
Some lenders are cautious; others lend as normal with a signed contract or the right history.
Common in non-government schools. The right lender grosses it up and adds it to your income.
HOW YOU’RE EMPLOYED
| What changes | Permanent | Contract | Casual |
|---|---|---|---|
| Income proof | Payslips | Contract, payslips | Pattern of shifts |
| History needed | Often short | Lender-dependent | Usually 6–12 months |
| Lender choice | Widest | Varies | Varies most |
Lender policies on contract, casual and packaged income vary and can change.
Check my optionsKNOW YOUR NUMBERS
Allowances and salary packaging can lift the income a lender assesses, if they’re counted properly.
Bring a recent payslip and we’ll show you what each lender would count.
Illustration only, not a borrowing assessment. Packaging grossed up assuming a 30% tax rate; lenders use their own method. Annual amounts.
Check my actual optionsLMI, DEPOSIT AND FIRST-HOME OPTIONS
Matched to your deposit and situation, and checked against what you actually qualify for.
Some lenders offer LMI waivers or discounts to eligible teachers, subject to role, income and policy.
We check whether you qualify rather than assume it, and look at other paths if you don’t.
The 5% Deposit Scheme may let first home buyers in with a smaller deposit and no LMI. We check what you qualify for.
Equity in a parent’s home as extra security can remove LMI and get you in without a full deposit.
See family guaranteesNo waiver? You can still buy above 80% with LMI.
Let’s find your smallest sensible deposit. We’ll compare waivers, schemes and guarantees for your situation.
Check my next stepsWHAT YOU’LL NEED TO QUALIFY
Every lender is different, but these matter most.
Payslips, plus an employment letter or shift history if contract or casual.
Base salary, allowances, casual loading and packaging.
Past issues change which lenders will consider you.
Savings, equity, a family guarantee or a first home scheme.
THINGS TO WEIGH UP
Before you commit.
Budget for school holidays so repayments stay comfortable all year.
The maximum approval isn’t always what suits your budget.
A badged teacher offer isn’t always the cheapest once fees count.
Lenders pay us on settlement. We disclose any fees before you proceed.
Buying with less than 20%? See how low deposit loans work.
Explore low deposit loansHOW WE WORK
We work around the school day, by phone, Zoom or in person.
CONVERSATION
What you can borrow once your role and allowances are counted.
PAYSLIPS
Salary, allowances, casual loading and packaging.
STRATEGY
The teacher policy and pricing that best fit.
APPLICATION
Liaising with the lender, agent and solicitor.
SETTLEMENT
We coordinate settlement and keep you informed.
AND BEYOND
We review your loan to check it remains competitive.
WHY TEACHERS WORK WITH AUSFIRST
You’re looked after by someone who treats your financial success as his own.
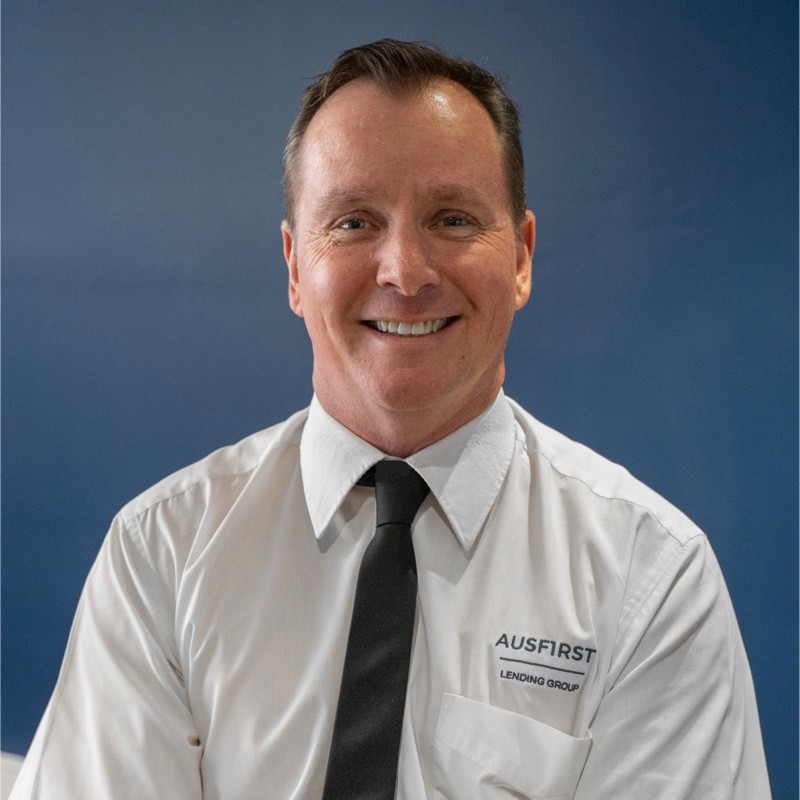
You work directly with Richard Luke, our director, with more than 30 years in Queensland lending. Not a call centre, and not a different voice each time.
We know which lenders offer teacher benefits, and who counts casual, contract and packaged income, so your file isn’t undersold.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Debbie made the process of buying a new house frictionless, by providing excellent support throughout”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions teachers ask us most. Bring a payslip and we’ll talk through the detail.
Ask a questionSometimes. Some lenders offer waivers or discounts to eligible teachers, depending on role, income and policy. If not, low deposit, family guarantee or first home options may help.
Base salary, consistent allowances and salary packaging where your school offers it. Casual teachers are assessed on their pattern of work.
Yes, usually with six to twelve months of consistent work. Some lenders are far more comfortable with casual teaching income than others.
Often, yes. Some lenders lend as normal with the right history or a signed contract.
It depends. A waiver, the 5% Deposit Scheme or a family guarantee may reduce it; otherwise you can buy above 80% with LMI.
START WITH A CONVERSATION
Bring a recent payslip and we’ll show you what you can borrow, and which teacher benefits you qualify for.
Allowances and packaging counted
LMI and deposit options compared
Direct access to Richard
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, and by appointment
YOUR FREE CONSULTATION
Permanent, contract or casual, and what you’re buying.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form