Own your premises
Stop paying rent to a landlord and build equity in the property your business uses.
COMMERCIAL PROPERTY FINANCE
Buy your premises, or invest.
On the right loan structure.
Whether you’re buying business premises or investing in office, industrial or retail property, we compare commercial lenders on rates, terms and LVR. We consider your cash flow, the lease and the valuation together, and help with trust, company or SMSF structures. Guidance from Ausfirst Lending Group, based in Caloundra.
Excellent · 35 Google reviews
HOW COMMERCIAL PROPERTY LOANS WORK
A lender funds the purchase and you repay with interest over an agreed term. Because lenders see commercial property as higher risk, expect a larger deposit, lower maximum LVRs and generally higher rates than residential lending.
Stop paying rent to a landlord and build equity in the property your business uses.
Commercial leases are often longer than residential, which can mean steadier income.
Add offices, warehouses, retail or industrial property to your business or investment assets.
Patchy credit history? Some non-bank lenders may still help, though usually with stricter conditions or higher rates.
Start with a free chatWHAT YOU CAN FINANCE
Each property type carries different risk for lenders, which affects the deposit, rate and terms you’re offered.
From small strata suites to whole buildings, for your own business or to lease out.
Workshops, sheds and industrial units, often with longer leases to established tenants.
Shops and shopfronts, where location and tenant strength matter heavily to lenders.
Mixed-use developments and specialised properties, subject to the lender’s criteria.
A QUICK COMPARISON
| What you compare | Residential | Commercial |
|---|---|---|
| Typical deposit | 5–20% | 20–30% or more |
| Interest rates | Lower | Generally higher |
| Loan terms | Up to 30 years | Often shorter, with reviews |
| Assessed on | Your income | Financials, lease, valuation |
Terms, LVR limits and rates vary by lender, property type and borrower. Approval depends on the lender’s assessment.
Compare my optionsKNOW YOUR NUMBERS
For leased investment property, many lenders check how comfortably the rent covers the interest, known as the interest cover ratio. A stronger ratio and a longer lease can support better terms.
For owner-occupied premises, lenders look more at your business’s own cash flow.
Illustration only, not a borrowing assessment. Deposit excludes stamp duty, GST, legal and valuation costs. Interest cover uses net rent against one year of interest. Lender requirements vary.
Check my actual optionsWHAT TO CONSIDER BEFORE APPLYING
Commercial lenders look at the property as closely as the borrower. Planning for valuation, lease and compliance issues early avoids surprises late in the deal.
An independent commercial valuation sets the value the lender will lend against. If it comes in below the price, you’ll need a bigger deposit.
Check zoning and permitted use with your council and solicitor before committing, especially if you plan to change how the property is used.
Lenders focus on your business’s profitability and cash flow, as the business pays the loan. A clear business plan can strengthen the application.
Lease terms, tenant quality and remaining lease length drive the assessment. Long, secure leases are viewed more favourably.
GST, stamp duty and tax on commercial property can be complex. Speak with your accountant and solicitor before you buy.
Let’s check the deal stacks up. We’ll look at the property, lease and your financials before approaching lenders.
Check my next stepsREQUIREMENTS
Being ready with these makes the application smoother and can improve the terms you’re offered.
Usually 20–30% of the price, for an LVR of 70–80%. Higher-risk property may need more.
Business financial statements, personal and business tax returns, and any trust deeds.
A strong record helps you access better terms. Options may exist even with past issues.
How the property fits your business, or details of current and proposed tenants.
OWNERSHIP STRUCTURES
The buying entity affects lender choice, documents and tax. Get advice from your accountant, then we’ll match lenders to the structure.
Fewer documents, assessed on your personal and business income.
Company financials, with directors usually giving guarantees.
The deed must allow borrowing. See trust loans.
Must meet SMSF borrowing rules. See SMSF loans.
Already own commercial property? Refinancing could improve your rate, terms or free up equity.
Talk about refinancingFROM FIRST CHAT TO SETTLEMENT
Richard manages your loan personally, coordinating with your accountant, solicitor and valuer through to settlement.
UNDERSTAND
Meet by phone, Zoom or in person. Tell us about the property, the lease and your plans.
GATHER
Business statements, tax returns, lease details and any trust or company documents.
ANALYSE & PLAN
We compare rates, terms, LVRs and conditions against the property and your structure.
APPLY
We present the business, property and lease clearly, and arrange the commercial valuation.
FINALISE
We walk you through the terms, covenants and guarantees, then coordinate settlement.
SUPPORT
Commercial loans are often reviewed periodically. We help you prepare and refinance if needed.
WHAT MAKES AUSFIRST DIFFERENT
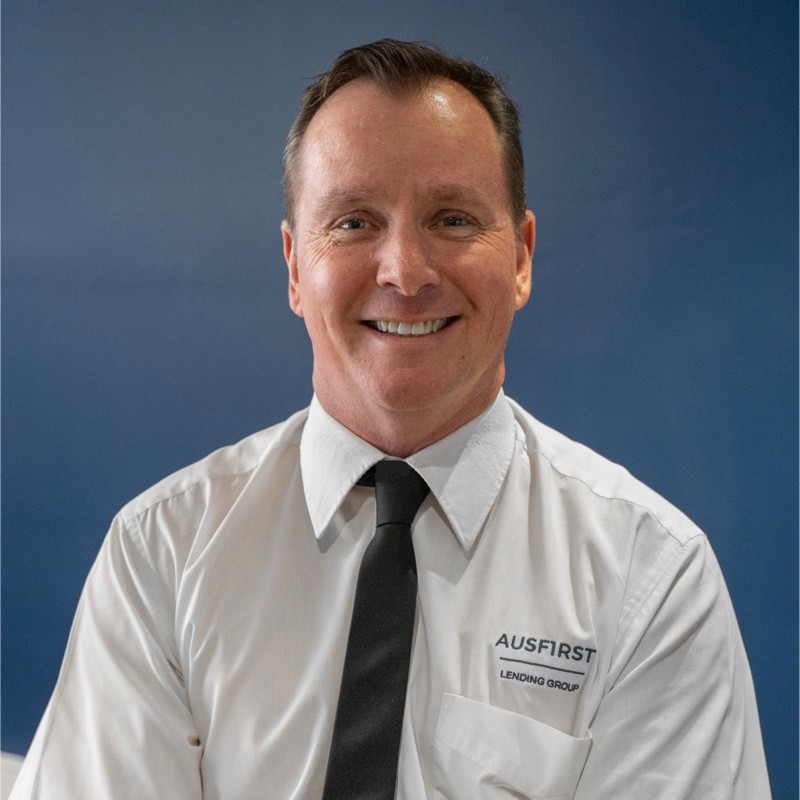
You’re looked after by someone who treats your financial success as his own.
Richard brings more than 30 years of lending experience across Queensland. He takes the time to understand your finances, business objectives and property plans before comparing commercial lenders from our panel.
Whether you’re buying premises, adding offices, warehouses or retail to a portfolio, or refinancing a commercial loan, you get clear advice and the same point of contact from application to settlement.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Thanks to Richard and Debbie and the team at Ausfirst Lending… They are the gurus of self employed loans. I highly recommend their services.”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions we’re asked most about commercial property finance. Every deal is different, so we’re happy to talk through the detail.
Ask about my purchaseMost lenders want 20–30% of the purchase price, depending on the LVR they’ll allow. Higher-risk or specialised properties may need more.
Generally higher than residential rates. They vary with the lender, property type, lease and your risk profile, so we compare current rates across our panel.
Possibly. Some non-bank lenders consider past credit issues, usually with higher rates and stricter conditions.
Not necessarily. Many borrowers are business owners, but investors can also borrow to buy commercial property leased to businesses.
Offices, warehouses, retail shops, industrial properties and mixed-use developments, depending on the lender’s criteria.
Often shorter than home loans, and many are reviewed every few years. Terms vary by lender and property type.
READY TO EXPAND YOUR BUSINESS?
Tell us about the property, the lease and your business. We’ll compare commercial lenders and show which structures and terms could work.
Deposit, LVR and interest cover worked out
Commercial lenders compared
One broker from application to settlement
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, 9 am–5 pm
YOUR COMMERCIAL PROPERTY CHAT
Send our team a little about your plans.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form