Live in your preferred location
Keep the commute, amenities and lifestyle you want without a large mortgage in a high-cost suburb.
LIVE WHERE YOU LOVE, INVEST WHERE IT COUNTS
Rent where you want to live.
Buy where the numbers work.
Rentvesting lets you get into the property market without giving up the suburb you love. We help you work out what you can borrow, compare investment loans from our lender panel and plan for both commitments. Personal guidance from Ausfirst Lending Group’s mortgage brokers in Brisbane and on the Sunshine Coast.
Excellent · 35 Google reviews
WHAT IS RENTVESTING?
You buy an investment property in an area that fits your budget and rent a home where you want to live. For example, you might rent near the Brisbane CBD and buy in a more affordable suburb or regional area with strong rental demand.
Keep the commute, amenities and lifestyle you want without a large mortgage in a high-cost suburb.
Buy in a more affordable area now, rather than saving for years for a home where you live.
Move for work or life changes without the cost and hassle of selling your home.
Weighing rentvesting against buying a home? We’ll compare both paths against your budget and goals.
Start with a free chatHOW WE HELP
Rentvesting means financing an investment property while paying rent. Lenders assess both, so the loan structure needs to work for your cash flow.
We help you weigh interest-only and principal and interest options, offset accounts and split loans against your goals.
We compare investment loans across our panel and explain how each lender treats rental income and your rent.
We test your budget against rate rises and vacancies, so you know your buffer before you buy.
Tax deductions, negative gearing and CGT affect your returns. We can connect you with accountants and advisers.
A QUICK COMPARISON
| What you compare | Buy to live in | Rentvest |
|---|---|---|
| Where you live | Where you can afford | Where you choose |
| First home grants | May be eligible | Generally not eligible |
| Tax deductions | Generally none | On investment costs |
| Moving | Sell or rent out | End your lease |
Which path suits you depends on your finances, goals and lifestyle. Confirm tax outcomes with your accountant.
Compare my optionsKNOW YOUR NUMBERS
As a rentvestor, you pay your own rent and the investment loan at the same time. Rental income can help, but it rarely covers everything once costs are added.
We look at both commitments together and build in a buffer for rate rises, vacancies and repairs.
Illustration only, not a borrowing assessment. Assumes a 30-year principal and interest loan and a rate that stays the same. Excludes LMI, rates, insurance, management fees, vacancies and tax.
Check my actual optionsBEFORE YOU COMMIT
Rentvesting can build wealth, but it comes with trade-offs. Weigh these against your finances, risk tolerance and long-term plans before you buy.
You’ll pay rent on your home and repayments on your investment. If the property sits vacant, you cover the full loan yourself, so a cash buffer is essential.
As a landlord, you also pay for maintenance, council rates and management fees. Property values can fall as well as rise.
Investment properties are usually subject to CGT when sold, which reduces your profit. Exemptions such as the six-year rule generally only apply if you lived in the property first.
Confirm your position with your accountant.
Investment purchases are generally not eligible for first home owner grants or stamp duty concessions, so you may need a larger deposit.
Owning an investment first may also affect your eligibility for first home support later.
We provide credit assistance only. Tax and grant rules change; check current rules with your accountant and the relevant state authority.
Let’s stress-test your plan. We’ll check your budget against rate rises, vacancies and both commitments.
Check my next stepsIS IT RIGHT FOR YOU?
Rentvesting often suits young professionals, investors and people who value flexibility. If stability and making a home your own matter most, buying to live in may suit you better.
You want to stay in a high-cost area for work, family or lifestyle, but can’t yet buy there.
You can comfortably cover rent, loan repayments and property costs, with a buffer left over.
You’re prepared for vacancies, rate rises and property values that can fall as well as rise.
You see the investment as a stepping stone, whether to more property or a future home.
THE RIGHT STRUCTURE MATTERS
The right mix depends on your cash flow, tax position and plans. We help you compare features against your strategy.
Lower repayments for a set term. The balance doesn’t reduce and repayments rise when the term ends.
Higher repayments that reduce your loan balance and build equity over time.
Fix part of the loan for certainty and keep the rest variable for flexibility.
Reduce the balance used to calculate interest while keeping your buffer accessible.
Planning to buy your own home later? We’ll structure the investment loan with that next step in mind.
Talk about my plansFROM FIRST CHAT TO SETTLEMENT
We explain each stage, prepare the application with you and keep you informed through to settlement and beyond.
UNDERSTAND
Meet by phone, Zoom or in person. Tell us where you want to live, where you’re looking to buy and your timeline.
GATHER
We collect income documents, savings and debt details, and factor in your rent and living costs.
ANALYSE & PLAN
We compare lenders and loan structures and check your cash flow against both commitments.
APPLY
Once you’ve found a property, we finalise the application and liaise with the lender on valuation and approval.
FINALISE
We coordinate with your lender and conveyancer and keep you informed through to settlement.
SUPPORT
We review your loan as rates, values and your goals change, including when you’re ready for the next step.
WHAT MAKES AUSFIRST DIFFERENT
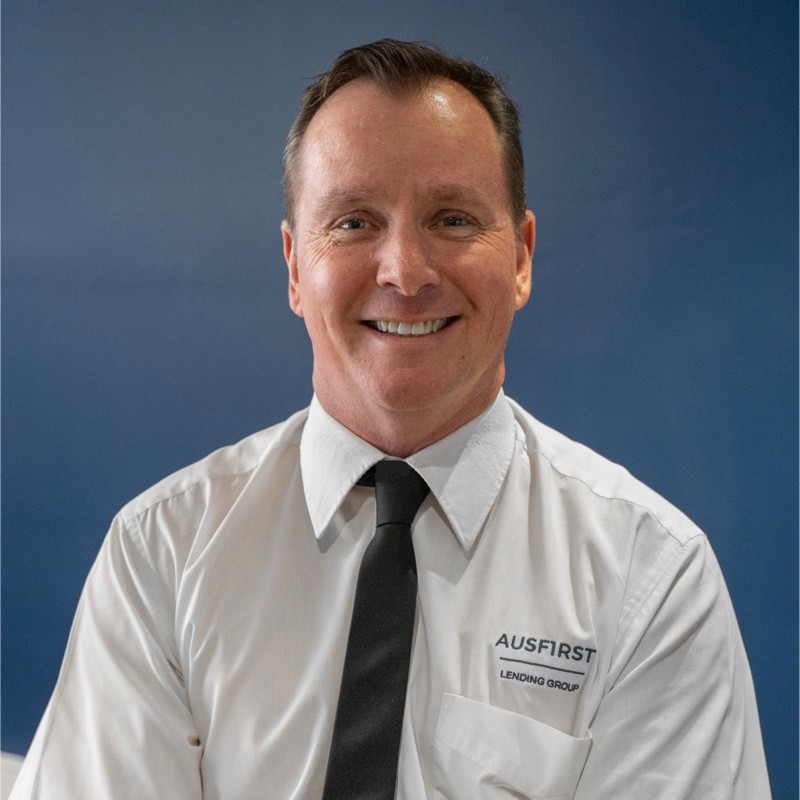
You’re looked after by someone who treats your financial success as his own.
Richard brings more than 30 years of hands-on broking experience. He takes the time to understand your finances, lifestyle and investment goals before comparing options from our panel.
Whether it’s your first investment while you rent or the next step in a growing portfolio, you get clear advice, regular updates and the same team from application to settlement.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Debbie made the process of buying a new house frictionless, by providing excellent support throughout”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions we’re asked most about rentvesting. Your circumstances matter, so we’re happy to talk through the detail.
Ask about my situationYou buy an investment property in an area that fits your budget and rent a home where you want to live. Rent from the investment can help with repayments and costs, though outcomes depend on the market and your circumstances.
It can be a way into the market while keeping lifestyle flexibility. Whether it suits you depends on your finances, goals and appetite for risk.
Neither is better for everyone. Rentvesting offers flexibility and an earlier start in the market. Buying to live in offers stability and the chance to make a home your own.
Yes, some lenders accept smaller deposits for investment loans. A 20% deposit generally avoids LMI and lowers borrowing costs. We compare options that fit your budget.
Generally, no. Investment purchases aren’t eligible for first home owner grants. Owning an investment property may also affect your eligibility for first home support later, so check the rules before you buy.
Investment property costs such as interest, depreciation, maintenance and management fees may be deductible. Negative gearing may apply if expenses exceed rent. Speak with a tax professional about your situation.
Vacancies hit your cash flow, so keep a buffer to cover repayments and costs. Buying in an area with strong rental demand can reduce the risk.
LET’S MAKE A START
You don’t need a property picked out. Tell us where you live, where you’re thinking of buying and your goals, and we’ll help you understand your options.
A clear look at your borrowing capacity
Cash flow tested against both commitments
Personal guidance from an experienced team
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, 9 am–5 pm
YOUR FREE RENTVESTING CHAT
Send our team a little about where you’re at.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form