Buy before you sell
Act quickly on the right property without waiting for your current home to sell.
BUY BEFORE YOU SELL
Found your next home?
Don’t wait for the sale.
A bridging loan lets you buy your next property before selling your current one. No rushed sale, no moving twice. We compare bridging finance across our lender panel, including rates, fees and early repayment terms. Personal guidance from Ausfirst Lending Group’s mortgage brokers in Caloundra, Brisbane and the Sunshine Coast.
Excellent · 35 Google reviews
ONE MOVE, NOT TWO
A quick look at how bridging finance closes the gap between homes.
We model your peak and end debt with a realistic sale price, compare bridging lenders and repayment options, and coordinate the timing between buying and selling.
Upsizing, downsizing or relocating, we’ll check whether bridging suits your equity and timeline before you commit.
HOW BRIDGING LOANS WORK
A bridging (or relocation) loan is short-term finance secured against your current home’s equity. Your existing loan and new purchase combine into “peak debt” until your sale settles, usually within 6 to 12 months.
Act quickly on the right property without waiting for your current home to sell.
Go straight to your new home without temporary rentals or moving twice.
Take time to find the right buyer instead of accepting a rushed offer.
Upsizing, downsizing or relocating? We’ll check whether bridging suits your timeline and equity.
Start with a free chatTYPES OF BRIDGING LOANS
The right bridging loan depends on whether you’ve sold yet and how you want to handle interest during the bridging period.
You’ve sold and have a confirmed settlement date. Lower risk for lenders, often with better terms.
You haven’t sold yet. Expect stricter criteria, possibly higher rates and the need for substantial equity and a clear sale plan.
Pay just the interest during the bridging period to ease cash flow until the sale settles.
Some lenders add interest to the balance instead of monthly repayments, paid when your home sells.
A QUICK COMPARISON
| What you compare | Open | Closed |
|---|---|---|
| Buyer secured | Not yet | Yes, with a settlement date |
| Lender risk | Higher | Lower |
| Typical terms | Stricter | More favourable |
| Timeframe | Usually up to 12 months | Set by settlement |
Terms, rates and maximum bridging periods vary by lender and can change.
Compare my bridging optionsKNOW YOUR NUMBERS
Peak debt is your current loan plus your new purchase. End debt is what’s left once your home sells. Most lenders want peak debt within about 80% of both properties’ combined value.
We model both figures, including interest that builds during the bridging period, before you commit.
Illustration only, not a borrowing assessment. Assumes interest is capitalised monthly for the full period. Excludes stamp duty, agent fees, valuations and other costs. Lender valuations may differ from prices entered.
Check my actual optionsBEFORE YOU COMMIT
Bridging finance is convenient, but it costs more than a standard home loan and depends on your sale going to plan. We help you prepare for both.

Bridging rates are often higher than standard home loans. When interest is capitalised, it’s added to your balance each month, so a slow sale increases your end debt.
You’ll also pay for valuations on both properties, plus the usual buying and selling costs.
If your home sells below expectations, the proceeds may not cover as much of the peak debt, leaving a larger end loan than planned.
We use a realistic price in your numbers.
Most bridging loans must be repaid within 6 to 12 months. Extensions aren’t guaranteed, and you may need to start principal and interest repayments or reduce your price.
We help you plan a backup.
Rates, fees and bridging periods vary by lender and can change. Confirm current terms before applying.
Let’s pressure-test your plan. We’ll model your peak and end debt with a realistic sale price and timeline.
Check my next stepsBEFORE YOU APPLY
Lenders also want a clear repayment strategy, such as savings or other income, in case your sale takes longer than expected.
Often around 50% or more in your current home, acting as security for the loan.
Proof your home is on the market, or an unconditional sale contract.
Income, expenses and credit history showing you can manage the bridging period.
Usually a maximum of around 80% LVR across both properties.
THE RIGHT STRUCTURE MATTERS
Bridging isn’t only for buying before you sell. We help you choose the structure that fits your timeline.
Secure your next home and sell your current one in your own time.
Fund upgrades that may lift your sale price, while still living in your home.
Buy your next home first, then sell and potentially clear your debt.
Once sold, any remaining balance becomes a standard home loan with its own features.
Building a new home while you sell? Construction and bridging finance can work together.
Talk about my plansFROM FIRST CHAT TO SETTLEMENT
We explain each stage, coordinate both settlements and keep you informed until your end loan is in place.
UNDERSTAND
Meet by phone, Zoom or in person. Tell us about both properties and your timeline.
GATHER
We collect income documents, loan details and your sale agreement or listing.
ANALYSE & PLAN
We compare bridging lenders, rates and repayment options using a realistic sale price.
APPLY
We submit your application and arrange valuations on both properties.
FINALISE
We coordinate settlement on your new home and keep you informed throughout.
SUPPORT
When your home sells, the proceeds reduce your peak debt and your end loan begins.
WHAT MAKES AUSFIRST DIFFERENT
You’re looked after by someone who treats your financial success as his own.
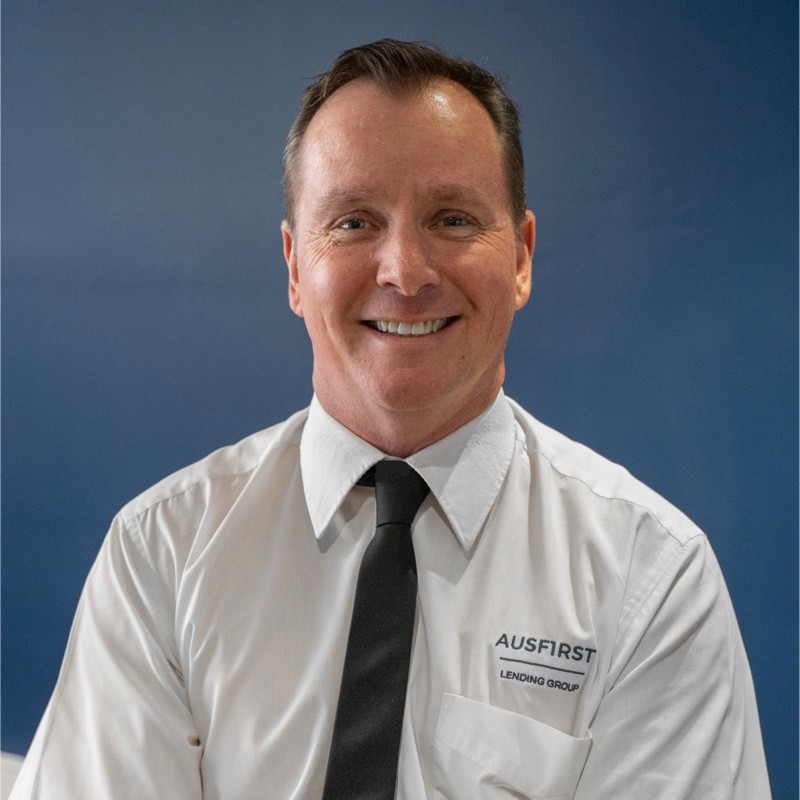
Richard brings more than 30 years of hands-on broking experience. He takes the time to understand your finances, timeline and plans before comparing bridging options from our panel.
Whether you’re upgrading, downsizing or relocating, you get clear advice on repayment options, regular updates and the same team through both settlements.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Debbie made the process of buying a new house frictionless, by providing excellent support throughout”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions we’re asked most about bridging finance. Your circumstances matter, so we’re happy to talk through the detail.
Ask about my moveIt’s a short-term loan that lets you buy before you sell, secured against your current home’s equity. Your existing loan and new purchase combine into peak debt, which is reduced when your sale settles, usually within 6 to 12 months.
It depends on the lender, rate and LVR. Rates are usually higher than standard home loans, and valuation fees apply on both properties. The longer your sale takes, the more interest you pay.
Many lenders look for around 50% equity in your current home. More equity can help you access better terms.
You may be able to request an extension, though it’s not guaranteed. Some lenders require principal and interest repayments on the peak debt. Without an extension, you may need to reduce your price, so a backup plan matters.
Yes. Many bridging loans allow interest-only repayments, and some allow extra repayments to reduce peak debt. Others capitalise the interest instead. We’ll explain the options each lender offers.
Yes. Some borrowers use bridging finance to fund upgrades that may lift their sale price, without having to move out during the work.
Our home loan broker service, including bridging finance, is free for you. Lenders pay us a commission, which we disclose. Lender fees, valuations and other costs are separate.
Several major banks and some smaller lenders offer bridging finance, with different terms, rates and LVR limits. We compare current options across our panel.
LET’S MAKE A START
Tell us about your current home and the one you’d like to buy. We’ll model your peak and end debt and explain your bridging options.
Peak and end debt worked out
Bridging lenders and repayment options compared
Personal guidance from an experienced team
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, 9 am–5 pm
YOUR FREE BRIDGING CHAT
Send our team a little about your plans.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form