LMI waivers
Borrow up to 90% of the property value without LMI, with eligible lenders.
FOR OPTOMETRISTS
You look after vision.
We’ll look after your loan.
Some lenders include optometrists in their health professional policies, with LMI waivers up to 90% LVR and professional pricing. We compare those policies across our lender panel, whether you’re employed, a practice partner or running your own practice. Personal guidance from Ausfirst Lending Group, based in Caloundra.
Excellent · 35 Google reviews
WHAT OPTOMETRISTS MAY ACCESS
Some lenders offer packages for health professionals, assessed case by case. If you’ve struggled with a bank before, a lender with a health professional policy may see your application differently.
Borrow up to 90% of the property value without LMI, with eligible lenders.
Rate discounts, fee waivers or dedicated lending teams, depending on the lender.
Salaried, partner and practice-owner income, matched to lender policy.
Early in your career? A waiver could help you buy sooner with a smaller deposit and lower upfront costs.
Start with a free chatWHAT LENDERS LOOK AT
LMI usually applies above 80% LVR. Lenders that list optometrists may waive it up to 90%, depending on their criteria.
Current registration as an optometrist through AHPRA.
Your time in practice and employment stability.
Some lenders set a minimum income for the waiver.
Waivers often cap the loan size, which varies by lender.
AN EXAMPLE
| What you compare | Standard loan | With waiver |
|---|---|---|
| Deposit | $90,000 | $90,000 |
| Loan | $810,000 | $810,000 |
| LMI | Usually payable | Waived if eligible |
| Eligibility | Standard | Registration and lender limits |
LMI is paid upfront or added to the loan; its cost depends on loan size, LVR and lender. Waiver policies vary and can change.
Check my eligibilityKNOW YOUR NUMBERS
A 10% deposit without LMI means less time saving and more cash left for furniture, a buffer or your practice.
We check which lenders include optometrists in their waiver policies and whether their loan limits fit your purchase.
Illustration only, not a borrowing assessment. Excludes stamp duty and buying costs. Eligibility, waiver LVRs and loan limits vary by lender.
Check my actual optionsHOW YOU EARN
How you’re paid shapes which lenders and documents suit you. We match your income structure to lender policy.
Many optometrists balance a salaried role with practice ownership, or hold a partnership in a joint-venture or franchise practice. That income is usually assessed as self-employed.
Practice owners and partners are usually assessed on one to two years of tax returns and business financials.
Payslips, with some lenders accepting a shorter employment history for registered professionals, including recent graduates.
A family guarantee, a low deposit loan or a standard loan with LMI may still help you buy sooner.
Lender policies on health professional waivers and income vary and can change.
Let’s check your eligibility. We’ll match your registration and income to lenders whose policies fit.
Check my next stepsDOCUMENTS TO PREPARE
Preparing these in advance helps your application move quickly.
Passport or driver’s licence.
Payslips, or tax returns if you’re a partner or owner.
Evidence of your current optometry registration.
Bank statements, and current loan statements if refinancing.
LOAN FEATURES
Loans with waived LMI often still include standard features, depending on the lender.
Balance repayment certainty with flexibility.
Reduce interest while keeping funds accessible.
Withdraw extra repayments when you need them.
Lower repayments for a set term, often for investments.
Not an optometrist? Many other health professionals may qualify for LMI waivers.
Explore LMI waived loansFROM FIRST CHAT TO SETTLEMENT
We guide you through each step, so you can keep focusing on your patients.
UNDERSTAND
By phone, Zoom or in person. Your plans, income and registration.
GATHER
Income, registration details and statements.
ANALYSE & PLAN
Waivers, loan limits and packages across our panel.
APPLY
We present your income and registration to fit lender policy.
FINALISE
We coordinate settlement and keep you informed.
SUPPORT
We review your rate and options as your career grows.
WHAT MAKES AUSFIRST DIFFERENT
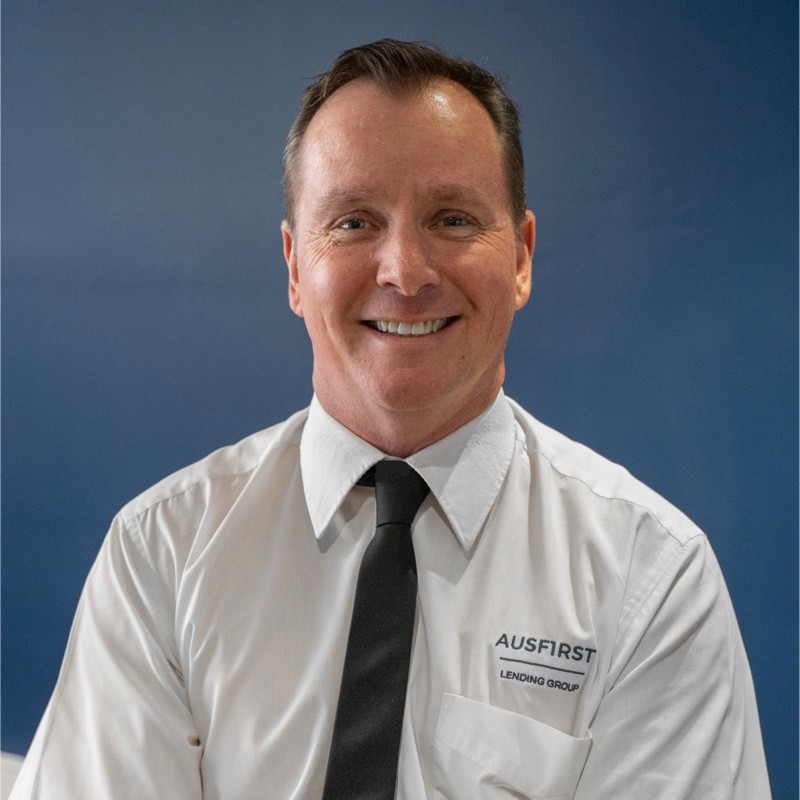
You’re looked after by someone who treats your financial success as his own.
Richard brings more than 30 years of hands-on broking experience. He takes the time to understand your profession, income structure and long-term goals before comparing options from our panel.
Whether you’re buying your first home, refinancing or growing a portfolio, you get clear advice, regular updates and support through to settlement.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Debbie made the process of buying a new house frictionless, by providing excellent support throughout”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions optometrists ask us most. Your circumstances matter, so we’re happy to talk through the detail.
Ask a questionSome lenders include optometrists in their health professional policies and may waive LMI up to 90% LVR. Eligibility is assessed case by case.
Usually, yes. Lenders generally want current registration as an optometrist before applying a professional waiver.
It depends on the lender. Some set a minimum income for the waiver, while others focus on registration and stability.
Often, yes. Partners and owners usually need one to two years of tax returns and business financials, and lender policies vary.
You may still buy with a family guarantee, a low deposit loan with LMI, or by saving towards 20%. We’ll compare the options.
Some lenders allow it, while others limit waivers to owner-occupied homes. We’ll check which lenders suit your plans.
WE’RE HERE TO HELP
Whether you’re early in your career or have practised for years, we’ll show you which lending pathways reflect your professional standing.
LMI waiver eligibility checked
Professional packages compared
Personal guidance from an experienced team
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, 9 am–5 pm
YOUR FREE CHAT
Send our team a little about your situation.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form