Funds in stages
Drawdowns against each milestone, not one lump sum upfront.
CONSTRUCTION HOME LOANS
Funds released in stages.
Valued on the finished home.
Whether it’s your first home, a knockdown rebuild, an investment or a major renovation, a construction loan releases funds as your build progresses, and the lender values it on the completed home. We compare 40+ lenders on your build and site, then manage the draws, valuations and builder paperwork so the money is there at each stage. Personal guidance from Ausfirst Lending Group in Caloundra.
Excellent · 35 Google reviews
NOT A STANDARD HOME LOAN
It draws down in stages as your build hits milestones, and the lender assesses it on the completed home, not the land or today’s spend. That changes what you provide, how the valuation works and how your cash flow runs during the build.
Drawdowns against each milestone, not one lump sum upfront.
Matched to who lends comfortably on your build type and site.
The same person from first plans to final completion.
Get the structure right upfront. It’s what keeps the money flowing when the builder invoices.
Start with a free chatHOW CONSTRUCTION LOANS WORK
What lenders assess, and how the money is released.
Sometimes up to 95%. Eligible first home buyers may build with 5% under a government scheme.
Lenders use the lower of land plus build cost, or the valuer’s completed estimate.
Commonly around 24 months to draw all funds. Vacant land may need a land loan first.
Some lenders consider projected rent as part of the assessment.
AN EXAMPLE
| Item | Amount |
|---|---|
| Land | $350,000 |
| Build contract | $450,000 |
| Valuer’s completed estimate | $780,000 |
| Value the lender uses | $780,000 (the lower) |
Illustrative. A valuation below cost means you contribute more.
Check my numbersKNOW YOUR NUMBERS
If the valuer’s completed estimate comes in below your land and build cost, the lender lends against the lower figure, and you cover the gap.
We check this before you sign, so the shortfall doesn’t surprise you at the frame stage.
Illustration only, not a borrowing assessment. Excludes stamp duty, fees, LMI and variations. Lender policies on LVR and valuation vary.
Check my actual optionsCOMPLETION AND CONVERSION
When the build is complete, the loan usually converts to a standard home loan. The lender may ask for final documents and a last inspection.
Note any outstanding work before the final payment is released. It can help avoid disputes after handover.
We coordinate the final inspection and paperwork with your lender.
First home schemes and grants can make a new build achievable with a smaller deposit.
See low deposit optionsBuilding it yourself narrows the lender choice and usually needs a bigger deposit.
Drawdown periods, LVRs and valuation methods vary by lender.
Let’s match your build to the right lender. Rather than finding out at the frame stage that it doesn’t suit.
Check my next stepsTHE PROGRESS-PAYMENT STAGES
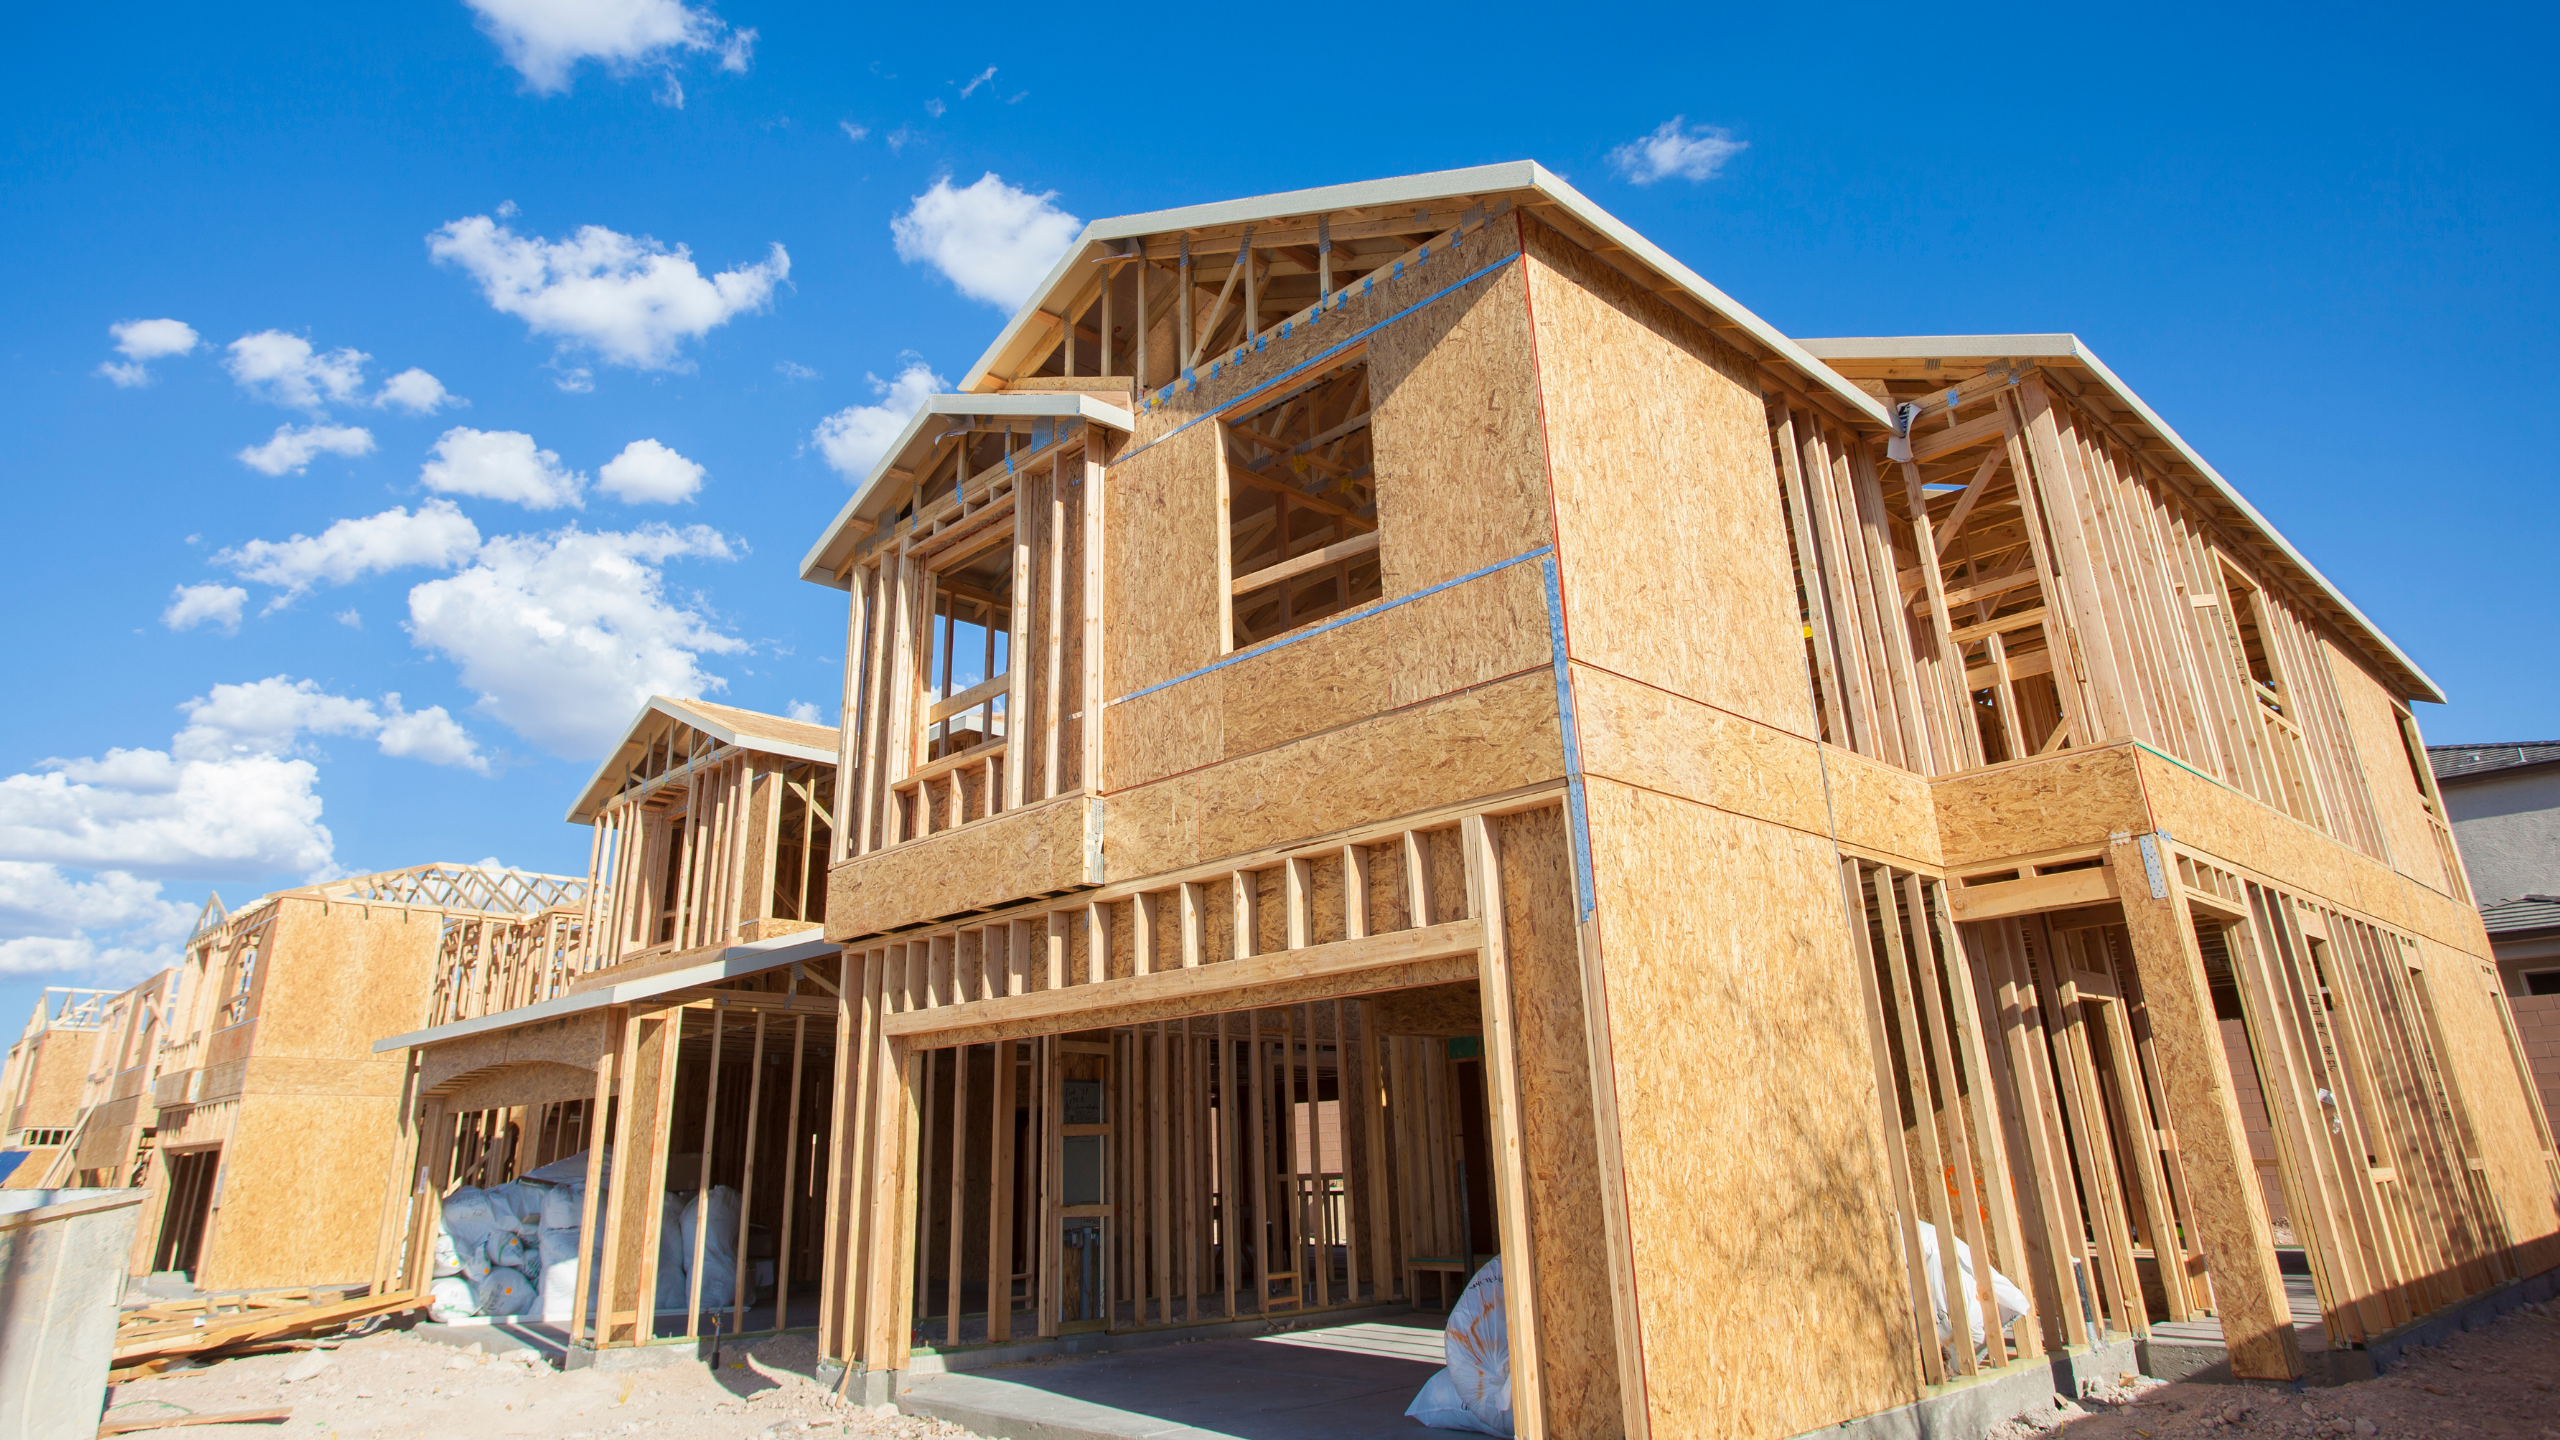
Your loan is released in stages aligned to construction milestones. The lender may inspect before releasing the next payment.
PREPARATION
The initial funds to get the build under way.
BASE
The foundation is laid.
FRAME
The frame of the home goes up.
LOCK-UP
Walls, windows and roof go on.
FIT-OUT
Cabinetry, fixtures and fittings are installed.
COMPLETION
Final works finished and keys handed over.
WHAT LENDERS LOOK FOR
Accurate documentation, prepared upfront, keeps the process and the draws moving.
Consistent income, savings history and good credit conduct.
Fixed-price contract, detailed plans, builder’s licence and budget.
An independent valuation of the finished home.
Your records and the builder’s documents ready upfront.
WHY BUILD WITH AUSFIRST
Construction lending has more moving parts than a standard loan.
Policies on draws, valuations and sites vary widely.
Progress payments, valuations and builder paperwork.
You work directly with Richard Luke, start to finish.
Lenders pay us on settlement. We disclose any fees upfront.
A major renovation can be funded on a similar staged basis.
Explore renovation loans
WHAT MAKES AUSFIRST DIFFERENT
You’re looked after by someone who treats your financial success as his own.
You deal directly with Richard, the founder, who brings over 30 years of lending experience across Queensland. He personally oversees every client’s loan.
You’re not passed between departments: one person from first plans to completion.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Debbie made the process of buying a new house frictionless, by providing excellent support throughout”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions we’re asked most about funding a build. Every project is different, so we’re happy to talk through the detail.
Ask about my buildOn the completed home. Lenders usually use the lower of land plus build cost, or the valuer’s completed estimate.
Some lenders go up to 95% LVR. Eligible first home buyers may build with 5% under a government scheme.
Commonly around 24 months, though it varies by lender. Delays beyond that may need an extension.
If you’re buying vacant land to build later, often yes. We can structure the land and construction loans together.
Some lenders consider projected rental income as part of the assessment.
The loan usually converts to a standard home loan after a final inspection and documents.
START WITH A CONVERSATION
Tell us about the land, the builder and the budget. We’ll show you how to structure the finance and which lenders suit it.
Valuation shortfall checked upfront
Progress draws managed
Direct access to Richard
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, and by appointment
YOUR FREE CONSULTATION
The land, the builder and the budget.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form