LMI waivers
Borrow up to 90% of the property value without paying LMI, with eligible lenders.
FOR ACCOUNTING PROFESSIONALS
You know the numbers.
We know the lender policies.
Some lenders offer CPA, CA and IPA members LMI waivers up to 90% LVR, plus pricing discounts and flexible income assessment. We compare those policies across our lender panel and structure your application to fit, whether you’re employed, a partner or self-employed. Personal guidance from Ausfirst Lending Group, based in Caloundra.
Excellent · 35 Google reviews
WHAT ACCOUNTANTS MAY ACCESS
Lenders see qualified accountants as lower-risk borrowers, with steady careers, strong incomes and financial literacy. Some reward that with policies most borrowers can’t access.
Borrow up to 90% of the property value without paying LMI, with eligible lenders.
Rate discounts, annual fee rebates or cashback, depending on the lender and product.
Salary, bonuses, partnership drawings and self-employed income, assessed to lender policy.
Your spouse is the accountant? Some lenders extend accountant policies to joint applications.
Start with a free chatHOW TO QUALIFY
LMI usually applies above 80% LVR. Eligible accountants may avoid it up to 90%, depending on the lender’s criteria.
Hold a CPA, CA or IPA qualification.
Be currently registered with a recognised accounting body.
Some lenders set a minimum income; others don’t.
Waivers often have a maximum loan size, which varies by lender.
AN EXAMPLE
| What you compare | Standard loan | With waiver |
|---|---|---|
| Deposit | $195,000 | $195,000 |
| LVR | 90% | 90% |
| LMI | Usually payable | Waived if eligible |
| Eligibility | Standard | Qualification and lender limits |
Waiver policies, loan limits and eligibility vary by lender and can change.
Check my eligibilityKNOW YOUR NUMBERS
Buying with a 10% deposit instead of 20%, without LMI, leaves more cash for your next investment, an offset account or a buffer.
We check which lenders’ waivers you qualify for and whether their loan limits fit your purchase.
Illustration only, not a borrowing assessment. Excludes stamp duty and buying costs. Eligibility, waiver LVRs and loan limits vary by lender.
Check my actual optionsWHO MAY QUALIFY
Eligibility usually depends on your qualification and membership, not just your job title. Not all accountants will qualify, and policies vary.
Assurance, tax, financial, management, forensic, public and government accounting, internal audit, insolvency, corporate finance and treasury, commercial finance and risk assessment.
Not listed? Speak with us, as you may still be eligible.
PAYG salary, casual income (often after six months), bonuses and allowances, and self-employed income, usually with one to two years of returns.
A few lenders may lend up to 90% with a waiver, plus a second loan for costs, often at a higher rate. These are uncommon and have strict criteria.
Lender policies on accountant waivers, income and high-LVR lending vary and can change.
Let’s check your eligibility. We’ll match your qualification and income to lenders whose policies fit.
Check my next stepsCLIENT SCENARIOS
Three examples of how accountants have used lender policies to reach their goals. Every situation is different.
Newly CA-qualified, Emma wanted her first investment property without spending all her savings.
A smaller deposit left more savings for her next purchase.
Tony’s bank wouldn’t match rates offered to new customers across his investment properties.
Improved cash flow supported his broader investment strategy.
Nick and his partner’s bank approval fell short for the family home they wanted.
Reducing card limits, updating bonus income and changing lenders closed the gap.
Scenarios are illustrative. Outcomes depend on your circumstances and lender assessment.
DOCUMENTS TO PREPARE
Preparing these in advance helps your application move quickly.
Passport or driver’s licence, plus secondary documents if needed.
Two recent payslips, or one to two years of tax returns if self-employed.
Evidence of your current CPA, CA or IPA membership.
Bank statements, and current loan statements if refinancing.
LOAN FEATURES
Depending on the lender and product, you can combine these to match your plans.
Balance repayment certainty with flexibility.
Reduce interest while keeping funds accessible.
Withdraw extra repayments when you need them.
Lower repayments for a set term, often for investments.
Not an accountant? See which other professions may qualify for LMI waivers.
Explore LMI waived loansFROM FIRST CHAT TO SETTLEMENT
Let us handle the comparison work while you focus on your priorities.
UNDERSTAND
By phone, Zoom or in person. Your plans, income and qualification.
GATHER
Income, membership proof and statements.
ANALYSE & PLAN
Waivers, loan limits, pricing and offers across our panel.
APPLY
We present your income and qualification to fit lender policy.
FINALISE
We coordinate settlement and keep you informed.
SUPPORT
We review your rate and options as your career and goals change.
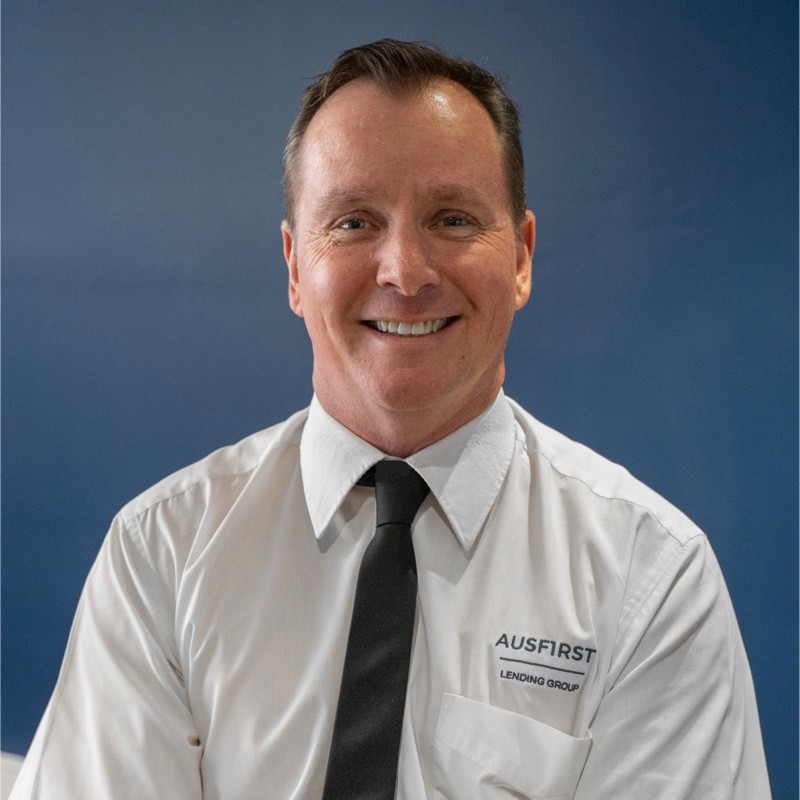
WHAT MAKES AUSFIRST DIFFERENT
You’re looked after by someone who treats your financial success as his own.
When you choose Ausfirst, you deal directly with Richard, the founder, who brings over 30 years of lending experience across Queensland.
He understands accountants’ financial profiles, whether you’re employed, self-employed, a partner in a firm or managing several income streams, and tailors your application to lender policy.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Debbie made the process of buying a new house frictionless, by providing excellent support throughout”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions accountants ask us most. Every situation is different, so we’re happy to talk through the detail.
Ask a questionSome lenders waive LMI up to 90% LVR for CPA, CA or IPA members. Income minimums and loan limits vary by lender.
Possibly. Some lenders extend accountant policies to joint applicants when one borrower qualifies. Eligibility depends on the lender.
In limited cases. A few lenders may combine a 90% loan with a waiver and a second loan for costs, often at a higher rate. It’s uncommon and has strict criteria.
For most waiver policies, yes. Lenders usually want current CPA, CA or IPA membership, not just an accounting degree.
Yes. We work with partners, contractors, self-employed accountants and those with bonuses or several income streams, matching each to lender policy.
As soon as you’re ready to share your details. We can usually outline your options shortly after reviewing your documents.
LET’S EXPLORE WHAT’S POSSIBLE
Whether you’re buying your first home, refinancing or planning your next investment, we’ll show you which professional loan options may be available to you.
LMI waiver eligibility checked
Professional pricing compared
Direct access to Richard
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, 9 am–5 pm
YOUR FREE CHAT
Send our team a little about your situation.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form