Buy years sooner
Get into the market without saving a full 20% deposit first.
BRIDGE THE DEPOSIT GAP
Stuck in the rent cycle?
Buy sooner with backing.
Saving 20% while renting can take years. A guarantor home loan lets a family member back your loan with equity in their home, so you may need little or no deposit and could avoid LMI. We explain how it works for both of you and find lenders that fit. Personal guidance from Ausfirst Lending Group’s mortgage brokers in Brisbane and on the Sunshine Coast.
Excellent · 35 Google reviews
WHY FIRST HOME BUYERS CHOOSE THIS
Rent keeps eating into your savings while prices move. With a guarantor’s equity filling the deposit gap, you could buy with 5% down, or sometimes nothing at all, as long as you can afford the repayments.
Get into the market without saving a full 20% deposit first.
LMI can cost tens of thousands. A guarantee often means you avoid it.
Extra security may help you borrow enough for the area you want to live in.
Your guarantor doesn’t hand over cash. They let the lender use part of their home’s equity as extra security for your loan.
Start with a free chatTHE SETUP IN PLAIN ENGLISH
Someone you trust, usually a parent, backs part of your loan with their property. You’re still the borrower and make every repayment.
Part of your guarantor’s home equity is used as security alongside your new property.
Most lenders want a parent, grandparent or sibling. Some accept other relatives.
Some lenders approve up to 100% of the price when a guarantee covers the gap.
You make the repayments. Your guarantor only covers the guaranteed portion if you can’t.
A QUICK COMPARISON
| Responsibility | You | Your guarantor |
|---|---|---|
| Makes repayments | Yes, every one | Only if you can’t |
| Property | The one you’re buying | Their home, as extra security |
| Legal advice | Recommended | Required by lenders |
| Credit file | Your new loan | The guarantee is recorded |
Guarantor rules, limits and requirements vary between lenders.
Talk through our situationGETTING YOUR GUARANTOR OFF THE HOOK
Your guarantor isn’t attached forever. Once repayments and price growth bring your loan to around 80% of your home’s value, you can usually apply to release them.
That normally means an internal refinance, with a new valuation, credit check and income review. Discharge, valuation or admin fees may apply.
Illustration only. Assumes a 30-year principal and interest loan, a steady rate and the growth rate chosen. Property values can fall as well as rise. Lender valuations may differ.
Check my actual optionsTHE RISKS TOO
Guarantor loans aren’t without downsides. Both you and your guarantor need to understand them before anyone signs.
If you can’t repay, your guarantor must step in. In a worst case, they could be forced to sell their home to cover the guaranteed amount.
The guarantee also limits their own borrowing for renovating or investing, and it appears on their credit file.
Money and family don’t always mix. Talk through expectations, risks and what happens if things don’t go to plan, before anyone signs.
Lenders insist your guarantor gets independent legal and financial advice first. No one can be pressured into it.
Guarantee limits, release rules and lender policies vary and can change.
Let’s talk it through together. We’re happy to meet with you and your guarantor so everyone understands the commitment.
Book a chatWHAT LENDERS WANT FROM YOU
Lenders assess you on your own merits, as well as your guarantor.
Consistent income and work history to afford the repayments.
Many lenders like to see a small deposit or genuine savings.
Usually a first home, though some lenders allow investment property.
Lenders check its type, condition and how easily it would sell.
WHO CAN BE YOUR GUARANTOR?
Lenders are specific about who qualifies. Age isn’t necessarily a dealbreaker, though older guarantors may face more questions about retirement plans.
Parents most often, with siblings and grandparents usually accepted too.
A home in Australia with enough equity to offer as security.
Income, assets, debts and credit history that could handle the responsibility.
Formal documents signed after legal advice, with no pressure.
Want the full detail on how guarantor equity is calculated? See our family guarantee guide.
Explore family guaranteesFROM RENTING TO OWNING
We guide you and your guarantor through each stage, then help you release the guarantee when the time comes.
UNDERSTAND
Your income, savings and the home you’re aiming for, and who might guarantee.
CHECK
We estimate their equity and check they’re likely to meet lender rules.
COMPARE
We compare lenders that offer guarantor loans and their limits.
ADVICE
Your guarantor receives independent legal and financial advice.
SETTLE
We coordinate both parties’ documents through to settlement.
RELEASE
When you reach around 80% LVR, we help you refinance and release your guarantor.
WHY WORK WITH AUSFIRST LENDING GROUP
We’re legally required to act in your best interests, and we want to see you succeed.
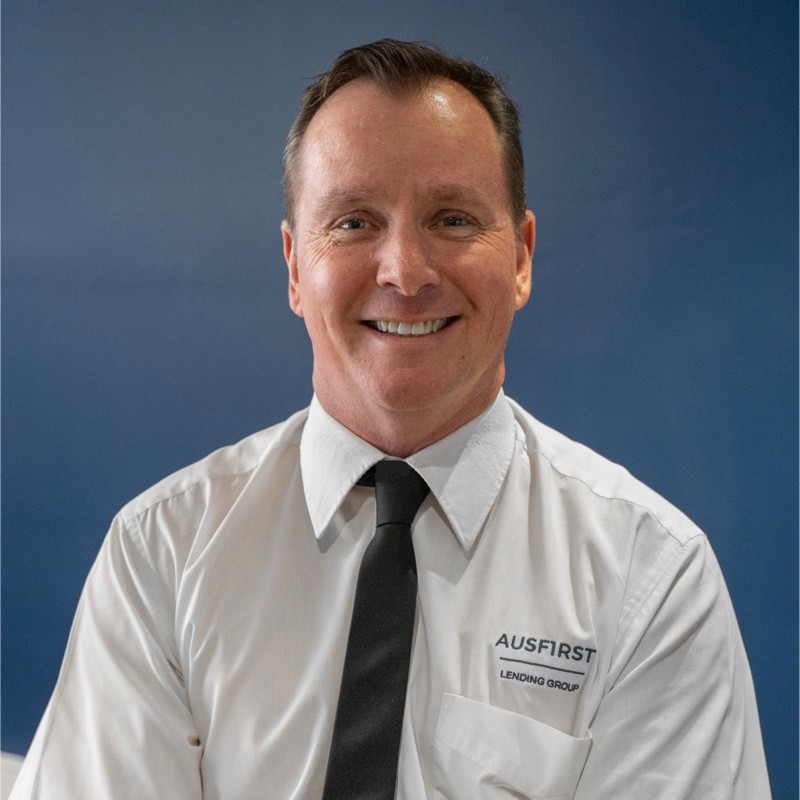
Richard brings more than 30 years of hands-on broking experience. From the first conversation to settlement, we assess your borrowing power, organise the paperwork and negotiate with lenders, so you can focus on finding your home.
We compare a wide range of lenders, not just one bank, to find better rates, more flexible terms or specialised products you might not know exist.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Debbie made the process of buying a new house frictionless, by providing excellent support throughout”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions first home buyers and their families ask most. We’re happy to talk them through with both of you.
Ask a questionSome lenders approve up to 100% of the purchase price with a guarantee. You still need to afford the repayments, and many lenders like to see some genuine savings.
Not unless you can’t make your repayments. Then they’re responsible for the guaranteed portion, which could ultimately mean selling their home.
Until your loan reaches around 80% of your property’s value, through repayments or growth. That can take a few years, depending on the market and how fast you pay down your loan.
Usually through an internal refinance, with a new valuation, credit check and income review to confirm you can manage alone. Discharge, valuation or admin fees may apply.
Most are for first homes, but some lenders allow investment purchases. We’ll check which lenders suit your plans.
Yes, the terms are used interchangeably. Our family guarantee page goes deeper into how guarantor equity is assessed.
Read about family guaranteesREADY TO EXPLORE YOUR OPTIONS?
We take the time to understand your situation, explain your options clearly and connect you with lenders that suit you and your guarantor.
Your options with a guarantor explained
Lenders that offer guarantor loans compared
A plan to release your guarantor later
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, 9 am–5 pm
YOUR FREE GUARANTOR CHAT
Send our team a little about you and your potential guarantor.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form