Review the fund
We look at the financial position, available deposit, contributions, liquidity and other information relevant to lender assessment.
SMSF LENDING
Borrowing through a self-managed super fund can involve more moving parts than a standard property loan. The fund, proposed property, borrowing structure and lender policy all need to work together before an application goes in.
We help Sunshine Coast trustees understand the lending requirements, compare relevant lender policies and manage the finance application through to settlement. As a mortgage broker in Caloundra, we can support local clients by phone, online or in person at our Bulcock Street office where appropriate.
We look at the financial position, available deposit, contributions, liquidity and other information relevant to lender assessment.
Property type, use, valuation and lender security requirements can influence which finance options may be available.
Different SMSF lenders can take different views of the same proposal, so lender selection can matter.
The Sunshine Coast page is different from a purely remote lending service because Ausfirst is actually based here. Our office is at Suite 3/74 Bulcock Street, Caloundra QLD 4551, giving local trustees and business owners the option of speaking with the team in person where an appointment is suitable.
Phone and online meetings are also available, which can be useful when several people are involved in the transaction. An SMSF property loan may require input from your broker, accountant, solicitor, financial adviser or SMSF administrator, and those professionals do not necessarily need to be in the same location.
Our role is the lending. We can explain how lenders may assess the SMSF, proposed property and borrowing requirement, identify likely documentation and compare finance options. Decisions about establishing an SMSF, investment strategy, taxation or legal structure should be made with appropriately qualified professionals.
Borrowers comparing SMSF loans across Queensland may also need to consider lender policy, servicing, liquidity and documentation requirements.
SMSFs are restricted in the circumstances in which they can borrow. Where the legislative requirements are satisfied, borrowing may take place through a Limited Recourse Borrowing Arrangement, commonly shortened to LRBA.
Under an LRBA, borrowed money is used to acquire a permitted asset that is held on trust so the SMSF acquires a beneficial interest, subject to the statutory requirements. The SMSF must also have the right to acquire legal ownership after making the required payments. The lender's recourse in relation to the borrowing is limited in the manner required by the legislation rather than extending freely across the SMSF's other assets.
From a lender's perspective, the finance assessment can involve the amount the fund is contributing, the proposed loan-to-value ratio, available liquidity after settlement and the income the lender is prepared to recognise for serviceability. Rental income and super contributions may be relevant, but their treatment can differ between lenders.
The legal documentation and transaction sequence also deserve early attention. Your solicitor, accountant and other SMSF professionals should advise on the legal, tax and superannuation aspects, while Ausfirst can explain the lender's requirements and coordinate the finance component.
Trustees preparing an application can also consider the information lenders may expect before they prepare for SMSF approval, particularly where fund records, property details or holding-trust documentation need to be brought together.
CURRENT BORROWING RULES
Accurate as of September 2026. The rules applying to affected new LRBAs involving real property changed on 10 August 2026.
Schedule 5 of the Treasury Laws Amendment (Tax Reform No. 1) Act 2026 amended section 67A of the Superannuation Industry (Supervision) Act 1993. For affected arrangements involving real property entered into from 10 August 2026, the asset must satisfy the business real property requirement.
Business real property is a defined superannuation concept rather than simply another name for any commercial property. The Australian Taxation Office explains in its business real property guidance that business real property broadly involves eligible interests in real property used wholly and exclusively in one or more businesses, subject to the applicable statutory rules and the circumstances of the property.
For an affected LRBA entered into from 10 August 2026, a standard residential investment property would not ordinarily satisfy the new business real property requirement. That is different from saying an SMSF can never hold residential property: the restriction here concerns borrowing under the affected new LRBA provisions.
The legislation includes transitional treatment for specified arrangements entered into before commencement. It also preserves specified refinancing arrangements and certain acquisitions associated with pre-commencement arrangements, subject to the statutory conditions.
Because the legislative position can depend on timing and the particular transaction, trustees should obtain appropriate legal, taxation and SMSF advice before relying on a transitional provision. Ausfirst can assess the finance once the proposed structure and transaction are understood.
An SMSF lender may consider the proposal as a whole rather than relying on one figure. Requirements can vary between lenders, particularly where the security is commercial or the fund has a more involved financial position.
Ausfirst has access to a broader panel of more than 40 lenders, including banks and non-bank lenders. Not every lender in that panel offers SMSF finance, so we focus on the lenders whose current policy may be relevant to the particular fund, property and proposed borrowing.
Lender differences can include acceptable property types, maximum LVRs, liquidity calculations, servicing treatment, contribution evidence, loan terms, interest rates, fees, guarantees and documentation requirements.
This can be particularly relevant for Sunshine Coast business owners considering their own premises. An office, warehouse or other commercial property may sit within one lender's acceptable SMSF policy while another lender may take a different view of the security, lease or servicing position.
Differences in lender policy can have a practical impact when comparing a proposed SMSF loan. We look at those policies before an application is lodged rather than assuming that a lender suitable for one fund will also suit another.
A local business owner may be considering eligible premises through an established SMSF. We can assess the lending side, including lender appetite, valuation, servicing and finance documentation, while your other advisers address the superannuation, legal and taxation requirements. For property acquired outside super, we also assist with commercial property loans.
An existing SMSF loan may warrant review where the lender's product, pricing or policy no longer suits the fund. Where refinancing is legally available, we can compare relevant refinancing loan options and assess the proposed replacement lender's requirements.
Not every property transaction sits inside an SMSF. Where a property is being acquired through another structure, borrowing requirements may differ, and options such as property trust loans may need to be considered separately from SMSF finance.
A business-premises transaction may involve a broker, accountant, solicitor and SMSF administrator before settlement. Understanding the lender's documentation and timing requirements early can help the finance component fit more smoothly with the work being completed by the other advisers.
Lending considerations can differ when an SMSF is buying an office, warehouse or similar asset. The requirements for SMSF business premises can depend on the property, its use, the fund and the lender's policy.
We start with the property or refinancing proposal, where your SMSF currently stands and what you need from the finance.
We identify the fund, financial, property and supporting information that relevant lenders are likely to request.
We assess current SMSF lending policies and compare options that may fit the fund, security and proposed borrowing structure.
Where appropriate, we can liaise with your accountant, solicitor, financial adviser or SMSF administrator about lender requirements while they advise on matters within their respective professional scopes.
Once you choose to proceed, we prepare the finance application, communicate with the lender and assist through the lending approval and settlement process, subject to lender assessment and conditions.
After settlement, the loan may be reviewed later if the fund's circumstances, lender products or available refinancing options change.
Ausfirst is based at Suite 3/74 Bulcock Street, Caloundra QLD 4551. That gives Sunshine Coast clients the option of local, in-person contact rather than relying solely on a distant call centre or online service.
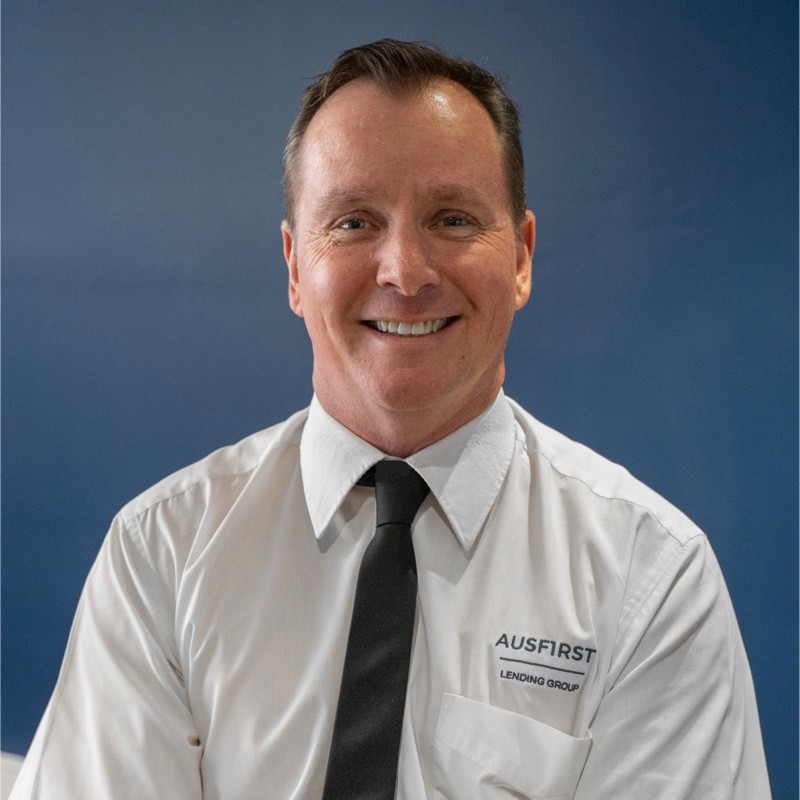
Richard Luke, Director of Ausfirst Lending Group, brings more than 30 years of finance and lending experience. His work includes property and more involved lending structures, and clients can deal directly with an experienced broker throughout the finance process.
Ausfirst works across commercial, investment, trust and SMSF-related lending. That broader finance experience can be useful where a proposal involves several entities, a business property or documentation that needs to be coordinated in a particular sequence.
Our broader panel includes more than 40 lenders. We do not suggest that every lender offers SMSF finance; instead, we look at which current policies may warrant consideration for the specific fund and security.
Ausfirst Lending Group was recognised as a finalist in the 2024 Sunshine Coast Business Awards under the Professional Services category. We treat that as a local trust signal rather than a claim that an award guarantees a particular lending outcome.
YOUR LOCAL BROKER
Richard Luke is Director of Ausfirst Lending Group and brings more than 30 years of experience across finance and lending. Based with the Ausfirst team in Caloundra, Richard works across SMSF, commercial and other structured property lending, including applications where lender policy or documentation may require closer attention.
His professional background includes lending experience with Commonwealth Bank, a Graduate Diploma in Business from the University of Queensland and a Diploma of Financial Planning (RG146), alongside earlier university studies in law. He has been a Director of Ausfirst Lending Group since 2016.
For Sunshine Coast SMSF clients, Ausfirst's local presence provides the option of discussing the lending proposal with Richard and the team in person where an appointment is appropriate, as well as by phone or online. Richard can help assess the proposal from a finance perspective, compare relevant lender policies and oversee the lending process through to settlement, while working alongside the client's other SMSF professionals where required.
Ausfirst's published client stories are general lending experiences rather than SMSF-specific case studies, so they are not presented as evidence of an SMSF outcome.
“Having that relationship with Rich now, he knows what we're like and what we're looking for.”
“If you don't have someone like Rich in your life, it can be quite a daunting task trying to negotiate or navigate through different loans and products.”
Published Ausfirst client case study concerning broader lending services, not an SMSF loan.
Our Sunshine Coast office is at Suite 3/74 Bulcock Street, Caloundra QLD 4551. Current Ausfirst information lists the office as open Monday to Friday, with appointments available.
You can also speak with us by phone or online if getting to Caloundra is inconvenient. The important part is having enough information about the fund and proposed transaction for us to assess the lending position and explain what a lender may require.
If you are considering an SMSF property purchase or reviewing an existing loan, we can look at how relevant lenders may assess the fund, proposed property and borrowing requirement before you decide how to proceed.
We can then compare relevant lender policies and manage the finance component alongside your other SMSF professionals, subject to current legislation and lender assessment.
SMSF LOANS SUNSHINE COAST FAQs
SMSF borrowing remains possible through qualifying limited recourse borrowing arrangements, subject to the applicable legislation. For affected arrangements involving real property entered into from 10 August 2026, the asset must satisfy the business real property requirement, subject to the applicable transitional provisions.
A standard residential investment property would not ordinarily meet the business real property requirement applying to an affected new LRBA entered into from 10 August 2026. Transitional provisions may apply to specified earlier arrangements, so legal and SMSF advice may be appropriate where an existing transaction is involved.
Deposit requirements can differ between SMSF lenders. The amount may depend on the lender, property, accepted valuation, maximum LVR and any post-settlement liquidity requirement.
Business premises may potentially be acquired through an SMSF where the transaction and property satisfy the applicable superannuation requirements. Whether a particular property qualifies as business real property depends on the relevant facts and circumstances and should be confirmed with appropriately qualified legal, tax and SMSF professionals, while Ausfirst can assess the lending requirements.
No. Lender participation and policy can change, and not every lender on Ausfirst's broader panel offers SMSF finance. We assess which lenders may have relevant policies for the particular fund, property and borrowing proposal.
Refinancing may be possible depending on the existing arrangement, current legislation and the replacement lender's requirements. The 2026 amendments preserve specified refinancing arrangements relating to pre-commencement borrowing arrangements, subject to the statutory conditions.
Ausfirst Lending Group is based at Suite 3/74 Bulcock Street, Caloundra QLD 4551. Local appointments may be available, and clients can also work with the team by phone or online.
The information above is general in nature and is accurate as of September 2026. It does not take into account your objectives, financial situation or needs and does not constitute personal financial, investment, tax or legal advice. SMSF rules, lender policies, rates, fees and assessment requirements can change, and outcomes are subject to lender assessment. Consider obtaining independent financial, taxation and legal advice appropriate to your circumstances. This content is subject to Ausfirst Lending Group/broker review before publication.






Whether you're buying your first home, refinancing, or exploring loan options through a trust or SMSF, we’re here to guide you every step of the way. As your trusted Mortgage Broker on the Sunshine Coast, we offer personalised advice tailored to your needs.


At Ausfirst Lending Group, we understand that medical and healthcare professionals need more than just a loan—they need a lending partner who appreciates their unique journey. Whether you're a doctor, nurse, dentist, or allied health specialist, we provide tailored home loan solutions with personal guidance, LMI waivers, and flexible options that fit your career and lifestyle. With Richard’s 30+ years of hands-on broking experience, we ensure your loan process is managed with care, transparency, and expertise from start to finish


Educators play a vital role in shaping future generations, and we’re here to ensure their home loan journey is just as rewarding. Whether you're a school teacher, early childhood educator, university lecturer, or support staff member, we offer home loan solutions designed to recognise your dedication to the community. From exclusive lending benefits to flexible loan structures, we simplify the process so you can focus on what you do best—teaching and supporting others.
For those who serve and protect—whether in law enforcement, emergency services, legal professions, or defence—navigating the home loan process should be as straightforward as possible. We offer tailored mortgage solutions that acknowledge the unique demands of your profession, providing structured lending benefits, flexible options, and personalised support.
From police officers and firefighters to lawyers and defence personnel, we’re here to simplify your path to homeownership with solutions designed around your service.