A lower interest rate
Even a small rate reduction can add up to real savings over the life of your loan.
SWITCH TO A BETTER-FITTING LOAN
Your loan isn’t set for life.
Make sure it still fits.
Rates, features and your circumstances change. Staying on the same loan without a review can cost you. We compare your current loan with options from our lender panel and show whether switching is worth it. Personal guidance from Ausfirst Lending Group’s mortgage brokers in Brisbane and on the Sunshine Coast.
Excellent · 35 Google reviews
WHAT DOES CHANGING HOME LOANS MEAN?
Switching means moving from your current mortgage to one that better suits you, either with your existing lender or a new one. It’s often driven by rate changes, new circumstances or the need for more flexibility.
Even a small rate reduction can add up to real savings over the life of your loan.
Offset accounts, redraw or penalty-free extra repayments can give you more control.
Move between fixed and variable, or split your loan to balance certainty and flexibility.
Haven’t reviewed your loan in a while? We’ll compare it with today’s options and tell you if staying put makes more sense.
Get a free loan reviewWHEN TO CONSIDER A SWITCH
A renovation, a growing family, a move to remote work or converting your home to an investment can all mean your loan needs to change too.
A lower rate or longer term can reduce repayments. A longer term usually means more interest overall.
Turning your home into an investment? An investment loan may better match your new goals.
Switching to a shorter term or adding an offset can help you clear the debt faster, if the repayments suit your budget.
Mortgage brokers providing regulated credit assistance must act in your best interests, considering costs, features and your needs.
A QUICK COMPARISON
| What you compare | Stay and negotiate | Switch lenders |
|---|---|---|
| Rate | One retention offer | Options across our panel |
| Paperwork | Usually minimal | A new application |
| Costs | Usually low | Discharge, setup, possibly LMI |
| Features | That lender’s range | A wider choice |
With a strong credit history and at least 20% equity, your current lender may match a competitor. We help you compare both paths.
Compare my optionsWILL YOU ACTUALLY SAVE?
Switching only pays off once your savings outweigh the costs of moving. The faster you reach that point, the stronger the case for switching.
We include every cost, from discharge and application fees to any LMI, so you see the real result.
Illustration only, not a quote. Assumes principal and interest repayments over the same remaining term and a rate that stays the same. Enter your own estimate of switching costs.
Check my actual optionsBEFORE YOU SWITCH
Switching can save you money, but some offers look better than they are. We check the detail before you commit.

A waived fee or cashback can come with a higher rate. Compare the comparison rate and total cost, not just the incentive.
Some lenders reset your loan to a full 25 or 30 years. That lowers repayments but can increase total interest unless you keep your original timeline.
Break costs, discharge and application fees can reduce your savings. With less than 20% equity, you may pay LMI again, even if you paid it on your current loan.
A new application triggers a credit check. The impact is usually minor with a healthy credit history, but several applications close together can add up.
Fees, LMI and lender offers vary and can change. Confirm current costs with each lender before applying.
Let’s run your numbers. We’ll compare your current loan with suitable options, including every cost of switching.
Review my loanHOW TO SWITCH
A clear plan makes switching smoother. Once you apply, the process typically takes four to six weeks.
Lower repayments, better features or paying off your home sooner. Your goal guides the right loan.
Check your rate, fees, features, any exit or break costs and how much equity you’ve built.
Let them know you’re shopping around. They may match or beat a competing offer.
Weigh rates, fees and features across lenders, and check the savings outweigh switching costs.
THE RIGHT STRUCTURE MATTERS
The right features depend on how you use your loan. We help you compare them against your budget and plans.
Reduce the balance used to calculate interest while keeping your savings accessible.
Withdraw extra repayments you’ve made if you need them later.
Make additional repayments without penalty to reduce interest and your loan term.
Fix part of your loan and keep the rest variable to balance certainty and flexibility.
Planning a renovation, a family change or turning your home into an investment? We’ll factor that into your new loan.
Talk about my plansFROM FIRST CHAT TO SETTLEMENT
We compare your options, manage the paperwork and keep you informed until your new loan settles.
UNDERSTAND
Meet by phone, Zoom or in person. We look at your current loan and what you want to change.
GATHER
We collect income documents, loan statements and details of your debts and equity.
ANALYSE & PLAN
We compare your current lender’s offer with suitable alternatives, including every switching cost.
APPLY
If switching makes sense, we prepare your application and liaise with the lender on valuation.
FINALISE
The new lender pays out your old loan. We keep you informed until settlement is complete.
SUPPORT
We review your loan as rates and your circumstances change, so it keeps fitting your life.
WHAT MAKES AUSFIRST DIFFERENT
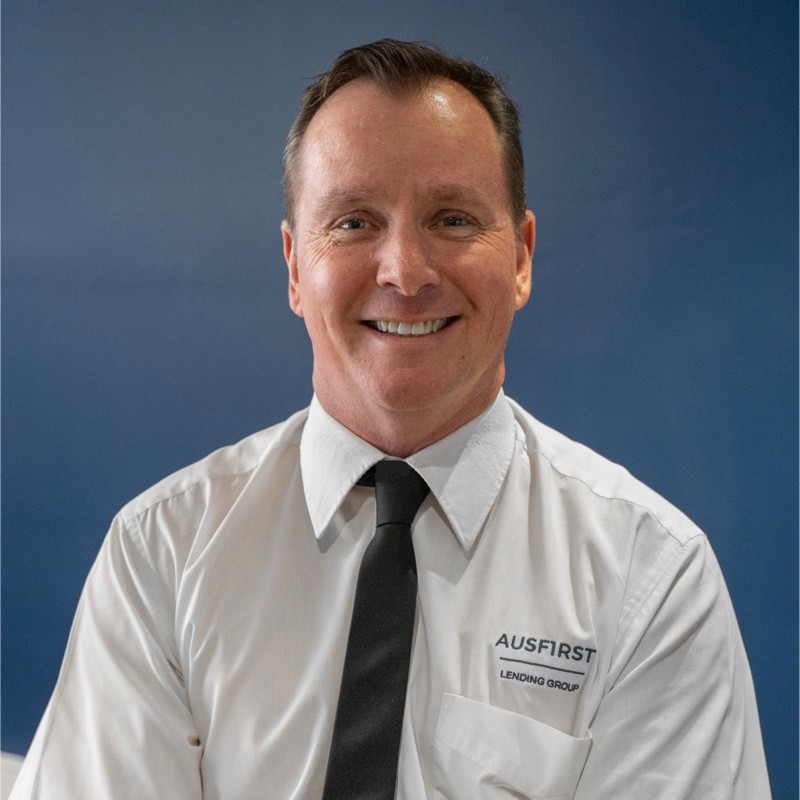
You’re looked after by someone who treats your financial success as his own.
Richard brings more than 30 years of hands-on broking experience. He takes the time to understand your current loan, circumstances and plans before comparing options from our panel.
Whether you want a sharper rate, lower repayments, better features or access to equity, we explain the costs and benefits clearly and tell you whether switching or staying is the better choice.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Debbie made the process of buying a new house frictionless, by providing excellent support throughout”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions we’re asked most about changing home loans. Your circumstances matter, so we’re happy to talk through the detail.
Ask about my loanReplacing your current mortgage with a new one, from your existing lender or a different one. It’s commonly called refinancing and is usually done for a lower rate, better features or more suitable terms.
You could, if the new loan has a lower rate or fewer fees. Compare the total cost of switching, including exit fees, application fees and any LMI, to see whether the savings outweigh the costs.
Possible costs include discharge fees, application fees, break costs on a fixed rate, government registration fees and LMI if your equity is under 20%.
Start with what you want to achieve, then compare offers, check every fee and estimate your break-even point. We can run the numbers with you.
Yes, and it’s worth doing. With a strong credit history and at least 20% equity, you may be able to secure a better deal without changing lenders.
Typically four to six weeks, covering application, approval and settlement. Timing depends on the lenders involved and how quickly documents are provided.
LET’S MAKE A START
Share a few details about your current loan and what you’d like to change. We’ll tell you what your options look like and whether switching makes sense.
A clear review of your current loan
Your break-even point worked out
Personal guidance from an experienced team
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, 9 am–5 pm
YOUR FREE LOAN REVIEW
Send our team a little about what you’d like to change.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form