Potential tax benefits
Interest on borrowings used to buy income-producing investments may be tax deductible.
RESTRUCTURE YOUR DEBT, BUILD YOUR WEALTH
Pay down your home loan.
Invest at the same time.
Debt recycling gradually turns non-deductible home loan debt into investment debt that may be tax deductible. It only works with the right loan structure. We set up the lending side and work alongside your accountant and financial adviser. Personal guidance from Ausfirst Lending Group’s mortgage brokers in Brisbane and on the Sunshine Coast.
Excellent · 35 Google reviews
WHAT IS DEBT RECYCLING?
You use equity or surplus cash to pay down your home loan, then borrow the same amount through a separate split to buy income-producing investments. Over time, your home loan shrinks while your investment debt grows.
Interest on borrowings used to buy income-producing investments may be tax deductible.
Investment income and tax savings can go back into your home loan, reducing it faster.
Grow an investment portfolio while you continue paying down your family home.
Already working with an accountant or adviser? We’ll coordinate with them so your loans match the strategy.
Start with a free chatHOW DEBT RECYCLING WORKS
Every strategy is different, but most follow the same cycle. The key is keeping personal and investment borrowing strictly separate.
Extra repayments or growth in your home’s value create usable equity.
A separate investment loan split funds income-producing assets, such as shares, managed funds or property.
Your non-deductible home loan shrinks as investment debt replaces part of it.
Investment income and potential growth help you repeat the cycle and speed up the strategy.
A QUICK COMPARISON
| What you compare | Standard home loan | Debt recycling |
|---|---|---|
| Home loan | All non-deductible | Shrinking over time |
| Investment debt | None | Growing; interest may be deductible |
| Structure | One loan | Separate loan splits |
| Record-keeping | Simple | Careful tracking needed |
Tax outcomes depend on your circumstances and current tax law. Get advice from your accountant or a licensed financial adviser.
Review my structureWHAT COULD IT MEAN?
Each dollar moved from your home loan into an investment split may change how its interest is treated for tax. Over several cycles, the effect can compound.
We build the lending structure. Your accountant or adviser confirms the tax and investment side.
Illustration only, not tax or financial advice. Assumes interest-only on the recycled amount for one year. Excludes the Medicare levy, investment returns, losses and fees. Deductibility depends on how funds are used and your circumstances.
Check my actual optionsSTRUCTURE IS EVERYTHING
Debt recycling depends on a clear line between personal and investment borrowing. One mixed transaction can cloud the tax treatment of a whole loan.
You need a lender that allows multiple loan splits, offsets linked to the right split and clean records for each. Not every lender’s products handle this well.
We compare lenders on these features, set up the splits and keep the structure reviewed as you recycle more debt.
Shares, funds and property can drop in value, and there’s no guarantee investments will produce positive returns. You still owe the full investment loan.
Rising rates increase repayments on both splits. If income or investment returns fall, cash flow can tighten quickly.
We provide credit assistance only. We don’t give tax or investment advice; speak with your accountant or a licensed financial adviser before starting.
Let’s review your current loan. We’ll check whether your structure and lender suit debt recycling.
Check my next stepsIS IT RIGHT FOR YOU?
It isn’t for everyone, particularly if your cash flow is tight or you’re uncomfortable with investment risk. It may suit homeowners who have:
Substantial equity in your principal place of residence.
Consistent savings or surplus household income each month.
Comfort with long-term investing and market ups and downs.
An accountant or financial adviser to guide the strategy.
THE RIGHT STRUCTURE MATTERS
The right features keep your borrowing separate and easy to track. We compare lenders on how well they support this setup.
Separate splits for your home loan and each investment purpose.
Linked to your home loan split, not the investment split.
Borrowing through a fresh split keeps a clearer record than redraw.
Choose rate types for each split to suit your cash flow.
Already have a mortgage with a lender that can’t split cleanly? We’ll compare refinancing options.
Talk about my loanOUR DEBT RECYCLING PROCESS
We set up the lending side of your strategy carefully, in step with your accountant or adviser.
UNDERSTAND
We discuss your goals, current loans and investment plans, and who your advisers are.
GATHER
We assess your mortgage structure, available equity and borrowing capacity.
ANALYSE & PLAN
We plan a multi-split structure that supports the strategy your adviser recommends.
APPLY
We find lenders with the split and offset features you need, and lodge the application.
FINALISE
We manage settlement and make sure each split is set up correctly.
SUPPORT
We review your structure as you recycle more debt and your circumstances change.
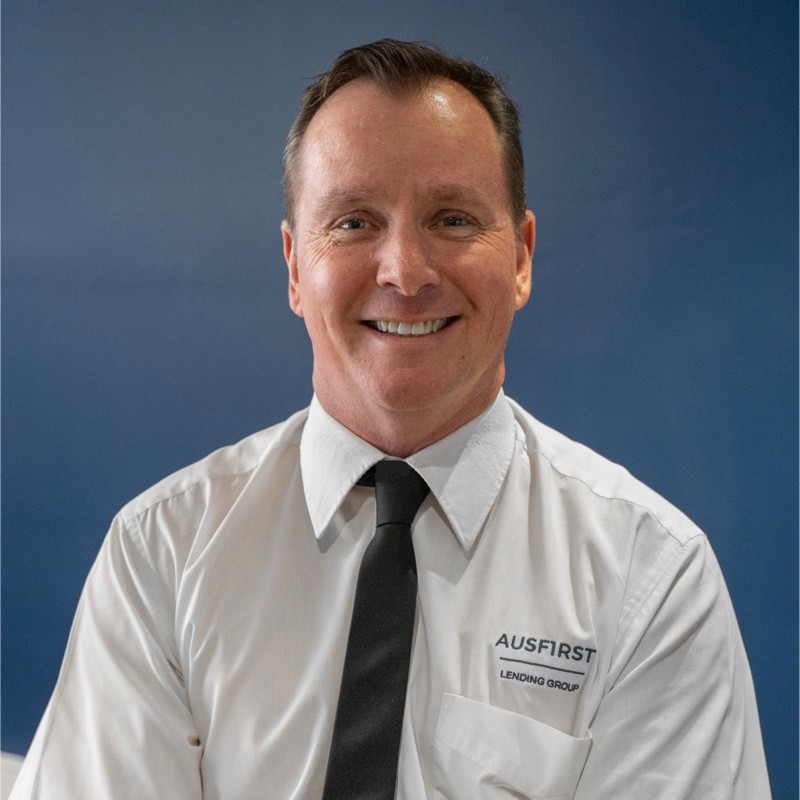
WHAT MAKES AUSFIRST DIFFERENT
You’re looked after by someone who treats your financial success as his own.
You deal directly with Richard, the founder, who has more than 30 years of lending experience across Queensland. He takes the time to understand your finances and builds the loan structure your strategy needs.
Unlike larger brokerages, you won’t be passed between staff. Richard manages your loans personally and works with your accountant or adviser from setup to ongoing reviews.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Debbie made the process of buying a new house frictionless, by providing excellent support throughout”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions we’re asked most about debt recycling. Your circumstances matter, so we’re happy to talk through the detail.
Ask about my situationNo. It generally suits homeowners with equity, stable income and a long-term investment plan. Consider your goals, risk tolerance and cash flow, and get advice from your accountant or financial adviser first.
Yes. Recycled funds can go towards income-producing assets such as investment property or shares. Your adviser can help you decide which suits your goals; we structure the lending to support it.
Yes. It’s most commonly used by homeowners with an existing mortgage and built-up equity. Your loan may be restructured into separate splits, and we’ll review whether your current lender suits the setup.
We strongly recommend it. Debt recycling involves tax and investment decisions that a broker can’t advise on. We work alongside your accountant or adviser on the lending side.
Investments can fall in value, rates can rise and returns aren’t guaranteed. Poor structuring can also affect deductibility. Make sure the strategy fits your goals and risk tolerance before starting.
The strategy relies on keeping personal and investment borrowing separate. We compare lenders on split and offset features, set up the structure correctly and coordinate with your advisers.
LET’S MAKE A START
Tell us about your current loan and your plans. We’ll review your structure, explain what a debt recycling setup needs and work with your adviser on the detail.
Your current loan structure reviewed
Lenders compared on split and offset features
Coordination with your accountant or adviser
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, 9 am–5 pm
YOUR FREE STRUCTURE REVIEW
Send our team a little about your plans.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form