Bridge the gap
Cover costs while invoices and progress claims are still outstanding.
CASHFLOW LENDING FOR TRADIES
Full order book, tight account?
Bridge the gap.
Running a trade business means chasing invoices, paying suppliers and wages, and keeping enough back for yourself. Cashflow lending looks at your work pipeline and incoming payments, not just property. We match short-term funding to how your jobs actually pay, for trade businesses on the Sunshine Coast and across Australia.
Excellent · 35 Google reviews
WHY TRADE CASHFLOW RUNS TIGHT
A job’s half done, the last progress claim is pending, the supplier wants paying before the next delivery and the client wants it finished by Friday. Nothing has gone wrong; that’s how trade work gets paid. Long payment terms leave busy businesses short, even with a full order book.
Cover costs while invoices and progress claims are still outstanding.
Fund materials, wages and urgent business costs without stopping work.
Structure funding around incoming client payments and job milestones.
No property to offer as security? Cashflow lenders focus on the strength and timing of the money coming in, not your house or gear.
Start with a free chatTYPES OF CASHFLOW FINANCE
Cashflow lending is a family of products. The right one depends on how and how often the gap shows up.
A flexible limit on your business account, drawn only when needed. Suits short, irregular gaps.
A revolving facility you can redraw as you repay. Useful when the same timing gap keeps coming back.
Funding advanced against invoices you’ve issued, so the cash arrives before the client pays.
A lump sum over a set term without property security. Priced higher for the risk, but quick to arrange.
A QUICK COMPARISON
| What you compare | Bank loan | Cashflow lending |
|---|---|---|
| Assessed on | Financials and security | Incoming work and invoices |
| Security | Usually property | Often none |
| Speed | Usually weeks | Some lenders in 1–2 days |
| Cost | Lower rates | Higher rates |
Rates, terms and speed vary by lender and your circumstances. Approval isn’t guaranteed.
Compare my optionsKNOW YOUR NUMBERS
Cashflow funding costs more than secured finance, so it should be short and matched to a real payment. The test is simple: does the cost of the funding make sense against the profit on the job?
We look at the job, the payment timing and the total cost before recommending a product.
Illustration only, not a quote. Simple interest for the period shown. Excludes establishment fees, line fees and GST. Rates vary widely between lenders and products.
Check my actual optionsWHAT CASHFLOW LENDING COVERS
Used with a clear repayment plan, it also keeps personal credit cards and the home loan out of the business, and smooths quieter stretches like the wet season or the Christmas shutdown.
Materials or supplier accounts before an earlier job has paid. Wages or subbies while a client payment is weeks away. The tool or vehicle that breaks down mid-job.
It also lets you take on a larger contract without scraping funds together to start. Paperwork not ready? A low doc business loan may cover the same gaps.
Some lenders release funds within one to two business days, usually without property security, which keeps personal risk lower. Repayments can follow your client payment schedule rather than a fixed calendar.
Rates are usually higher than secured finance, and repayments lean on projected income, so forecasts must be realistic. A patchy pipeline can turn funding into pressure. Borrowing more than the job can repay is the main trap.
General information only. Lending is subject to lender criteria, terms, conditions and eligibility.
Let’s size it right. We’ll match the amount and term to the job, so the funding clears when your invoice does.
Check my next stepsHOW LENDERS ASSESS YOU
A lender funding against your income rather than property focuses on four things.
Signed contracts, purchase orders and a booked pipeline show the money is genuinely coming.
How the account runs day to day, including dishonours or overdrawn periods.
Current loans, leases and tax positions affect how much more you can carry.
Where repayments come from and when. A realistic plan beats an optimistic one.
WHAT YOU NEED TO APPLY
You don’t need a mountain of paperwork, but lenders want to see real work coming in. Requirements vary by lender and your circumstances.
Plus GST registration if you’re over the threshold.
Recent invoices, signed contracts or job schedules.
Usually the last three to six months of business statements.
BAS or tax documents, plus a short forecast of upcoming jobs and payments.
Need a ute, tools or a home loan too? We help tradies with self-employed home loans and equipment finance.
Explore tradie home loansHOW CASHFLOW LENDING WORKS
Often through specialist lenders rather than the major banks, with repayments lined up with your progress payments.
UNDERSTAND
What you’re funding, when you need it and what the pipeline looks like.
REVIEW
We look at upcoming invoices, contracts or service agreements rather than security over your home, ute or gear.
COMPARE
We compare specialist lenders and products against the size and timing of the gap.
PREPARE
We pull together statements, BAS and your forecast so the lender can assess quickly.
FUND
Once the file is ready, some lenders can approve and release funds promptly.
REPAY
A short-term boost that clears when your invoice does, not long-term debt.
WHAT MAKES AUSFIRST DIFFERENT
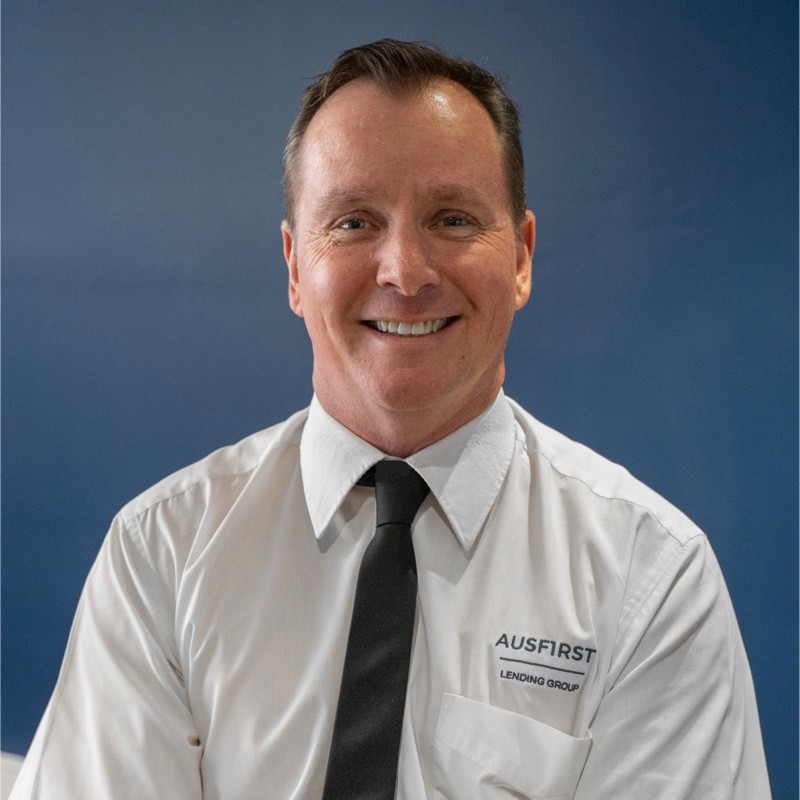
You’re looked after by someone who treats your financial success as his own.
Richard brings more than 30 years of lending experience. He takes the time to understand your business, income cycle and goals before comparing cashflow lending options from our panel.
Whether it’s working capital, materials, wages, seasonal dips or a bigger contract, you get clear advice, regular updates and support from application to funding.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Thanks to Richard and Debbie and the team at Ausfirst Lending… They are the gurus of self employed loans. I highly recommend their services.”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
CASHFLOW LENDING FAQS
The questions builders and tradies ask most about cashflow funding. Every business is different, so we’re happy to talk through the detail.
Ask about my businessOften, yes. Banks struggle with the lumpy income of trade work. We work with specialist lenders that assess your upcoming jobs and contracts, not just past financials, so a business that looks uneven on paper may still have options.
Possibly. Many specialist lenders consider businesses with ATO debt, especially if it’s on a payment plan, and late invoices are common in trades. Lenders weigh the whole picture, so tell us upfront and we’ll find lenders whose policies fit.
Some specialist lenders can approve and fund within one to two business days once the file is complete. Having statements, BAS and invoices ready makes the biggest difference to speed.
It can be if it’s used wrongly. Rates are higher and terms short, so it works best for a specific gap with a clear repayment source. Borrowing more than the job can repay, or funding a patchy pipeline, adds pressure.
Each lender has different criteria, rates, fees and speed. We compare specialist lenders across our panel, match the product to the gap and present your business clearly, saving you applying to lenders one by one.
General information only. It doesn’t consider your objectives, financial situation or needs and isn’t financial, tax or legal advice. Lending is subject to lender criteria, terms, conditions and eligibility.
GET CASHFLOW FUNDING SORTED
You built the business with your own hands. A timing gap shouldn’t stop you taking the next job or paying the team. A yes to any of these is a good reason to look at your options.
Turning down work because of upfront costs?
Paid weeks or months after the job’s done?
Steady income overall, bumpy week to week?
Want to grow without risking your house or ute?
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, 9 am–5 pm
YOUR CASHFLOW CHAT
What you’re funding, when you need it and what the pipeline looks like.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form