Buy with a small deposit
Borrow more with a smaller deposit, or in some cases none at all.
WITH A LITTLE HELP FROM FAMILY
No big deposit yet?
Family equity may help.
A family guarantee uses equity in a family member’s property as extra security for your loan. It can reduce your LVR and may help you avoid LMI. We find lenders that offer guarantees and make sure both you and your guarantor understand the commitment. Personal guidance from Ausfirst Lending Group’s mortgage brokers in Brisbane and on the Sunshine Coast.
Excellent · 35 Google reviews
HOW A FAMILY GUARANTEE WORKS
A family member, such as a parent or sibling, offers part of their property as additional security for your loan. The guarantee covers part of the loan, usually the amount above 80% of the purchase price, so the lender sees less risk.
Borrow more with a smaller deposit, or in some cases none at all.
If the overall LVR meets the lender’s requirements, you may not pay LMI.
The added security can bring your loan within lender limits.
Outcomes depend on the guarantor’s equity and each lender’s policy. We check both before you apply.
Start with a free chatWHO CAN BE A GUARANTOR?
Guarantor rules differ between lenders. We confirm whether your intended guarantor is likely to meet specific lenders’ requirements.
The most commonly accepted guarantors, often using equity in their own home.
Accepted by many lenders, subject to their own financial position.
Some lenders accept a spouse or partner as guarantor in certain circumstances.
Lenders want guarantors who understand the risks and could manage if the loan defaulted.
A QUICK COMPARISON
| What you compare | Pay LMI | Family guarantee |
|---|---|---|
| Your deposit | Often 5–10%+ | Little or none |
| LMI | Usually payable | Often avoided |
| Family risk | None | Guarantor’s property is security |
| Paperwork | Standard | More steps, legal advice |
Lender policies on guarantees, LVRs and costs vary. The guarantor should get independent legal and financial advice.
Compare my optionsHOW EQUITY IS EVALUATED
Lenders value the guarantor’s property, subtract their existing mortgage and check the combined LVR once the guarantee is added. Many look for that to stay around 80% or below.
We work out the guarantee amount and the guarantor’s position before anyone commits.
Illustration only, not a borrowing assessment. Guarantee covers your loan above 80% of the price; some lenders also allow it to cover buying costs. Valuations and lender limits vary, and you must still afford the repayments.
Check my actual optionsWHAT YOUR GUARANTOR TAKES ON
Your guarantor’s property is being used to support your loan. Everyone should understand the legal and financial implications before signing.

If you can’t repay the loan, the lender can call on the guarantor for the guaranteed amount, and could ultimately take action against their property.
Lenders usually require the guarantor to get independent legal advice. A guarantee can also affect their own future borrowing.
Most family guarantees are limited to a set amount, rather than the whole loan. That caps the guarantor’s exposure.
Once your loan falls to around 80% of your property’s value, through repayments or growth, the guarantee may be released. We can review it when you’re ready.
Guarantee terms and release conditions vary by lender. Approval is subject to lender assessment.
Let’s make sure everyone’s clear. We coordinate documents between you and your guarantor and explain each person’s commitments.
Check my next stepsASSESSING ELIGIBILITY
Each of these affects your eligibility and the guarantee structure a lender offers.
You still need to afford the full loan repayments yourself.
How much equity is available in the guarantor’s property.
Whether their property is mortgaged, and with which lender.
The guarantor’s ability to manage obligations if the loan defaults.
WHEN IT MIGHT SUIT
A guarantee isn’t right for every family. These are the situations where it tends to work best.
You’re buying without the full 20% deposit saved.
The guarantor owns property with significant equity or little debt.
The guarantor is financially independent and aware of the risks.
Your income comfortably covers the repayments on the full loan.
No family guarantee available? A low deposit loan or a professional LMI waiver may be other paths.
Explore low deposit loansSTEPS TO APPLY
Family guarantee loans involve more steps than standard loans. Careful planning reduces the chance of delays.
UNDERSTAND
We meet with you, and your guarantor if they like, to understand everyone’s position.
CHECK
We check the guarantor’s property meets lender criteria and estimate its equity.
COMPARE
We compare lenders that support family guarantees and their LVR limits.
ADVICE
Your guarantor receives independent legal and financial advice before signing.
APPLY & SETTLE
We coordinate documents between you, your guarantor and the lender through to settlement.
RELEASE
As your equity grows, we help you release the guarantee.
WHY CHOOSE AUSFIRST LENDING GROUP
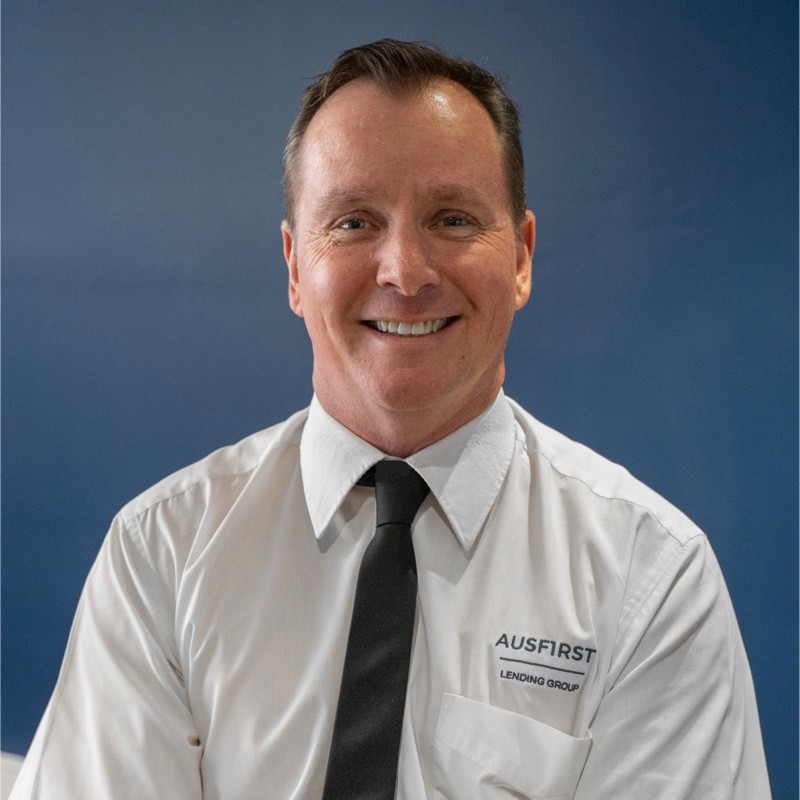
You’re looked after by someone who treats your financial success as his own.
Richard brings more than 30 years of hands-on broking experience. He takes the time to understand both your position and your guarantor’s before comparing lenders that offer family guarantees.
From the first purchase to releasing the guarantee years later, you get clear advice and a long-term lending partner on the Sunshine Coast and in Brisbane.
WHAT OUR CLIENTS SAY
“I would describe Richard and Ausfirst Lending as friendly, insightful, prompt and diligent. A pleasure to deal with.”
“Debbie made the process of buying a new house frictionless, by providing excellent support throughout”
“I received very prompt responses to all of my questions and the team ensured that my application was processed in a timely manner. The service was brilliant!”
Excerpts from client reviews displayed on Ausfirst’s website. These reflect individual experiences.
LET’S CLEAR THINGS UP
The questions borrowers and guarantors ask most. Every family is different, so we’re happy to talk through the detail with both of you.
Ask about a guaranteeA loan where a family member uses equity in their property as extra security for part of your loan. It can reduce your deposit and LVR, and may help you avoid LMI.
Some lenders allow it, and some let the guarantee cover buying costs too. You still need to show you can afford the repayments, and many lenders like to see some genuine savings.
Usually not. Most family guarantees are limited to a set amount. If you can’t repay, the lender can call on the guarantor for that amount.
Often parents, grandparents, guardians, siblings or spouses, depending on the lender. They must have enough equity and be financially independent.
The lender values their property, subtracts any existing mortgage and checks the combined LVR with the guarantee added, often aiming for about 80% or less.
Yes, usually once your loan falls to around 80% of your property’s value through repayments or growth. The lender will normally need a new valuation.
READY TO DISCUSS YOUR OPTIONS?
We can assess your eligibility, compare lenders and guide you and your guarantor through the process. No obligation, just an opportunity to explore what might be possible.
Guarantee amount and equity worked out
Lenders that offer guarantees compared
Both parties’ commitments explained
Suite 3/74 Bulcock St, Caloundra QLD 4551
Monday–Friday, 9 am–5 pm
YOUR FREE GUARANTEE CHAT
Send our team a little about you and your guarantor.
Review and send it from your email app to share your details with Ausfirst. Your enquiry has not been sent yet.
Open my email draftNo email app? Use our online contact form